SPY Options Are Pricing an $8.42 Move Into November 3 — Our Model Sees a Tighter Drift Lower
SPY options imply a $743.68–$760.52 range into the November 3 expiration, with puts in heavy demand and premium unusually rich. Our read is neutral with a bearish tilt. Here are the levels that matter and three defined-risk ways to trade the next session.
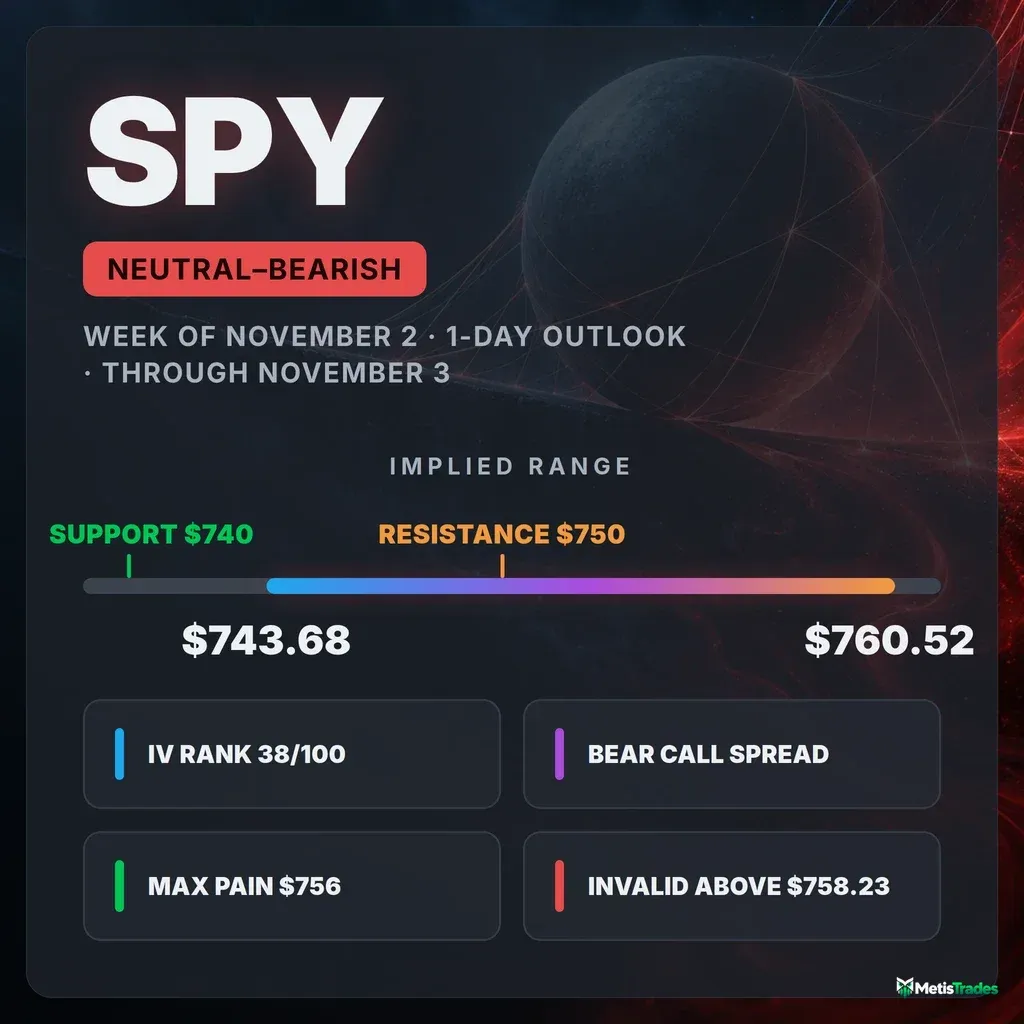
The options market implies a $743.68–$760.52 range into the November 3 expiration. Here's what's driving it and three defined-risk ways to trade it.
Published Monday, November 2, 2026 · Data as of Monday, November 2, 2026 close · Nightly update covering the next session (2026-11-03)
Explore the live SPY options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bearish tilt |
| Options-implied range (into November 3) | $743.68 – $760.52 (±$8.42, ±1.12%) |
| Spot / last close | $752.10 |
| Major support | $740.00 (put wall, November 3 expiration) |
| Major resistance | $750.00 (call wall, November 3 expiration); structural resistance at $758.23 |
| Max pain (November 3) | $756.00 |
| Dealer gamma regime (estimate) | Negative — hedging tends to amplify moves; flip level n/a (not computable today) |
| Volatility condition | Rising — IV rank 38/100 (ATM IV 16.99%) · premium rich: options are priced about 5.6 vol points above delivered movement |
| Technical check | Confirms (bearish, 2-day model; target $750.80, model range $747.90–$754.60) |
| Best-fitting strategy | Bear call credit spread above max pain, if SPY stays capped below $757 |
| Analysis invalidated if | SPY closes above $758.23 |
1 · What matters today
Our read of SPY options heading into the November 3 session is neutral with a bearish tilt. The main reason is a surge in demand for downside protection. Puts outtraded calls by more than 1.5 to 1 on Monday, which is unusually heavy for SPY. Puts are also priced far richer than calls compared with their recent norm. The options market is pricing a move of about $8.42 either way, the move implied by what straddles cost. That gives a range of roughly $743.68 to $760.52 for tomorrow's expiration. Options are also expensive relative to how much SPY has actually been moving, which favors collecting premium over buying it. The level that changes the picture is $758.23: a close above it means sellers lost control. The chart-based technical model points the same direction, with a modest drift toward $750.80.
2 · What the options market is pricing
What changed this week
SPY closed at $752.10 on Monday. That is down 1.73% over five sessions and down 2.93% over the past month, and it sits about 2.2% below its 20-day average. The options market got noticeably more nervous along the way. At-the-money implied volatility rose 15.8% over five sessions and 8.9% on Monday alone. Implied volatility is the market's estimate of how much SPY will move, baked into option prices.
Put/call open interest shows the same shift. Open interest means contracts currently held open. There are now 2.27 puts held open for every call. The 7-day average is 1.71 and the 14-day average is 1.54, so traders kept adding downside protection all week. The short-term trend read is bearish over the past week, while the one- and two-month reads are flat. Momentum also turned lower again on Monday, after briefly turning up on October 30. The pressure is near-term and fresh, not a long-running slide.
Among contracts that are still live, the 11/13 $745 puts showed one of the cleaner builds. Open interest rose by 13,608 contracts to 15,862, on volume of 58,620. On the other side, the large 11/20 $750 put position shrank by 12,338 contracts. Some of the existing protection was taken off even as new protection went on. Into Monday's own same-day expiration, the 11/02 $745 puts added more than 38,000 contracts of open interest before settling. That is settled history now, but it shows how strongly traders wanted protection near $745.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. Into the November 3 expiration it is ±$8.42 (±1.12%), a range of $743.68 to $760.52 around the $752.10 snapshot price. That one-day figure comes from the next-session at-the-money options, which carry about 21.4% implied volatility. That is well above the chain-wide 16.99% reading, because very short-dated options are where traders are paying up most.
| Expiration | Implied move | Range around $752.10 |
|---|---|---|
| November 3 (next session) | ±1.12% | $743.68 – $760.52 |
| November 4 | ±1.69% | $739.39 – $764.81 |
| November 6 | ±2.36% | $734.35 – $769.85 |
| November 20 | ±4.10% | $721.26 – $782.94 |
The ladder widens steadily rather than jumping at any one date. Through November 6, though, the short-dated options are priced hotter per day than the later rungs. That is consistent with near-term stress rather than one scheduled event.
Volatility
ATM implied volatility is 16.99%, up 37% over 30 sessions. Both its 30-day and 90-day averages sit near 13.5%, so volatility is clearly rising off a calm base.
The two yearly gauges tell slightly different stories:
- IV rank is 38/100. IV rank shows where today's IV sits within the past year's high-to-low range. At 38, it is in the lower half of that range, below the peaks of the past year's stress spikes.
- IV percentile is about 84. Today's IV is higher than about 84% of the past year's daily readings. SPY spent most of the year calmer than this.
The front-month term-structure read is unavailable today because of Monday's same-day expiration. Term structure means comparing option prices across different expiration dates. About 60 days out, IV sits near 16.6%.
Actual movement is speeding up too. Realized movement over the past five sessions runs about 1.3 times its 20-day pace, which is on the high side of normal for SPY. The VIX is at 18.89, in the lower third of its 52-week range. It tracks SPY's own IV very closely right now, so this is broad-market caution, not something specific to SPY.
Premium rich or cheap. The volatility risk premium is the gap between how much movement options are priced for and how much SPY has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them. Right now options are priced about 5.6 vol points above SPY's 20-day realized volatility of 11.35%. That gap ranks at the 94th percentile versus this stock's own recent readings, meaning it is richer than 94% of them. It has also widened quickly, from about 3.2 points on October 29 to 5.6 points now. That combination — IV rank 38 and a 94th-percentile premium over delivered movement — favors collecting premium in the next session rather than owning it.
Skew and sentiment
Skew means puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. Puts at the 25-delta point carry about 20.7% IV versus 14.4% for comparable calls. That is a gap of 6.3 vol points against a 60-day norm of 3.6. The 7-day average is about 4.8, so skew is stretched well past anything seen in recent weeks. Compared against this stock's own recent history, this is an unusually steep put premium for SPY.
Flow agrees with skew:
- Put/call volume ratio: 1.57. This ratio measures put activity relative to calls; above 1 means puts dominate. Its 7-day average is 1.13 and its 14-day average is 1.09. That is one of the most put-heavy days for SPY in recent history.
- Total option volume was about normal, at 0.97 times its 20-day average. Traders were not trading more overall; they were mostly buying puts.
- Short-dated sentiment is clearly negative. Options expiring within a week lean bearish, and the 8–30-day group leans even more so. Both are well below their 7-day averages. Longer expirations are split, so the overall read is mixed rather than uniformly bearish.
- One counter-signal: new call positions. Net new open interest leaned toward calls on Monday, and call-side sweeps slightly outnumbered put sweeps among the most unusual trades.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $781.62 | SPY is 3.78% below it — the ceiling of the year's range |
| Swing resistance | $776.26 | Upper structural pivot from recent swings |
| 20-day moving average | $769.33 | Price is 2.24% below — the short-term trend line overhead |
| 50-day moving average | $767.22 | Lost in the past week's slide |
| Expected-move ceiling (November 3) | $760.52 | Upper edge of the one-session implied range |
| Call wall (whole chain) | $760.00 | Heaviest call open interest across all expirations (63,874 contracts) |
| 100-day moving average | $759.49 | Medium-term trend marker sitting with the whole-chain call wall |
| Swing resistance | $758.23 | Nearest structural ceiling — this analysis's invalidation level |
| Max pain (November 3) | $756.00 | Where the most next-session option value would expire worthless |
| Spot (snapshot) | $752.10 | Monday's close |
| Call wall (November 3) / put wall (whole chain) / largest gamma strike | $750.00 | The densest strike in the chain — 260,457 puts across all expirations |
| Swing support | $746.81 | Nearest structural floor below the $750 pivot |
| Gamma cluster | $745.00 | Fifth-largest gamma strike; heavy put open interest |
| Expected-move floor (November 3) | $743.68 | Lower edge of the one-session implied range |
| Put wall (November 3) | $740.00 | Heaviest put open interest for the next session; second-largest gamma strike overall |
| Swing support | $734.61 | Lower structural pivot |
| 200-day moving average | $729.15 | Long-term trend still intact, 3.15% below |
| 52-week low | $629.28 | Floor of the year's range |
Positioning and unusual flow
A call wall or put wall is the strike with the biggest pile of open call or put contracts. These often act like magnets or barriers.
The next-session expiration has an unusual layout. Its call wall, at $750.00 with 9,634 contracts, sits below spot. Its put wall is $740.00, with 7,192 contracts. The whole-chain picture is different: its heaviest call strike is $760 and its heaviest put strike is $750. The $750 strike is therefore both the next-session call wall and the chain's biggest put pile. SPY ended Monday just above it.
Most of the November 3 call open interest at $750 is new. It went from 29 contracts to 9,634 in a day, so the strike now carries real two-sided weight. Max pain for November 3 is $756. Max pain is the price where the most option value would expire worthless, and expirations sometimes gravitate toward it. Here it sits about $4 above spot.
Dealer gamma describes how market makers hedge the options they've sold. One rough estimate puts that hedging in a negative regime, both for the November 3 expiration and for the chain as a whole. In this regime, their hedging tends to amplify moves rather than dampen them. The estimate could not locate a flip level today, so there is no clean price at which that behavior is expected to switch.
The most unusual non-expired flow:
- 11/04 $756 puts: 32,201 contracts traded against just 448 open — about 72 times the open interest — worth roughly $20.5 million in premium. Someone bought or sold in-the-money near-dated protection in size.
- 11/03 $764 calls: 43,620 traded against 1,095 open. These are cheap lottery-style upside contracts at about $0.20.
- 11/03 $760 calls: 64,719 traded against 3,775 open. These sit right at the top of the implied range.
The call activity is the reason our read stops at a tilt rather than a firm bearish call. Some traders are positioning for a snap-back.
3 · Technical check
The 2-day chart model is bearish, with a target of $750.80 and a projected range of $747.90–$754.60. Its reference price of $752.14 matches the options snapshot. That target sits inside the options-implied $743.68–$760.52 range and points the same direction as our tilt, so the technical read confirms.
Its two strongest pieces of evidence are trend strength and selling pressure. Trend strength (ADX) is 31 and rising, with sellers far stronger than buyers. Money-flow (CMF) sits at −0.40, a sign of heavy distribution. The model also flags an oversold RSI near 29 and price riding the lower Bollinger Band. It gives a 35% chance to a relief bounce toward $755–$756.50. Its key levels are support at $750.00 and resistance at $754.04, and its main bearish scenario is invalidated by a reclaim of about $756.
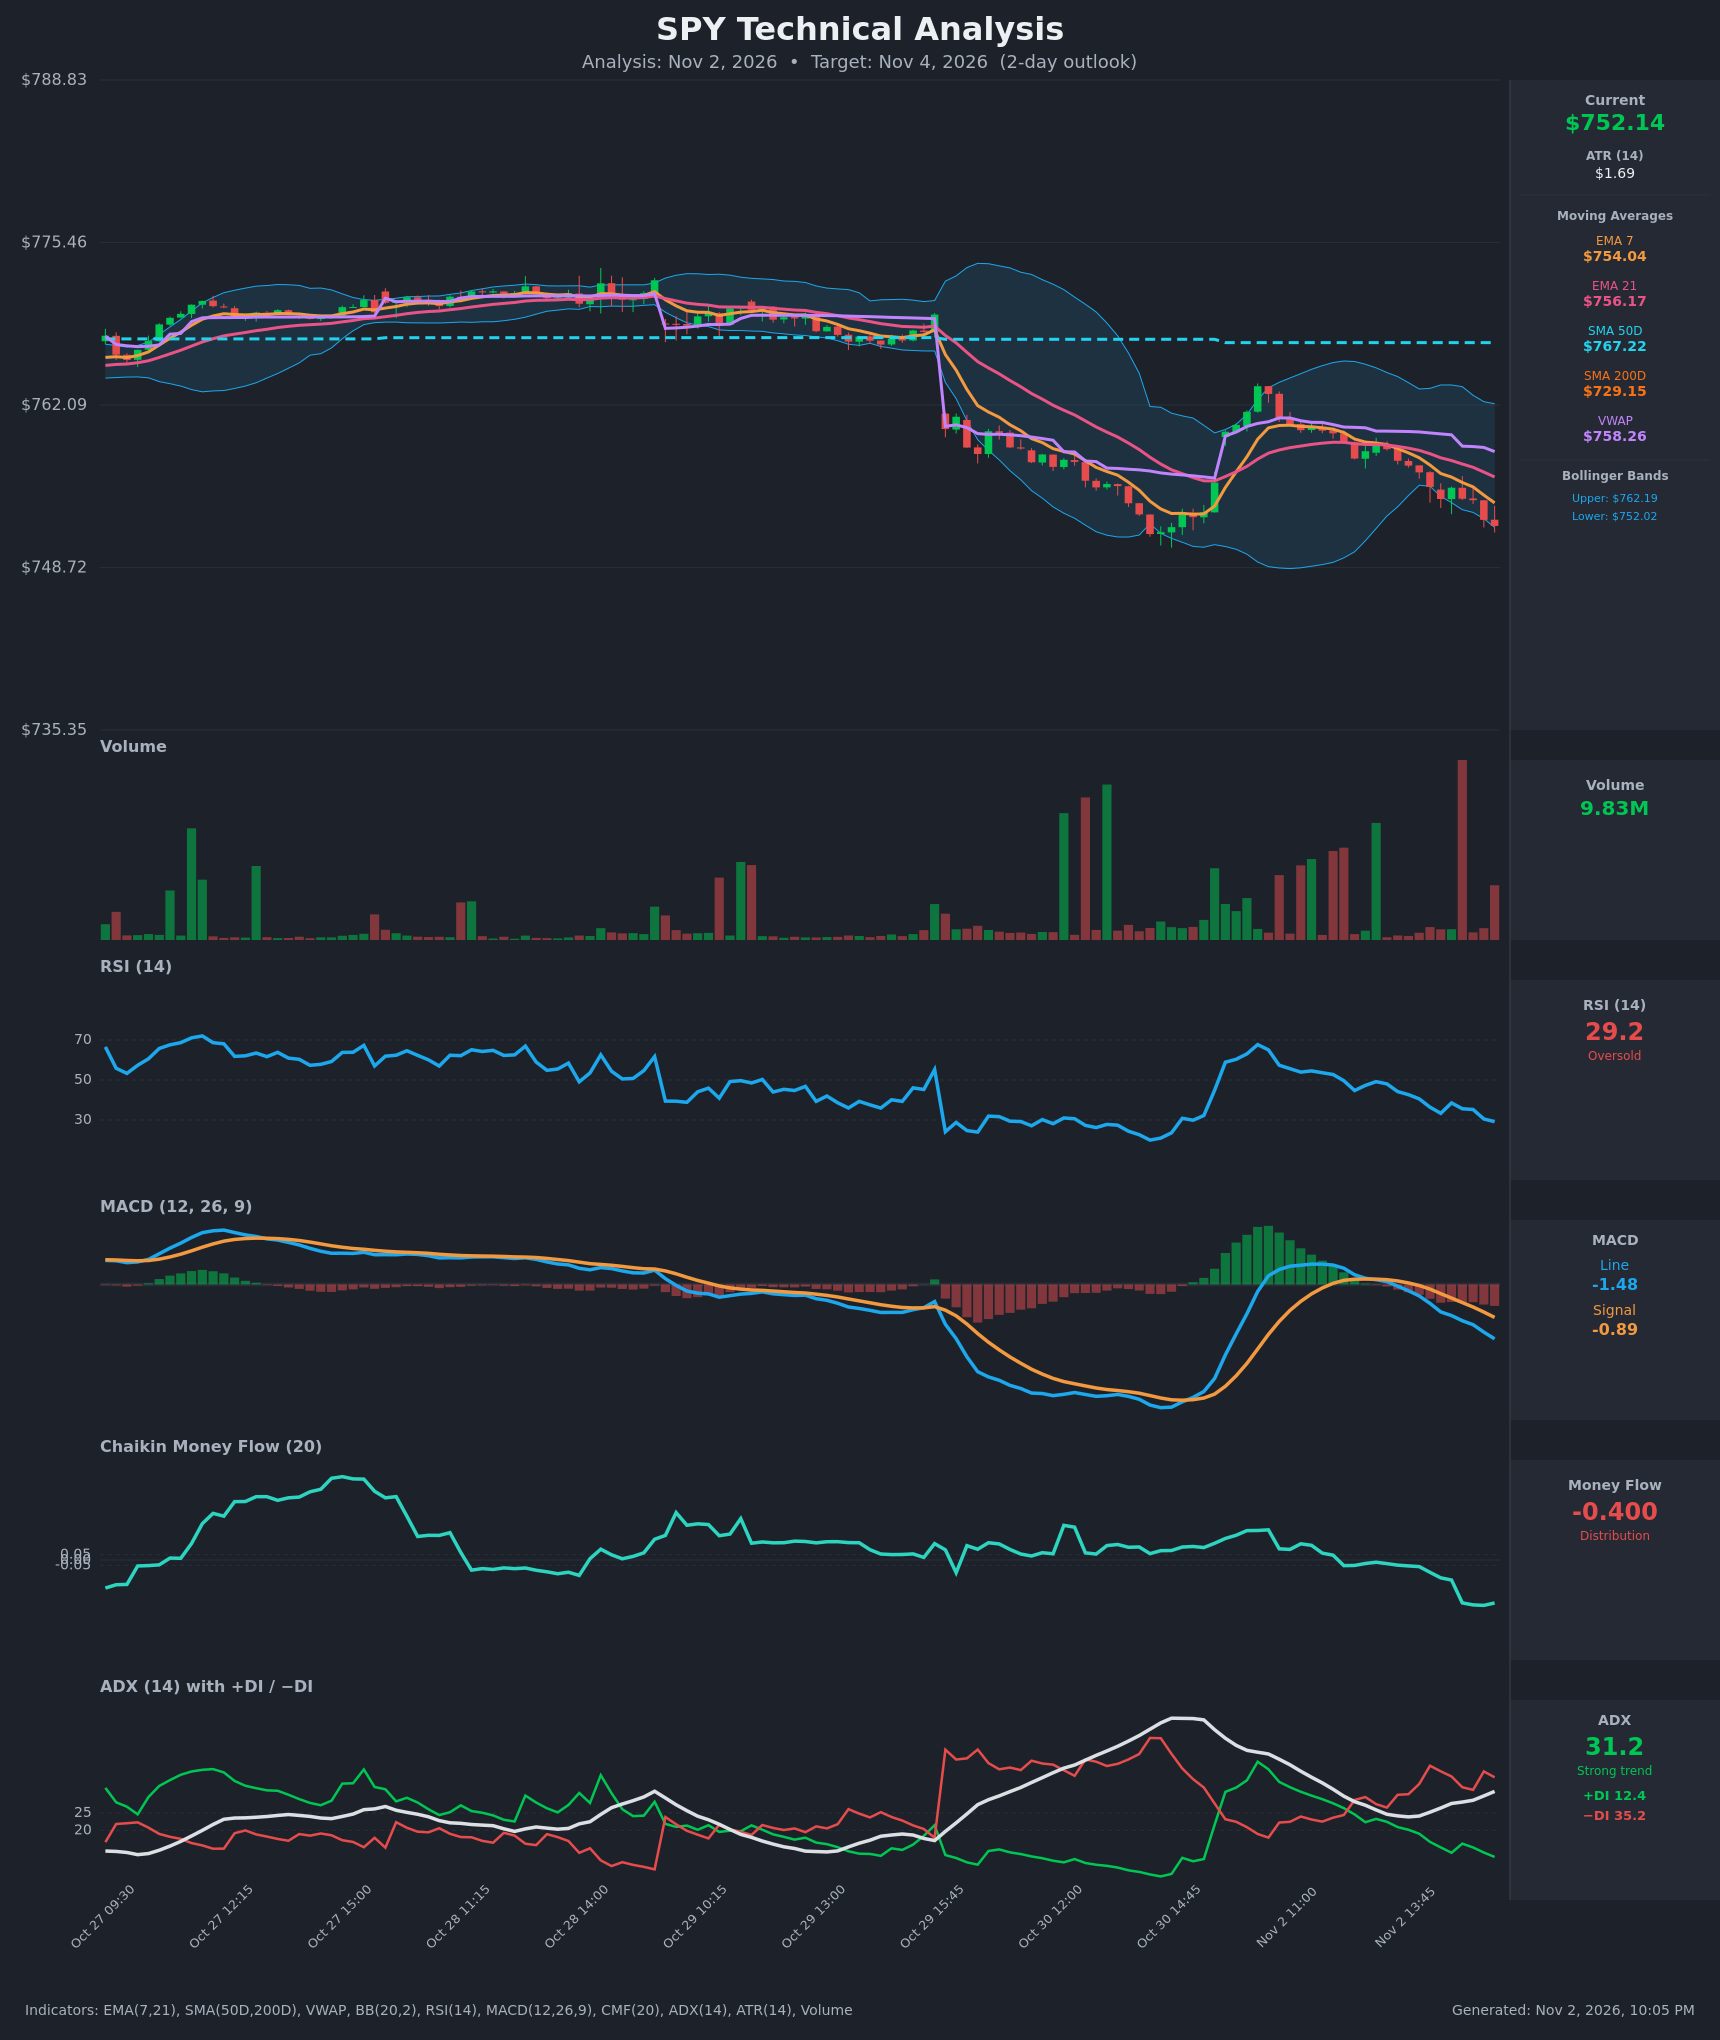
Model vs. Market: The options market implies $743.68–$760.52; the next-session technical model targets $750.80 within a $747.90–$754.60 band. The chart model expects a much narrower, slightly lower session than options are priced for. That gap is exactly why selling premium outside the model's band looks attractive.
The technical read shaped the strikes below. The bear call spread's short strike sits above both the model's $754.04 resistance and max pain. The condor's short strikes sit outside the model's whole projected range.
Full technical write-up: Next-session technical report →
4 · Three ways the next session can go
If SPY pushes back above max pain ($756) toward $758.23: The $750 call open interest would sit well in the money, and the whole-chain call wall at $760 would come into view overhead. With hedging estimated to amplify moves, a squeeze could travel quickly toward $760. A close above $758.23 would break the lower-high structure and invalidate the bearish tilt.
If SPY drifts between $746.81 and $756: This is the pin case. The dense $750 strike — next-session call wall, whole-chain put wall and largest gamma strike — sits in the middle. Expiring open interest tends to pull price toward that kind of cluster into settlement. Max pain at $756 gives a mild upward pull. This is the scenario where the credit structures below do best.
If SPY breaks below $746.81 toward the $740 put wall: This is the acceleration case. Negative dealer gamma means hedging could add to selling rather than cushion it. The heavy put pile at $745 is the next speed bump before $740. Below the $743.68 expected-move floor, SPY would be moving more than the market priced, even after a week of protection buying.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-11-02. All structures are hypothetical. Verify live prices before trading — these will be stale by the open. Because premium is priced unusually rich versus delivered movement, credit structures lead this section.
If you lean bearish: November 3 $757/$760 bear call credit spread
- Trade: Sell the November 3 $757 call ($1.59) and buy the November 3 $760 call ($0.725). You collect a credit and are betting SPY stays below $757 through settlement.
- Credit: $0.865 ($86.50 per spread) · Max profit: $86.50 · Max loss: $213.50 · Break-even: $757.87
- Why it fits: The short strike sits above max pain ($756) and the chart model's $754.04 resistance, inside a regime of rich premium (94th-percentile premium over delivered movement). The long leg sits at the whole-chain call wall.
- Makes sense only if: SPY holds below $756 early in the session.
- Invalidated if: SPY closes above $758.23.
- Managing it: Close at about 50% of max credit. If SPY trades through $757 with momentum, close rather than hope. This is a one-session trade, and the short-term trend is bearish while the longer reads are flat, so take profits early.
- Liquidity note: The $757 calls traded about 2¢ wide ($1.58/$1.60) and the $760 calls about 1¢ wide ($0.72/$0.73). Fills should be easy.
- Analyze this position →
If you expect the range to hold: November 3 $741/$744/$760/$763 iron condor
- Trade: Sell the $744 put ($0.71) and buy the $741 put ($0.39). Sell the $760 call ($0.725) and buy the $763 call ($0.28). All legs expire November 3. You collect a credit and are betting SPY settles between the short strikes.
- Credit: $0.765 ($76.50) · Max profit: $76.50 · Max loss: $223.50 · Break-evens: $743.24 and $760.77
- Why it fits: The break-evens sit almost exactly on the expected-move rails of $743.68 and $760.52. The short strikes sit well outside the chart model's $747.90–$754.60 band, and the $750 cluster in the middle supports a pin.
- Makes sense only if: SPY opens inside roughly $746.81–$756 without a gap.
- Invalidated if: SPY closes above $758.23 or below $746.81.
- Managing it: Close at 40–50% of the credit. If either short strike is touched, close that side; negative-gamma hedging can extend moves.
- Liquidity note: The short legs traded 1–2¢ wide. The cheap wings ($741 puts at $0.38/$0.40, $763 calls at $0.27/$0.29) are only 2¢ wide in dollars, but that is 5–7% of their price. Work the order at mid.
- Analyze this position →
If you lean bullish: November 3 $745/$748 bull put credit spread
- Trade: Sell the November 3 $748 put ($1.485) and buy the November 3 $745 put ($0.86). You collect a credit and are betting SPY stays above $748.
- Credit: $0.625 ($62.50) · Max profit: $62.50 · Max loss: $237.50 · Break-even: $747.38
- Why it fits: This structure bets on the oversold relief bounce the chart model gives a 35% chance. The short strike sits below the $750 pivot and just above the model's $747.90 range low, and you are selling puts while put skew is unusually stretched.
- Makes sense only if: $750 holds on the first test and the new call-side positioning shows up as buying.
- Invalidated if: SPY closes below $746.81.
- Managing it: This trade fights the near-term flow. Keep it small, close at 50% of the credit, and exit on any break of $748.
- Liquidity note: The $748 puts traded 3¢ wide ($1.47/$1.50) and the $745 puts 2¢ wide ($0.85/$0.87). Fills should be easy.
- Analyze this position →
If none of these: no trade
Premium is rich, so standing aside needs a real reason. Here is one. All three structures risk $2–$2.40 to make $0.60–$0.90 in a single session, inside a negative-gamma regime where hedging can turn a modest drop into a fast one. Elevated put demand also means some of that richness is the market pricing genuine downside risk, not free money. If you can't watch the position through the session, or if SPY gaps outside $746.81–$756 at the open, standing aside is a sound choice.
6 · Quick FAQ
What is SPY's expected move for the next session? About ±$8.42 (±1.12%) into the November 3 expiration, a range of $743.68 to $760.52, based on straddle pricing as of the November 2 close.
Is SPY expected to go up or down tomorrow? Options positioning as of November 2 leans neutral with a bearish tilt, driven by heavy put buying and unusually steep skew. That is a read of what traders have done, not a forecast. The actionable map is the $743.68–$760.52 range, the $740 put wall and the $750 call wall.
Are SPY options expensive right now? IV rank is 38/100, so implied volatility sits in the lower half of its past-year range, even though it is higher than about 84% of the year's daily readings. On top of that, options are priced about 5.6 vol points above the movement SPY has actually delivered. That is richer than 94% of this stock's own recent readings, which favors selling premium over buying it.
Where is SPY's biggest options support and resistance for November 3? The put wall is at $740 and the call wall is at $750. Max pain is $756, and $758.23 is the nearest structural resistance.
What invalidates this read? A close above $758.23.
Methodology & disclosures. Data: end-of-day options-chain snapshot for SPY, 2026-11-02, generated 2026-11-02T22:05:37.905Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.