SPY Options Price a $4.20 Move Into October 8: Pinned Between $770 and $781 While the Chart Leans Higher
SPY options imply a $773.02–$781.42 range for the October 8 expiration, with a $781 call wall overhead, a $770 put wall below and max pain at $775. Here is what is driving the neutral read, plus three defined-risk ways to trade the next session.
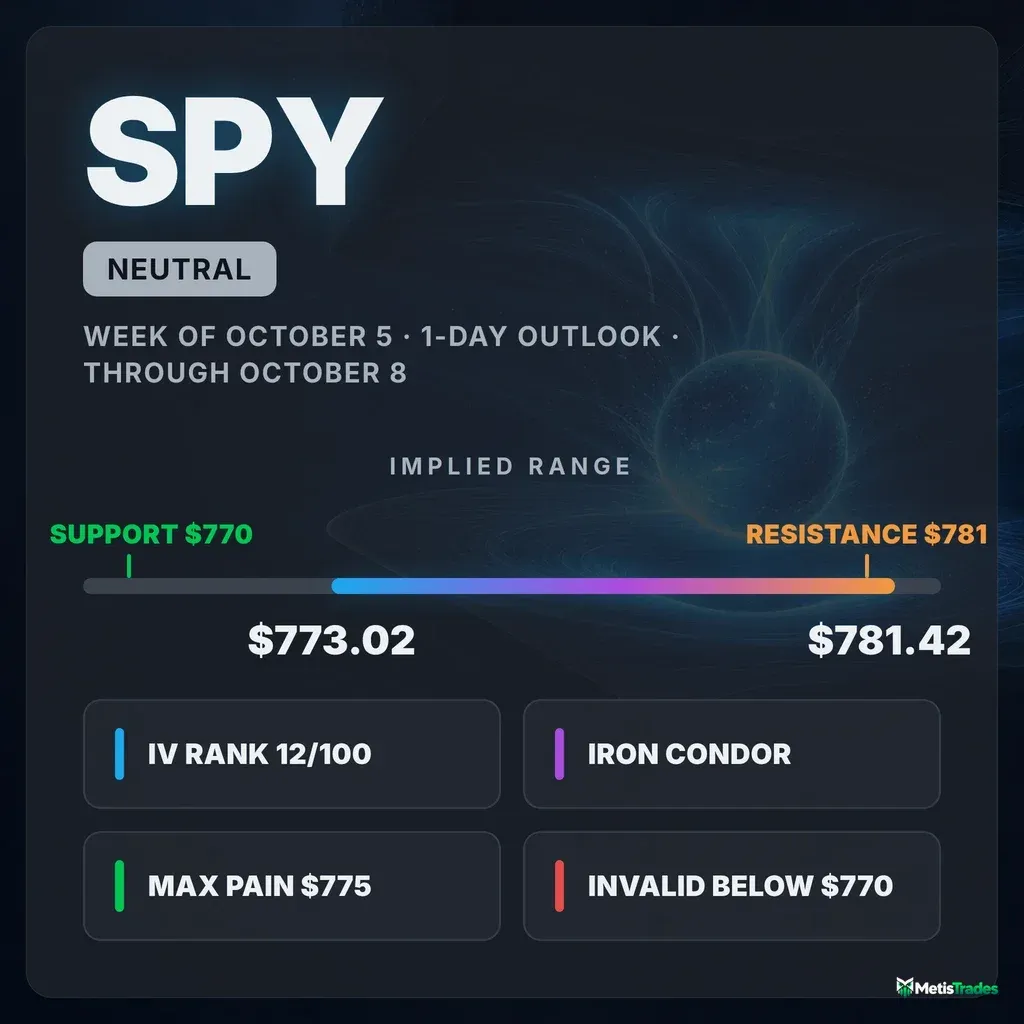
The options market implies a $773.02–$781.42 range into the October 8 expiration. Below is what is driving that range, the levels that frame it, and three defined-risk ways to trade it.
Published Wednesday, October 7, 2026 · Data as of Wednesday, October 7, 2026 close
Explore the live SPY options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Spot (last close) | $777.22 |
| Options-implied range (into October 8, 2026) | $773.02 – $781.42 (±$4.20, ±0.54%) |
| Major support | $770.00 (put wall, October 8 expiration) |
| Major resistance | $781.00 (call wall, October 8 expiration) |
| Max pain (October 8, 2026) | $775.00 |
| Dealer gamma regime (estimate) | Positive: hedging tends to dampen moves. Flip level ≈ $725 |
| Volatility condition | Falling. IV rank 11.73/100, ATM IV 12.85% · premium fair: options priced ~2.5 vol pts above delivered movement |
| Technical check | Mixed (chart model bullish, 2-day horizon; target $779.50, model range $769.50–$785.10) |
| Best-fitting strategy | Iron condor around the $770–$781 walls, only for traders comfortable with one-day gamma risk |
| Analysis invalidated if | SPY closes below $770.00 |
1 · What matters today
Our read of SPY options positioning for tomorrow's session (2026-10-08) is neutral. The signals mostly cancel out. Short-dated flow leans mildly toward calls, but traders also added a heavy batch of put contracts today, and SPY closed at $777.22, closer to its overhead wall than its floor.
The options market is pricing a move of about $4.20 either way, which works out to a range of $773.02 to $781.42. That figure is the expected move: the move the market is pricing in, derived from what straddles cost.
The range is framed by two piles of open contracts:
- the $781 call wall overhead, which sits right under SPY's 52-week high of $781.62;
- the $770 put wall below.
The level that changes the picture is $770. A close below it breaks the floor that options positioning has built. The chart model leans bullish, but its $779.50 target still sits inside the options range.
2 · What the options market is pricing
What changed this week
Price. SPY gained 1.91% over the past five sessions, which leaves it 0.56% below its 52-week high.
Implied volatility. IV (implied volatility, the market's estimate of how much SPY will move, baked into option prices) actually fell during the rally. ATM IV is down 7.9% in relative terms over five sessions. IV rank slipped to 11.73, below its 7-day average of 14.60 and right on its 14-day average of 11.80.
Put/call open interest. Open interest means contracts currently held open. The put/call OI ratio drifted from about 1.10 five sessions ago to 0.80 today, so puts thinned out over the week. Today's 0.80, however, is above the 3-day average of 0.64.
Today's flow. Put open interest grew by roughly 220,000 contracts, while call open interest shrank by about 153,000. That one-day swing toward puts is unusually large for SPY versus its own recent history. Some of the call shrinkage is the October 7 expiration rolling off. Into that settled expiry, the $780 calls had added 10,609 contracts of open interest on more than 522,000 contracts of volume.
Trend. The short- and long-term trend reads agree rather than fight. The past week is clearly positive, and the past month and past two-and-a-half months are flat-to-positive (+1.5% and +5.2%).
Expected move
Into the October 8 expiration, straddle pricing implies ±$4.20 (±0.54%) around $777.22. The ladder below shows how that envelope widens with time:
| Expiration | Implied move | Range around $777.22 |
|---|---|---|
| October 8, 2026 | ±0.54% | $773.02 – $781.42 |
| October 9, 2026 | ±0.78% | $771.16 – $783.28 |
| October 16, 2026 | ±1.71% | $763.93 – $790.51 |
| November 6, 2026 | ±3.69% | $748.54 – $805.90 |
The first two rungs are tight and roughly scale with time. The October 9 contracts carry a slightly higher ATM IV (10.59%) than the next-session contracts (10.37%) and noticeably more than the October 12 expiry (8.55%). The data shows that kink but no stated reason for it.
Volatility
Where IV sits. SPY's interpolated ATM IV is 12.85%, and the October 8 contracts on their own price about 10.4%. IV rank is 11.73/100, meaning today's IV sits cheaper than about 88% of the past year's range. IV percentile is 16.67, so only about one day in six over the past year printed lower.
Direction.
- IV ticked up 0.9% today but is down 7.9% over five sessions and 1.4% over 30.
- It sits right on its 30-day average (12.85%) and below its 90-day average (13.76%).
- Two-month IV is 13.54%.
The front-month term-structure read (term structure means comparing option prices across different expiration dates) is unavailable today because of the expiry day.
Realized movement. SPY's past ten sessions have been calmer than its 20-day pace: 10-day realized vol is 7.8% versus 10.3% over 20 days. That slowdown is unusually pronounced compared with this stock's own recent history. "Unusual" here means unusual for SPY, not versus the broader market.
Is premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much SPY has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them.
- Right now options are priced about 2.5 vol points above SPY's 20-day realized movement of 10.3%.
- That gap sits at the 61st percentile, richer than about 61% of this stock's own recent readings. That is squarely middle-of-the-road.
- Over the past week the gap eased from about 3.3 points (October 1) to 2.3 points (October 6) before ticking back to 2.5.
So what? IV rank at 11.73 and a mid-pack premium over delivered movement make premium fair, not rich. Sellers get paid modestly, not generously, which argues for small, defined-risk credit structures rather than aggressive premium selling.
Skew and sentiment
Skew. Puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. SPY's 25-delta puts trade at 14.2% IV versus 10.5% for the matching calls, so puts run about 3.7 vol points over calls. That is essentially SPY's 60-day norm of 3.8 points. The trailing averages show skew steepened over the past week, from a 7-day average of about 3.0 points, so put demand has been rebuilding from a complacent stretch back to normal.
Put/call volume. The put/call ratio measures put activity relative to calls, and above 1 means puts dominate. Today's volume ratio was 0.999, almost exactly balanced. It is slightly above its 7-day average of 0.96, with total volume right at its 20-day norm. The most aggressive trades leaned the other way: 36 call contracts versus 25 puts cleared the unusual-volume bar. That call-side sweep count is well above SPY's normal pace.
Sentiment by expiration. Options in the 0–7 day window read mildly bullish (+20), as do the 7–30 day options (+12). The 30–60 day bucket leans bearish (−42) on put building. The overall picture is "Mixed": short-dated traders lean modestly upward while traders a month or two out are adding protection.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Whole-chain call wall / largest gamma strike | $785 | Heaviest call open interest across all expirations (214,662 contracts); the October 9 expiry alone holds 123,040 there |
| 52-week high | $781.62 | Price-structure ceiling; SPY sits 0.56% below it |
| Upper edge of implied range | $781.42 | Top of the ±$4.20 envelope for October 8 |
| Call wall (October 8) | $781 | Largest call pile for the next-session expiry (3,404 contracts), which often acts as a lid |
| Second-largest gamma strike | $780 | Big combined call/put interest; a likely sticking point on rallies |
| Chart-model resistance | $778.43 | TA report's key resistance (upper Bollinger band) |
| Spot (close) | $777.22 | Reference price |
| Swing support | $776.14 | Nearest heuristic support from recent price pivots |
| Chart-model support | $775.17 | TA report's key support and its bullish-scenario invalidation |
| Max pain (October 8) | $775 | Price where the most next-session option value expires worthless; also the third-largest gamma strike |
| Lower edge of implied range | $773.02 | Bottom of the ±$4.20 envelope |
| Put wall (October 8 and whole chain) | $770 | Largest put pile for October 8 (4,028) and across the chain (96,644); the thesis floor |
| Gamma strike / October 9 put wall | $767 | 70,530 open puts in the October 9 expiry |
| 20-day / 50-day moving averages | $766.46 / $765.95 | Trend support cluster about 1.4% below |
| Swing support | $757.50 | Next heuristic pivot |
| 100-day moving average | $755.40 | Intermediate trend support |
| Gamma flip (estimate) | $725 | One rough estimate of where hedging flips from cushioning to amplifying; far below |
| 200-day moving average | $721.99 | Long-term trend; SPY is 7.65% above it |
The next-session walls ($770 / $781) and the whole-chain walls ($770 / $785) agree on the floor but disagree on the ceiling. For tomorrow, the $781 call wall is the one that applies.
Positioning and unusual flow
Dealer gamma. Market makers hedge the options they've sold. One rough estimate puts SPY in a positive gamma regime, where their hedging tends to dampen moves. The October 8 expiration's own estimate is also positive, so the cushioning framing applies to tomorrow. The estimated flip level near $725 is far below spot.
Today's notable flow in next-session contracts:
- $778 calls (October 8): 96,588 traded against just 1,055 open, about $13.2 million in premium.
- $777 calls (October 8): 83,409 traded against 856 open, about $15.7 million in premium.
- $777 puts (October 8): 75,223 traded, with open interest rising by about 1,000 to 1,238, roughly $11.0 million in premium.
Heavy two-way trading right at the money is classic pin behavior: traders are positioning for a close near current levels rather than a breakout.
Further out, protection is being layered in:
- The October 15 $772 puts added 7,223 contracts of open interest.
- The October 9 $767 puts added 5,974, to 70,530.
3 · Technical check
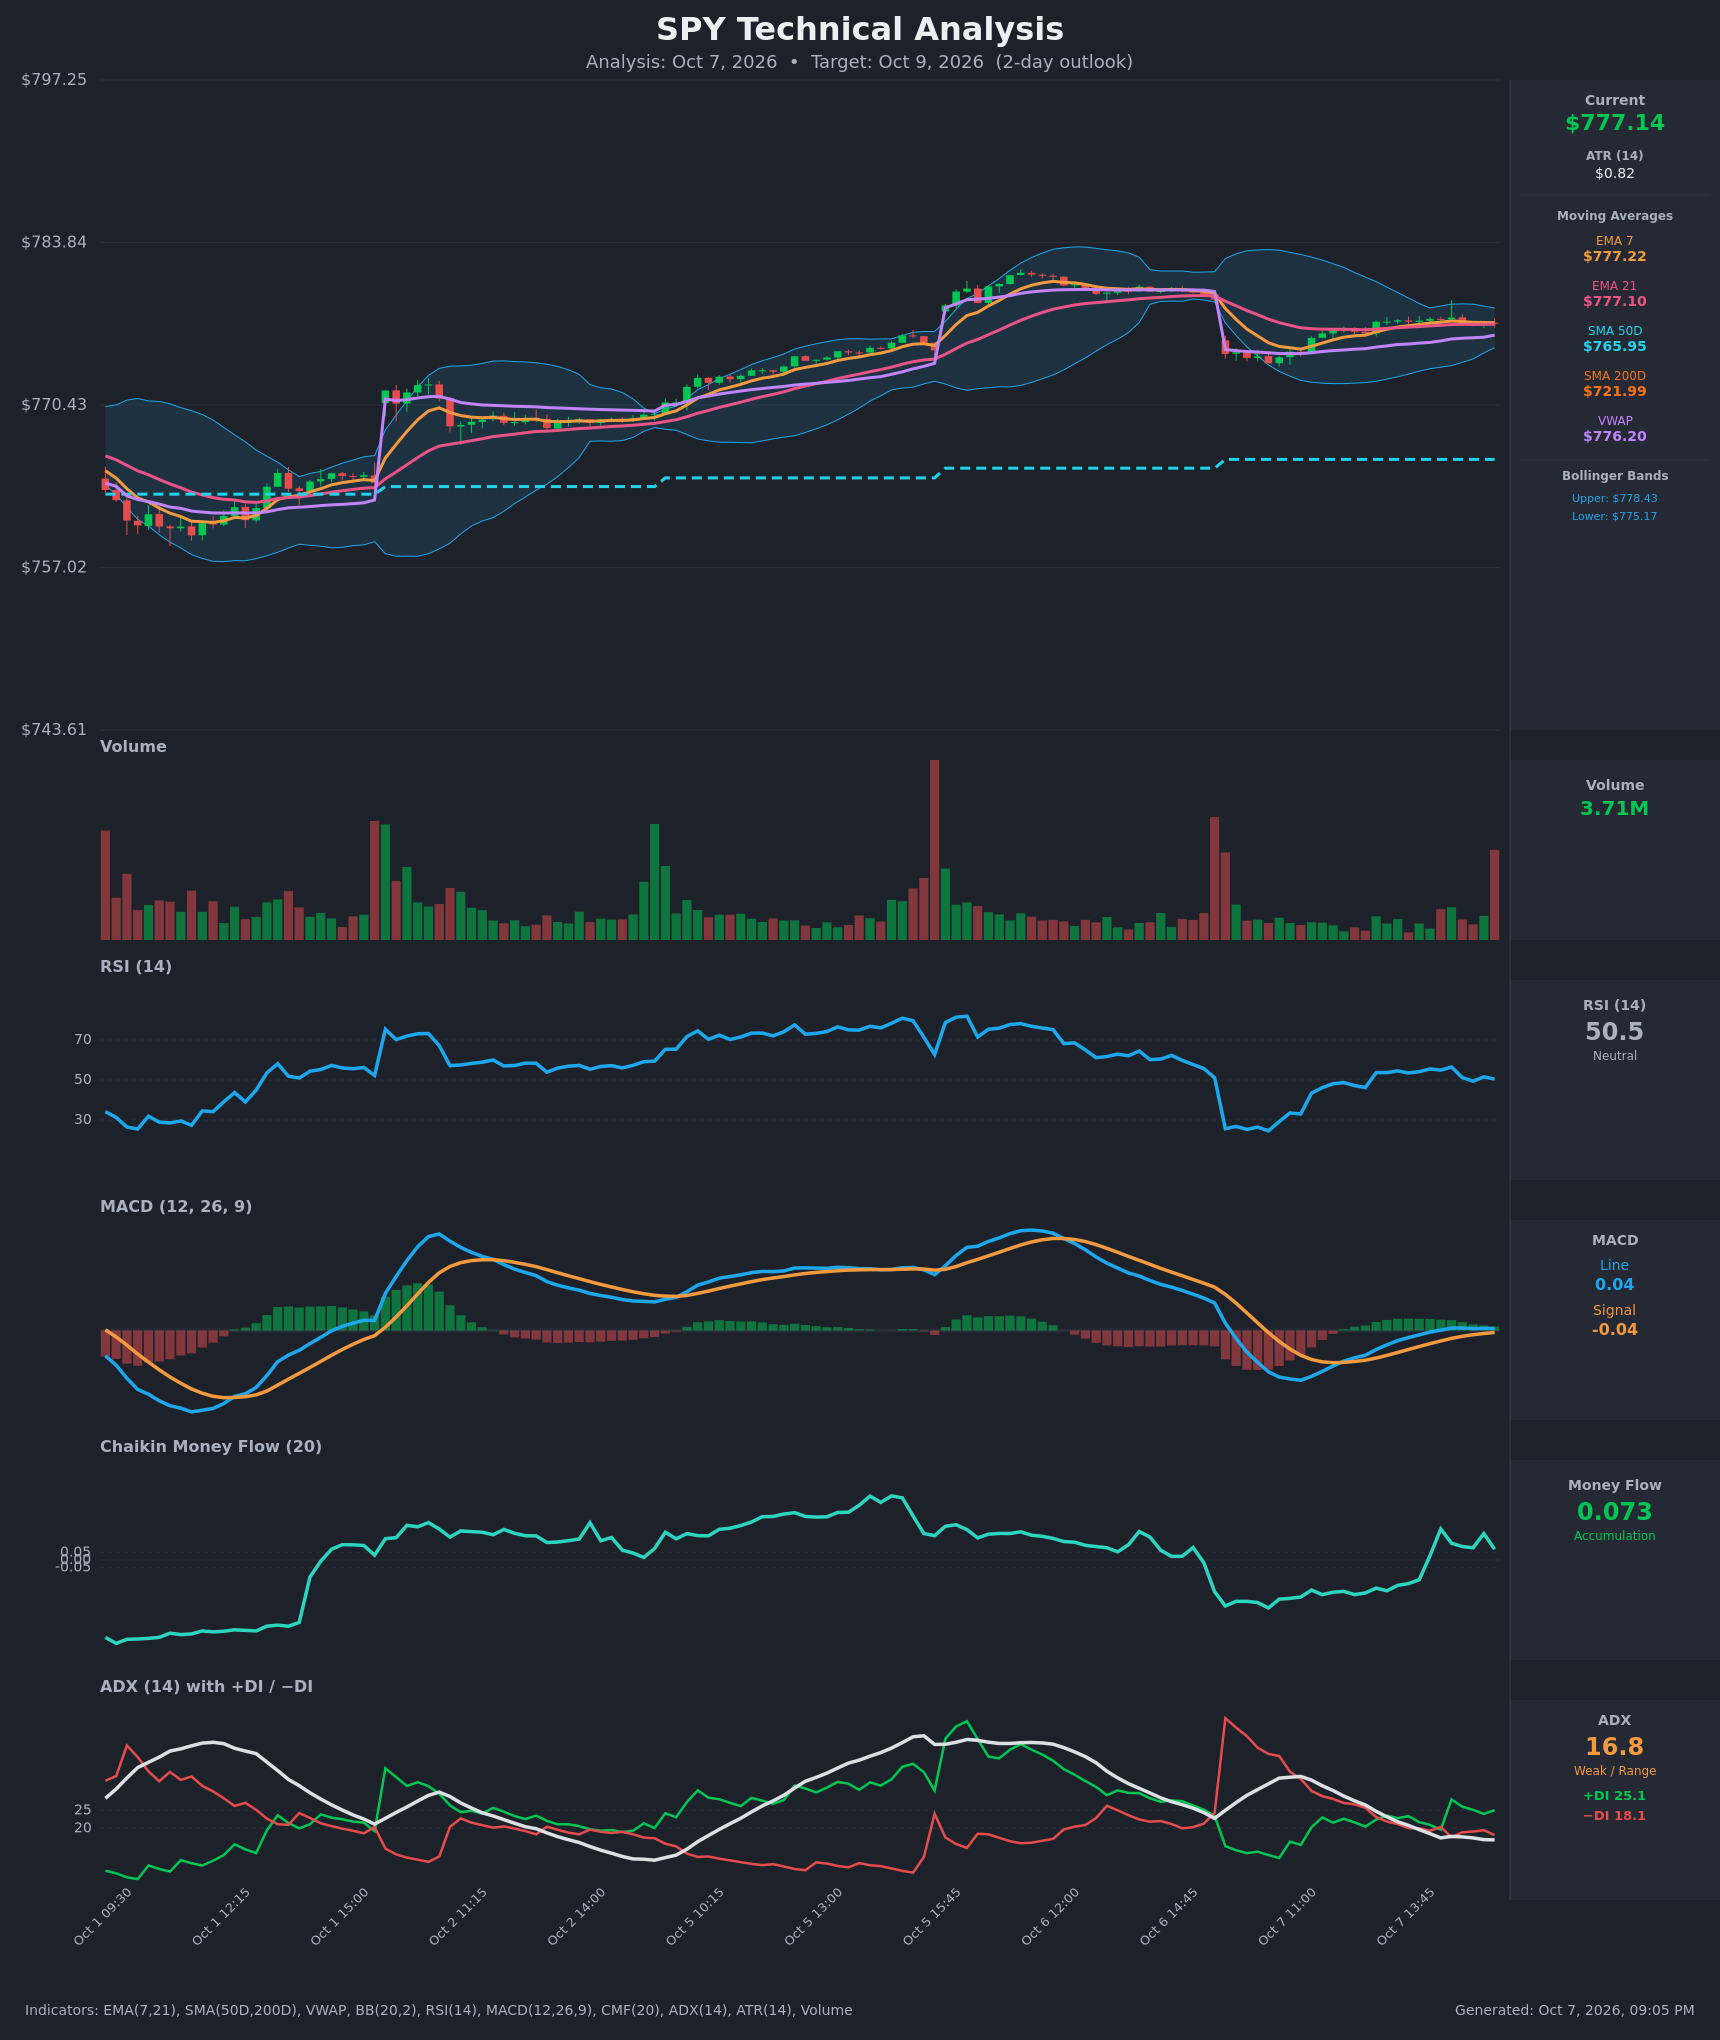
The chart model's call. The next-session technical report (2-day horizon, target date October 8) is bullish. It targets $779.50 with a projected range of $769.50 to $785.10, and its reference price ($777.14) matches the options data. It reads the recent compression as a small bullish pennant aimed at the $780–$782 area.
Indicator support is soft. ADX sits at 16.8 and falling, a weak, range-bound trend. Money flow (CMF +0.073) shows only mild accumulation. The model frames its own conviction as modest.
Classification: Mixed. The direction differs from our neutral options read, but the $779.50 target sits inside the $773.02–$781.42 implied range. The model's $769.50–$785.10 range is wider than what options are pricing. Its dominant scenario is invalidated on a close below $775.17, which sits a hair above max pain.
Model vs. Market: The options market implies $773.02–$781.42 for October 8; the 2-day technical model targets $779.50. That's a lean toward the upper half of the same box, not a breakout, and the $781 call wall stands between the target and anything bigger.
The TA shaded strike selection only slightly: the bullish structure below aims its short strike at the $781 wall rather than beyond it.
Full technical write-up: Next-session report →
4 · Three ways the next session can go
If SPY pushes above the call wall ($781): The heaviest next-session call interest and the $781.62 52-week high sit together. Positioning like that tends to slow rallies as hedgers sell into strength. A clean close through it leaves the whole-chain $785 call wall as the next magnet. That pile is concentrated in the October 9 expiry, so a break would quickly shift attention there.
If SPY drifts between the walls: This is the base case positioning describes. Positive dealer gamma tends to cushion moves, and heavy at-the-money trading at $777–$778 suggests a session that oscillates inside $773–$781. Expiring open interest pulls toward $775 max pain. SPY closed $2.22 above that level, and the chart model's $775.17 support lines up with it.
If SPY breaks below the put wall ($770): Losing the largest put pile for both the next-session expiry and the whole chain would invalidate the range read. Below it, the next interest clusters at the $767 October 9 puts and the $766–$766.50 moving-average zone. The gamma flip estimate (~$725) is far enough away that dealer hedging would still be expected to cushion, not accelerate, a one-day drop.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 7, 2026. All structures are hypothetical unless flagged as an entered position. Verify live prices before trading; these will be stale by the open. All three expire October 8, 2026, which is a single session. Gamma risk is extreme and positions can swing from max profit to max loss within hours.
If you expect the range to hold: October 8 iron condor
- Trade: Sell the October 8 $773/$770 put credit spread and the $781/$784 call credit spread. A credit spread collects premium up front and profits if the stock stays away from the short strike.
- Credit: $0.57 ($0.24 puts + $0.33 calls) · Max profit: $57 · Max loss: $243 · Break-evens: $772.43 and $781.57
- Why it fits: The short strikes sit at the edges of the ±$4.20 implied move, with the $781 call wall as the upper anchor and $770 put wall support beneath the put side. The neutral bias and a positive gamma regime both favor a contained session.
- Makes sense only if: you accept a roughly 1:4 reward-to-risk in exchange for a wide profit zone, and you can monitor the position during the session.
- Invalidated if: SPY closes below $770 or above $781 (either short spread fully tested).
- Managing it: Close at about 50% of the credit, a $0.28–$0.29 buyback. If SPY trades through $773 or $781 intraday, close rather than hope; one-day options don't give you time to recover.
- Liquidity note: All four legs were a penny wide today ($773 puts 0.41/0.42, $770 puts 0.17/0.18, $781 calls 0.40/0.41, $784 calls 0.07/0.08). The $784 call's penny spread is about 13% of its tiny price, and a few cents of slippage on four legs eats a meaningful slice of a $0.57 credit, so use limit orders.
- Analyze this position →
If you lean bullish: October 8 $777/$781 bull call spread
- Trade: Buy the October 8 $777 call, sell the $781 call. A debit spread costs you a fixed amount up front and pays if the stock rises toward the short strike.
- Debit: $1.48 · Max profit: $252 · Max loss: $148 · Break-even: $778.48
- Why it fits: It aims directly at the chart model's $779.50 target and caps the payoff at the $781 call wall, where positioning tends to stall rallies. Call sweeps ran unusually heavy today, and the past week's trend is up.
- Makes sense only if: SPY holds above $775.17 early in the session.
- Invalidated if: SPY closes below $775.17.
- Managing it: Take profits near $780; there's little left to gain from $780 to $781 against pin risk at the wall. Cut the trade if SPY loses $775 intraday.
- Liquidity note: The $777 calls traded 1.88/1.89 and the $781 calls 0.40/0.41, both penny-wide, so fills are easy.
- Analyze this position →
If you lean bearish: October 8 $777/$773 bear put spread
- Trade: Buy the October 8 $777 put, sell the $773 put (debit spread).
- Debit: $1.05 · Max profit: $295 · Max loss: $105 · Break-even: $775.95
- Why it fits: It targets a drift toward $775 max pain and the $773.02 lower edge of the implied range. It also reflects today's unusually large put-side open-interest build.
- Makes sense only if: SPY fails to reclaim $778.43 and slips under $776.14 swing support.
- Invalidated if: SPY closes above $781.
- Managing it: Take profits near $774. Exit if SPY trades above $779 with call flow persisting.
- Liquidity note: The $777 puts traded 1.46/1.47 and the $773 puts 0.41/0.42, both penny-wide.
- Analyze this position →
If none of these: no trade
Standing aside is a reasonable choice tomorrow.
- Credit is thin. IV rank of 11.73 means option sellers are collecting little, and a premium only about 2.5 vol points over delivered movement is middling, not rich.
- The directional edge is weak. The positioning signals net out to roughly zero.
- One-day structures punish slippage. The condor risks $243 to make $57, and the debit spreads need SPY to move promptly.
If you can't watch the screen during the session, a one-day option position is the wrong tool.
6 · Quick FAQ
What is SPY's expected move for October 8? About ±$4.20 (±0.54%), a $773.02–$781.42 range, per the options market's straddle pricing as of the October 7 close.
Is SPY expected to go up or down tomorrow? Options positioning as of October 7 leans neutral: mild call-side flow is offset by a heavy put open-interest build. That's a read of what traders have done, not a forecast. The actionable map is the $773.02–$781.42 range and the $770/$781 levels.
Are SPY options expensive right now? No. IV rank of 11.73/100 means option prices sit near the low end of the past year's range. They're running about 2.5 vol points above the movement SPY has actually delivered, richer than about 61% of its own recent readings, which is fair rather than rich.
Where is SPY's biggest options support and resistance? For the October 8 expiration, the put wall is at $770 and the call wall at $781. Across the whole chain, the heaviest call strike is $785.
What invalidates this read? A close below $770.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for SPY, 2026-10-07, generated 2026-10-07T21:05:20.216Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.