SPY Options Are Pricing a $6 Move — Our Positioning Read Sees a Neutral Stalemate Under $770
SPY options imply a $763.60–$775.60 range into the October 15 expiration, with the close parked just under the $770 put wall after a put-heavy session. Here is what is driving the setup and three defined-risk ways to trade it.
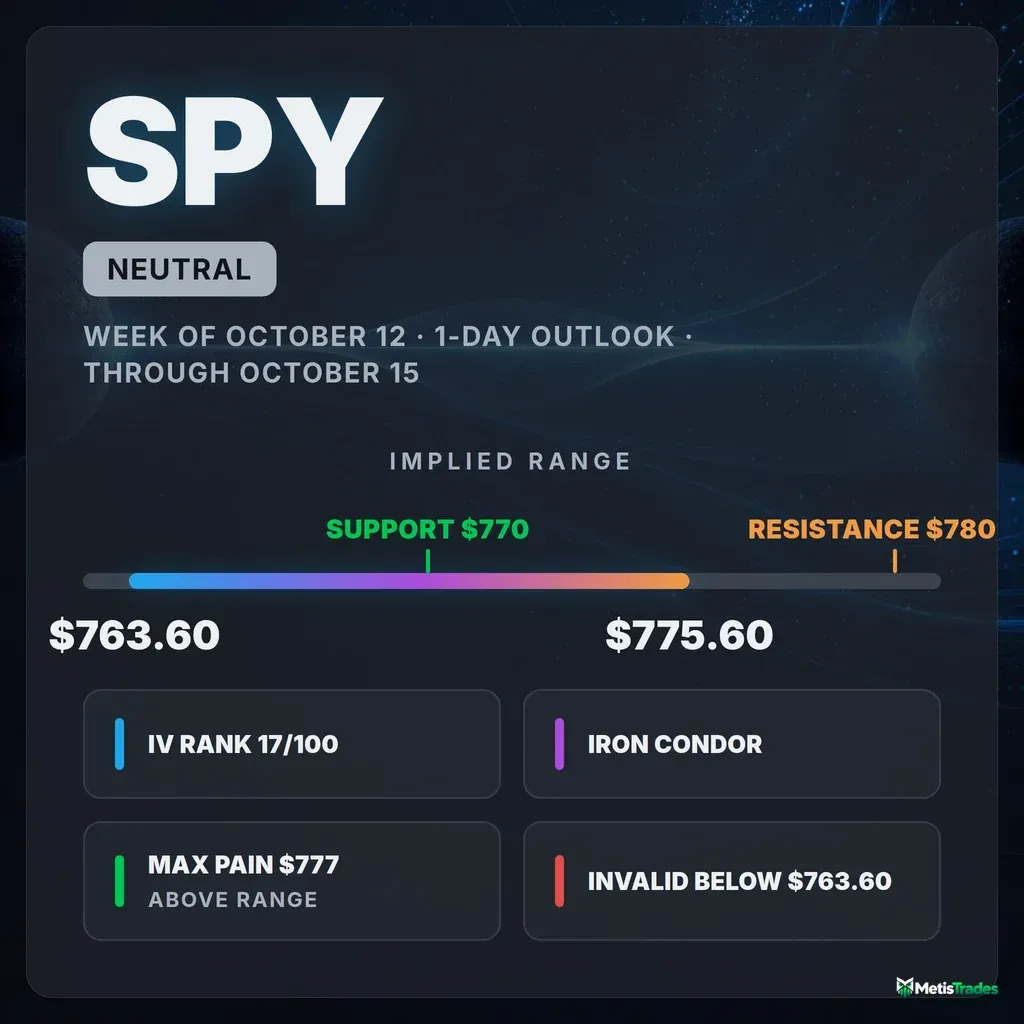
The options market implies a $763.60–$775.60 range into the October 15 expiration. Here's what is driving it and three defined-risk ways to trade it.
Published Wednesday, October 14, 2026 · Data as of Wednesday, October 14, 2026 close · Nightly update covering the next session (October 15)
Explore the live SPY options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into October 15) | $763.60 – $775.60 (±$6.00, ±0.78%) |
| Major support | $770 (October 15 put wall; SPY closed just beneath it). Next: $765, the heaviest put strike across the whole chain |
| Major resistance | $780 (October 15 call wall) |
| Max pain (October 15) | $777 |
| Dealer gamma regime (estimate) | Negative: hedging tends to amplify moves. Flip level n/a (no flip estimate in today's data) |
| Volatility condition | Rising. IV rank 16.5/100 · premium rich: options priced ~3.3 vol pts above delivered movement |
| Technical check | Mixed (bullish, 2-day horizon; target $771.80, model range $761.50–$778.50) |
| Best-fitting strategy | Iron condor around the implied range (defined risk, small size) |
| Analysis invalidated if | SPY closes below $763.60 |
1 · What matters today
Our positioning read on SPY is Neutral for tomorrow's session (October 15). The options market is pricing a move of about $6 either way, a $763.60 to $775.60 range, based on what at-the-money straddles cost. The key fact is where SPY closed: $769.60, a hair under $770. That is the strike with the biggest pile of open put contracts for the October 15 expiration, a level that often acts like a magnet or a floor.
Flow turned put-heavy in the latest session. The levels stacked just below, though, keep the picture balanced rather than one-sided: the 50-day average at $768.57 and another heavy put strike at $765. The level that changes the picture is $763.60. A close below the bottom of the priced range would mean sellers broke out of what options were bracing for. The chart model leans mildly bullish, but its $771.80 target sits inside the options range.
2 · What the options market is pricing
What changed this week
The past few sessions flipped the tone.
- Price: SPY slid from $778.01 to $769.60 in the latest session, about a 1.1% drop, leaving it down 0.98% over five trading days.
- Volatility: At-the-money implied volatility jumped 8.1% in a day and 5.8% over five days.
- Put/call open interest: This ratio compares contracts held open on each side. It climbed to 1.29 from 0.81 a day earlier, so for every call held open there are now about 1.3 puts. Its 7-day average is 0.83, so traders added downside protection at a rapid clip.
- Net position changes: Since the prior snapshot, call open interest fell by roughly 318,000 contracts while put open interest rose by about 251,000.
- Biggest single open-interest build: The October 16 $773 puts, up 20,790 contracts to 26,545. These puts are already in the money, which looks more like hedging of existing long exposure than a fresh short bet.
Our flow composite swung from a 7-day average of 0 to −30 today, so the shift is recent and sharp rather than a long-building trend. The short-, medium- and long-term trend reads all sit flat, with a fresh bearish momentum crossover printed on October 13. This is a new wobble inside a market that has gone nowhere much over two months, not an established downtrend.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the October 15 expiration it is ±$6.00, or ±0.78%, which puts the range at $763.60 to $775.60 around the $769.60 snapshot price.
| Expiration | Implied move | Range around $769.60 |
|---|---|---|
| October 15 (1 day) | ±0.78% | $763.60 – $775.60 |
| October 16 (2 days) | ±1.06% | $761.44 – $777.76 |
| October 23 (9 days) | ±1.91% | $754.90 – $784.30 |
| November 13 (30 days) | ±3.88% | $739.74 – $799.46 |
The two front rungs carry noticeably higher implied volatility (about 14.9% and 14.3%) than the October 19–22 expirations (roughly 10.8%–11.9%). Traders are paying up for protection over the next 48 hours specifically, consistent with the post-selloff hedging described above.
Volatility
Level and direction. Implied volatility (IV) is the market's estimate of how much SPY will move, baked into option prices. At-the-money IV is 13.60%. That sits above its 30-day average of 12.9% and just under its 90-day average of 13.7%, and it is up 12.8% over the past 30 sessions.
Against the past year. IV rank shows where today's IV sits versus the past year's range. At 16.5/100, today's level sits in the cheapest sixth of that range (cheaper than about 83.5% of it). On the related percentile measure, IV is higher than only about 35% of the past year's readings. So option prices are rising off a low base, not stretched.
Other context. The front-month term-structure read, which compares option prices across expiration dates, is unavailable today because the nearest expiration expired at the close. The VIX closed at 16.87, up from 15.27 the prior day, and SPY's IV has tracked it almost one-for-one over the past 60 sessions. Realized volatility over the past 20 days is about 10.3%, running a touch below SPY's own recent norm, and the pace of daily moves is about typical for this name.
Premium rich or cheap. The volatility risk premium is the gap between how much movement options are priced for and how much SPY has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them. Today options are priced about 3.3 vol points above what SPY has actually delivered.
- That gap's percentile is 76/100, richer than about 76% of this stock's own recent readings.
- The gap widened from about 2.3 points on October 9 with no sign flip along the way.
- The implied-versus-realized reading is modestly above its own norm as well.
So what: a 76th-percentile premium over delivered movement favors collecting premium in the next session. The low IV rank of 16.5 means that edge comes in small dollar amounts, which argues for tight sizing over swinging for big credits.
Skew and sentiment
Skew. Puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. SPY's 25-delta puts are priced at 15.4% IV against 11.6% for comparable calls, a gap of 3.8 vol points. The norm for this name over the past 60 days is 3.6 points, so skew is slightly steeper than usual: more demand for downside protection, but not a panic premium.
Put/call volume. This ratio measures put activity relative to calls, and above 1 means puts dominate. It came in at 1.05, against a 7-day average of 0.95. Total option volume ran 1.20× its 20-day average.
Sweeps. Put-side sweeps outnumbered call sweeps among contracts clearing the peer-relative unusual-volume bar, 23 to 18. That put tilt is unusually heavy for SPY relative to its own recent history. The day-over-day build in put open interest is also well beyond what's typical for this name.
Short-dated sentiment. The 0–7 day bucket scores −15 and the 7–30 day bucket −12. A week ago they averaged +17 and +15. Every bucket on the curve now leans the same way, a "broadly bearish" reading, but each only mildly.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Call wall (October 16) | $785 | Heaviest call stack for Friday's expiration; far outside tomorrow's range |
| 52-week high | $781.62 | The ceiling of the past year |
| Call wall (October 15 and whole chain) | $780 | Largest open call position, often a cap on rallies |
| Swing resistance | $777.05 | Recent pivot cluster from price action |
| Max pain (October 15) | $777 | Price where the most option value would expire worthless; sits above the implied range |
| Upper implied rail (October 15) | $775.60 | Top of the one-day priced move |
| Large-gamma strike | $775 | Heavy open interest on both sides; hedging activity clusters here |
| Max pain (October 16) | $773 | Friday's expiration pulls toward a lower level than Thursday's |
| Put wall (October 16) / large-gamma strike | $772 | 52,219 open puts for Friday; a sticky zone just overhead |
| 20-day moving average | $770.65 | Short-term trend line SPY just slipped under |
| Put wall (October 15) / largest-gamma strike | $770 | Biggest put pile for the next session, and the single heaviest gamma strike in the chain |
| Close | $769.60 | Where SPY finished the October 14 session |
| 50-day moving average | $768.57 | First trend support below the close |
| Put wall (whole chain) | $765 | 113,222 open puts across all expirations combined |
| Lower implied rail (October 15) | $763.60 | Bottom of the priced move and the invalidation level |
| Large-gamma strike | $760 | Large put concentration below the range |
| Swing support | $757.50 | Recent pivot low cluster |
| 100-day moving average | $757.23 | Intermediate trend support |
| Swing support | $746.81 | Deeper pivot cluster |
| 200-day moving average | $724.21 | Long-term uptrend line, far below |
A gamma flip level is the price below which market-maker hedging tends to accelerate selling rather than cushion it. Today's data carries no flip estimate, so that level is not on the map.
Positioning and unusual flow
Dealer gamma. Market makers hedge the options they've sold. One rough estimate suggests the regime is negative both for the October 15 expiration alone and for the chain as a whole. In that regime their hedging tends to amplify moves rather than dampen them. Pair that with spot sitting right at the $770 put wall: if the wall gives way, there is less of a cushion than the open interest alone would suggest.
Unusual flow, mostly short-dated calls.
- The October 15 $770 calls traded 87,794 contracts against only 987 held open beforehand, about $17.3 million of premium.
- The October 15 $772 calls traded 88,702 contracts against 1,501 open.
- The October 15 $768 calls traded 43,091 contracts against 163 open, about $13.2 million in premium.
Most of that is same-day turnover rather than positions carried overnight. Still, it shows traders actively buying and selling upside lottery tickets right at the strikes that define tomorrow's range.
Downside builds that stuck. The October 15 $765 puts traded 49,004 contracts, and open interest there went from zero to 1,682. The October 15 $766 puts added 3,779 contracts of open interest. Both strikes sit just above the lower edge of the implied range.
3 · Technical check
Classification: Mixed. The next-session technical model, a 2-day horizon report generated alongside this data, leans bullish. It targets $771.80 within a projected range of $761.50 to $778.50. Its direction doesn't match our neutral options read, but the target sits inside the options-implied range.
Its case. The model treats the latest dip as an oversold bounce: RSI recovered from deeply oversold readings and MACD posted a bullish crossover below zero. It flags the money-flow indicator as still deeply negative (−0.44), which "does not confirm the price bounce." Its key levels are support at $768.57 (the 50-day average) and resistance at $771.70 (the upper Bollinger band). The dominant bullish scenario is invalidated on a close below $767.00.
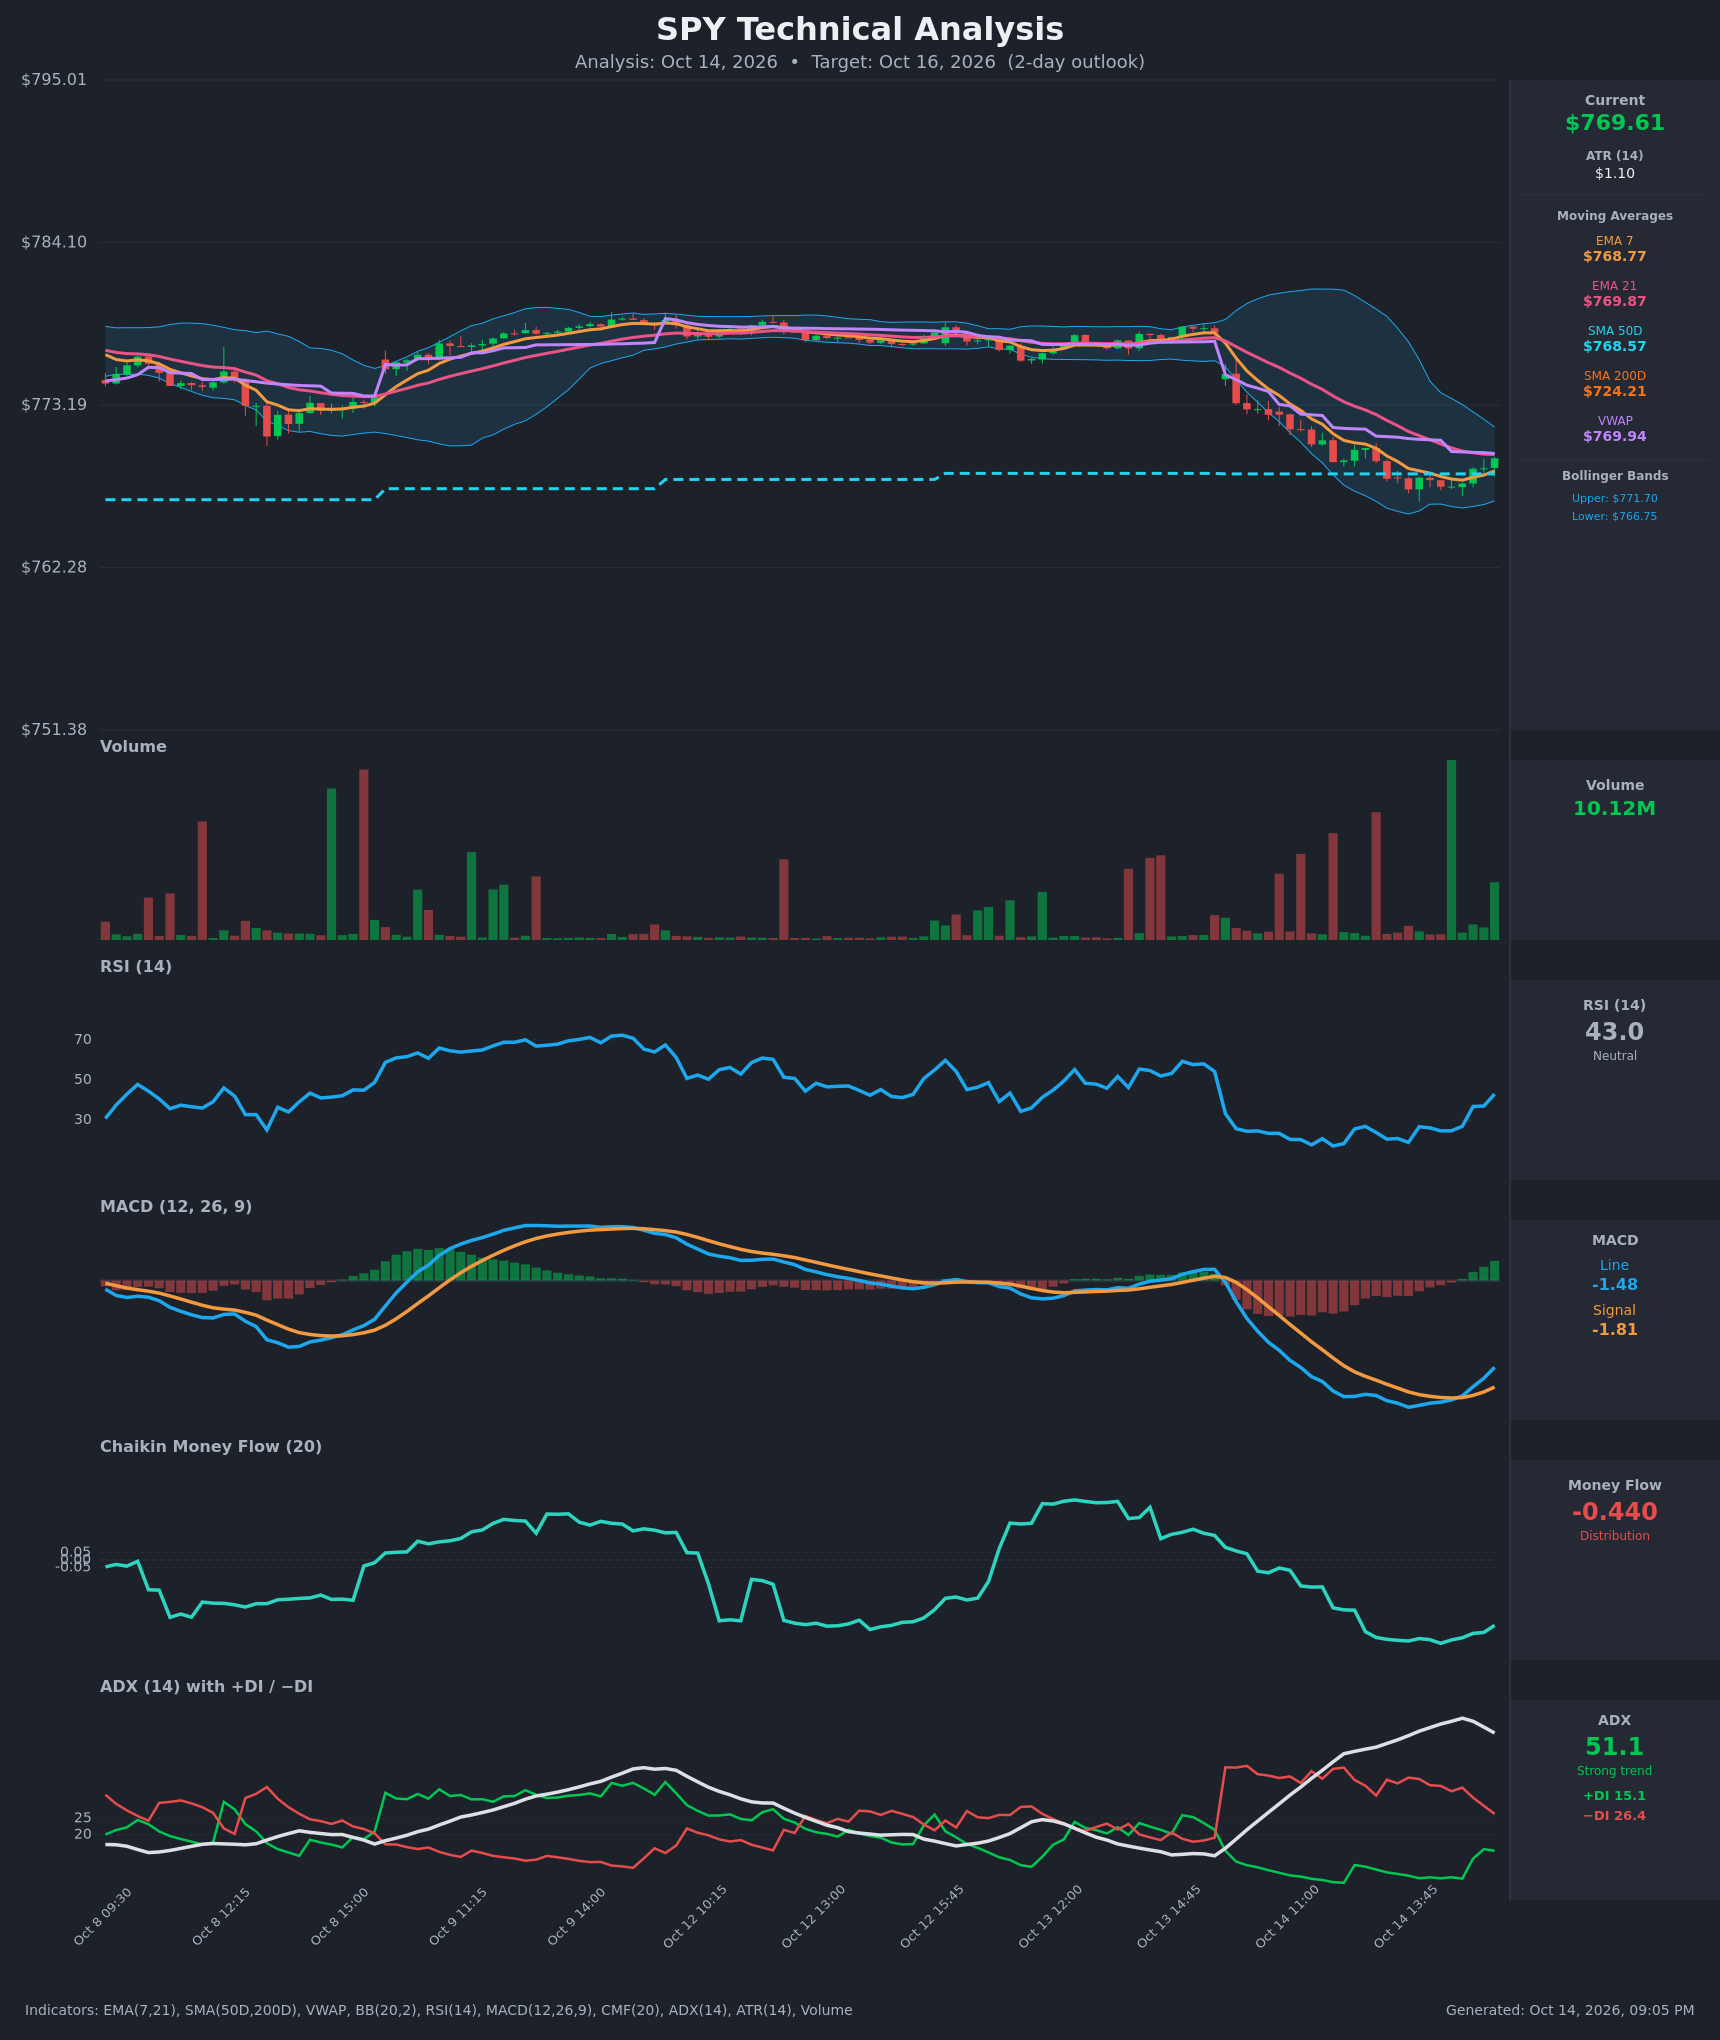
Model vs. Market: The options market implies $763.60–$775.60 for October 15; the next-session technical model targets $771.80. The chart model sees a modest bounce back above the $770 put wall. Options are pricing a symmetric move, and flow has been leaning the other way, so a close back above $770 would tip the tie toward the chart, while a close under the 50-day at $768.57 would undercut it.
Because the technical read is mixed rather than confirming, it did not shade our strikes. The condor below is built around the options-implied rails only.
Full technical write-up: Next-session report →
4 · Three ways the next session can go
If SPY pushes above the call wall ($780): That would take a move well beyond the $775.60 upper rail and through max pain at $777 and swing resistance at $777.05. Heavy call open interest at $780 tends to slow rallies. A clean break would leave thinner positioning overhead until the 52-week high at $781.62 and Friday's $785 call wall. Given a ±$6 priced move, this is the tail case.
If SPY reclaims $770 and drifts between the walls: This is the pin case. With the largest gamma concentration at $770 and October 15's max pain at $777, expiring open interest can pull price back into the low $770s, especially toward the $772 strike, where Friday's put wall and a large gamma stack sit. Range-bound premium sellers do best here.
If SPY stays below the put wall ($770) and slides: SPY is already a few cents under $770. In a negative-gamma regime, one rough estimate suggests hedging amplifies selling rather than cushioning it. The next checkpoints are the 50-day average at $768.57, the whole-chain put wall at $765, and the $763.60 lower rail. No gamma flip estimate is available today, so the line in the sand is the rail itself: a close below $763.60 breaks the neutral read.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 14, 2026. All structures are hypothetical unless flagged as an entered position. Verify live prices before trading. These will be stale by the open.
Because options are pricing in more movement than SPY has been delivering (76th percentile), the premium-selling structures lead. The neutral read makes the iron condor the best fit.
If you expect the range to hold: October 15 iron condor 760/763 – 776/779
An iron condor collects a credit by selling a put spread below the market and a call spread above it. You keep the credit if SPY stays between the short strikes.
- Trade: Sell the October 15 $763 put / buy the $760 put; sell the October 15 $776 call / buy the $779 call
- Credit: $0.53 ($0.32 put side + $0.21 call side)
- Max profit: $53 per condor
- Max loss: $247 per condor
- Break-evens: $762.47 and $776.53
- Why it fits: Both short strikes sit just outside the $763.60–$775.60 implied range, and the premium over delivered movement is in its 76th percentile. The $776 short call also sits just under max pain at $777 and swing resistance at $777.05.
- Makes sense only if: You accept a lopsided payoff (risking $247 to make $53) in exchange for a high-probability, one-day hold.
- Invalidated if: SPY closes below $763.60 (or trades through either short strike intraday)
- Managing it: Take profits at roughly 50% of the credit if SPY settles back near $770 early. If either short strike is touched, close that side rather than hoping for a reversal. Exit before the final hour of trading on October 15 to avoid pin and assignment noise.
- Liquidity note: The $763 and $760 puts and the $776 call each traded 1¢ wide. The $779 call is also 1¢ wide, but that is roughly 9% of its 11.5¢ mark, so use limit orders at the mid for the full four-leg package.
- Analyze this position →
If you lean bullish: October 15 $765/$762 put credit spread
A put credit spread collects premium up front and profits if SPY stays above the short put at expiration.
- Trade: Sell the October 15 $765 put / buy the October 15 $762 put
- Credit: $0.51
- Max profit: $51 per spread
- Max loss: $249 per spread
- Break-even: $764.49
- Why it fits: The short strike sits at the whole chain's heaviest put strike ($765), below the 50-day average ($768.57), with rich short-dated put premium to sell. The chart model's bullish lean and $771.80 target add mild support.
- Makes sense only if: SPY holds the 50-day average early in the session and puts stop building.
- Invalidated if: SPY closes below $765
- Managing it: Close at about 50% of the credit. If SPY breaks $767 (the chart model's invalidation for its bounce case), cut the trade. With the short-term flow fighting a flat bigger trend, take profits early rather than holding into the final hour.
- Liquidity note: The $765 puts traded $1.01 × $1.02 and the $762 puts $0.50 × $0.51, both 1¢ wide. Fills should be easy.
- Analyze this position →
If you lean bearish: October 15 $769/$764 put debit spread
A put debit spread pays a fixed amount for downside exposure, capping both cost and payoff.
- Trade: Buy the October 15 $769 put / sell the October 15 $764 put
- Debit: $1.56
- Max profit: $344 per spread
- Max loss: $156 per spread
- Break-even: $767.44
- Why it fits: Put open interest jumped, sweeps leaned put-side, and the negative-gamma estimate means a break of $770 can extend. The short $764 leg sits just above the $763.60 lower rail, so you are not paying for a move bigger than the market prices.
- Makes sense only if: SPY fails to reclaim $770 and loses the 50-day average at $768.57.
- Invalidated if: SPY closes above $772
- Managing it: Take profits near $764–$765 rather than waiting for the full payout. Exit if SPY reclaims $770 with conviction early in the session. Close before the final hour either way.
- Liquidity note: The $769 puts traded $2.36 × $2.37 and the $764 puts $0.80 × $0.81, both 1¢ wide.
- Analyze this position →
If none of these: no trade
Option prices are rich relative to delivered movement, which normally favors selling premium. Standing aside is still defensible here, for three reasons:
- Thin premium. An IV rank of 16.5 means the credits are small in absolute dollars. The condor risks about $4.70 for every $1 it can make.
- Negative gamma. The estimated regime means a break of $770 can move faster than a one-day expected move implies.
- Contradictory signals. Put-heavy flow argues one way and a bullish chart model the other, with no edge from either side.
If you can't watch the position through the October 15 session, the risk of a gap-and-run through a short strike is not worth $50 of credit.
6 · Quick FAQ
What is SPY's expected move for October 15? About ±$6.00 (±0.78%), a range of $763.60 to $775.60, per straddle pricing as of the October 14 close.
Is SPY expected to go up or down tomorrow? Options positioning as of October 14 reads Neutral. Put buying picked up sharply, but price is sitting on heavy put support and the bigger trend is flat. That is a read of what traders have done, not a forecast. The actionable map is the $763.60–$775.60 range with $770 support and $780 resistance.
Are SPY options expensive right now? IV rank of 16.5/100 says option prices sit low in their past-year range. They are also running about 3.3 vol points above the movement SPY has actually delivered, richer than 76% of its own recent readings. Premium is modestly rich relative to realized movement, but small in dollar terms.
Where is SPY's biggest options support and resistance? For the October 15 expiration, the put wall is $770 and the call wall is $780. Across the whole chain, the heaviest put strike is $765.
What invalidates the next session's read? A close below $763.60, the bottom of the options-implied range.
Methodology & disclosures. Data: end-of-day options-chain snapshot for SPY, 2026-10-14, generated 2026-10-14T21:05:04.466Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.