SPY Options Price a $7.18 Move Into October 23 — Positioning Leans Bearish While the Chart Model Leans Up
The options market implies a $756.78–$771.14 range for SPY into the October 23 expiration. Put building, steeper skew and bearish short-dated flow give the positioning read a slightly bearish lean, while the chart model points the other way.
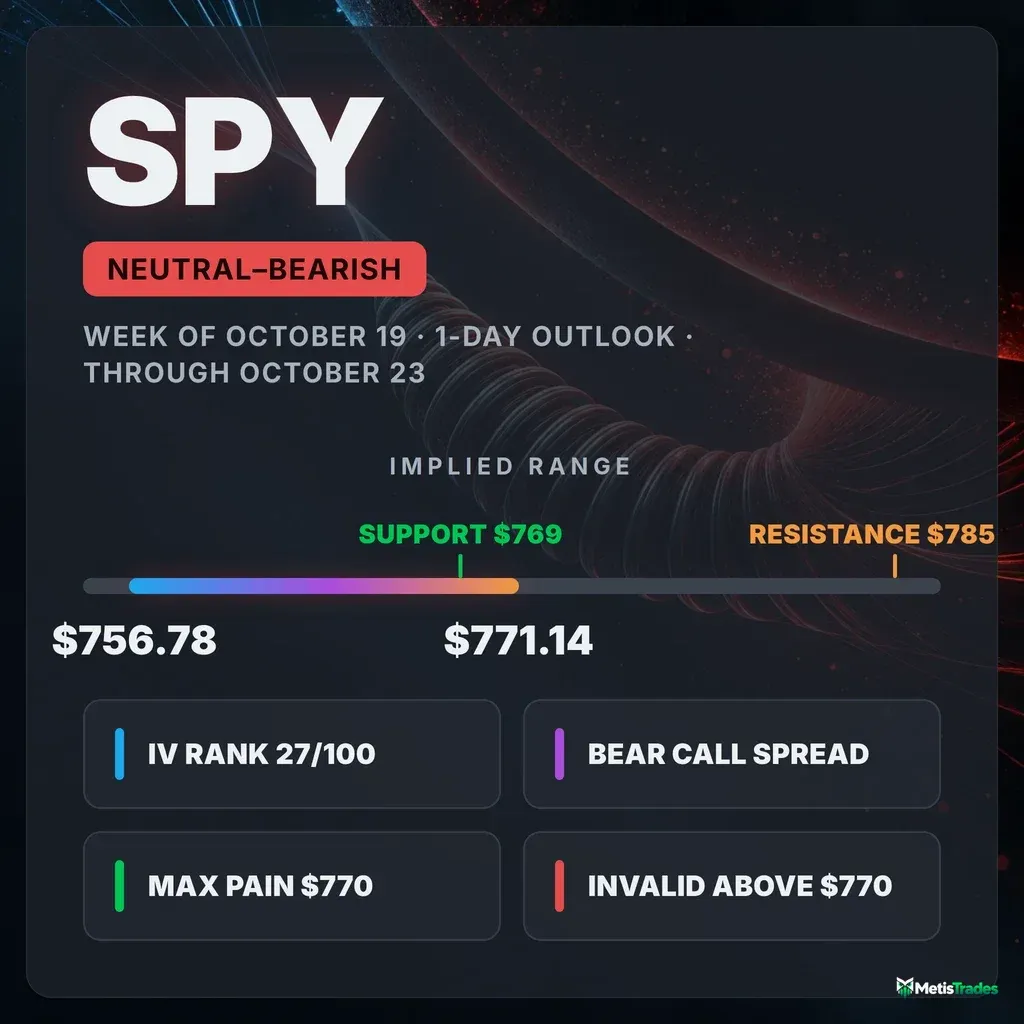
The options market implies a $756.78–$771.14 range into the October 23 expiration. Here's what's driving it, where the levels sit, and three defined-risk ways to trade the next session.
Published Thursday, October 22, 2026 · Data as of Thursday, October 22, 2026 close · Nightly update covering the next trading session (2026-10-23)
Explore the live SPY options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bearish |
| Options-implied range (into October 23) | $756.78 – $771.14 (±$7.18, ±0.94%) |
| Major support | $769.00 put wall (October 23). It now sits above spot, so the nearest structural support below is $761.25, with the whole chain's heaviest put strike at $760 |
| Major resistance | $785.00 call wall (October 23); nearer overhead, the whole chain's heaviest call strike and max pain sit at $770 |
| Max pain (October 23) | $770.00 |
| Dealer gamma regime (estimate) | Negative: hedging tends to amplify moves. Flip level n/a (the estimate could not place one today) |
| Volatility condition | Rising. IV rank 26.67/100 · premium rich: options priced ~5.3 vol pts above delivered movement |
| Technical check | Diverges (bullish, 2-day chart model; target $766.00, model range $757.50–$773.00) |
| Best-fitting strategy | Bear call spread above max pain (October 23), only if SPY stays below $770 |
| Analysis invalidated if | SPY closes above $770 |
1 · What matters today
Our read of the SPY options market is slightly bearish for tomorrow's session (2026-10-23). The main reason is that traders spent Thursday piling into puts. For every call contract held open there are now 1.84 puts, up from 1.06 five sessions ago. The options market is pricing a move of about $7.18 either way, which gives a range of roughly $756.78 to $771.14 into the October 23 expiration. The level that changes the picture is $770, which is both the "max pain" strike (where the most option value would expire worthless) and the heaviest call strike across the whole chain. A close above it undercuts the bearish lean. Option premiums are rich right now, so selling defined-risk spreads gets paid better than usual. The chart-based technical model disagrees and leans modestly higher, which is reason enough to keep position sizes small.
2 · What the options market is pricing
What changed this week
SPY closed Thursday at $763.96, down about 1.2% on the day from $773.09 and down 1.01% over five sessions. Options traders reacted more than the price did. Implied volatility (the market's estimate of how much SPY will move, baked into option prices) jumped 12% in a single day and 15.7% over five days. Measured against SPY's own recent history, that one-day jump in option prices was unusually sharp. The put/call open-interest ratio, which compares contracts held open on each side, climbed to 1.84. That is well above its 7-day average of 1.37 and its 14-day average of 1.05. Put/call volume ran at 1.13, versus a 7-day average of 1.05. The single biggest open-interest build was in the October 27 $767 puts, which went from 525 contracts to 37,241 in one day. On the bigger picture, the short (past week), medium (~20-day) and long (~50-day) trend reads all sit near flat, so this is a sharp near-term shift inside a market that has gone mostly sideways for two months. Flow scores tell the same story. Our momentum read swung from +19 on Wednesday to −38 on Thursday, after a 14-day average near −5.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the October 23 expiration it is ±$7.18, or ±0.94%, around the $763.96 snapshot price. That gives a one-session range of $756.78 to $771.14.
| Expiration | Implied move | Range around $763.96 |
|---|---|---|
| October 23 (next session) | ±0.94% | $756.78 – $771.14 |
| October 26 | ±1.37% | $753.49 – $774.43 |
| October 30 | ±2.43% | $745.40 – $782.52 |
| November 20 (~1 month) | ±4.29% | $731.19 – $796.73 |
The one-day rung stands out. The October 23 contracts carry an at-the-money IV of about 18.0%, against about 13.1% for October 26. Traders are paying a premium for tomorrow's session specifically, so the near-dated contracts are priced as if Friday-style volatility is likely.
Volatility
The blended at-the-money IV is 15.19%. That sits above both its 30-day average (13.2%) and its 90-day average (13.6%), and close to the ~2-month reading of 15.3%. IV rank shows where today's IV sits versus the past year. At 26.67/100, today's IV is cheaper than about 73% of the range it has covered over that period. Its percentile is 66, though, meaning IV has been lower than today on about two-thirds of past-year days. Option prices are low by yearly-range standards but climbing quickly. The front-month term-structure read, which compares option prices across expiration dates, is unavailable today because the nearest expiration (October 22) expired at the close. Realized movement is speeding up too. SPY's last five sessions have moved about 1.4× faster than its 20-day pace, which is unusually brisk acceleration for this ETF. The VIX closed at 19.03, up from 16.68, and SPY's implied volatility tracks the VIX very closely (60-day correlation of about 0.91). This is a broad-market volatility bid, not something specific to SPY.
Premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much SPY has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them. Today, SPY options are priced about 5.3 vol points above the roughly 9.9% realized volatility SPY has shown over 20 days. The gap's percentile is 93/100, meaning it is richer than 93% of this ETF's own recent readings. It has also roughly doubled over the past two weeks, from about 2.5 points in early October. An IV rank of 26.67 alongside a 93rd-percentile premium over delivered movement favors collecting premium with defined risk rather than buying it outright. Premium is cheap against the yearly range but expensive against what the market is actually doing.
Skew and sentiment
Skew means puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. Today, 25-delta puts trade at about 18.2% IV versus 13.3% for comparable calls, a gap of 4.9 vol points. That compares with a 60-day norm of 3.5 points and a 7-day average of 4.4. Traders are paying noticeably more than usual to protect against a drop, and the skew is stretched well past its own recent range. Short-dated sentiment is clearly negative. Options expiring within a week score −45 and those expiring in 7–30 days score −46 on our directional scale. Every expiration bucket leans the same way, so the overall regime reads "broadly bearish." The 7-day averages were much milder (−9 and −22), so Thursday's turn was abrupt. One counterweight is that unusual-size trades split evenly, with 21 standout call contracts and 21 standout put contracts. The aggressive sweeps were not one-sided.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Call wall (October 23) | $785 | Biggest pile of open calls for tomorrow's expiry (16,613 contracts). Far outside the implied range |
| 52-week high | $781.62 | SPY sits 2.26% below it |
| Swing resistance | $777.05 | Heuristic level from recent price pivots |
| Implied range top (October 23) | $771.14 | Upper edge of the one-session expected move |
| 20-day moving average | $770.72 | SPY closed 0.88% below it |
| Max pain (October 23) / whole-chain call wall | $770 | Where tomorrow's options would cause the least payout. Also the heaviest call strike across all expirations and the third-largest gamma strike. This is the invalidation line |
| Put wall (October 23) | $769 | Biggest pile of open puts for tomorrow (24,424). Now above spot, so these puts are in the money rather than acting as a floor |
| 50-day moving average | $768.17 | Overhead resistance and the technical model's key resistance |
| Large-gamma strikes | $767 / $765 | Heavy open interest close to spot, where hedging flows concentrate |
| Spot (close) | $763.96 | Thursday's close |
| Technical support | $761.25 | The chart model's support and its bullish-scenario invalidation |
| Whole-chain put wall / largest gamma strike | $760 | Heaviest put open interest across all expirations (193,137 contracts) |
| Swing support / 100-day average | $758.16 / $758.14 | Price-structure support clustered together |
| Implied range bottom (October 23) | $756.78 | Lower edge of the one-session expected move |
| Swing support | $746.81 | Next structural level below |
| 200-day moving average | $726.65 | Long-term trend support, 5.13% below |
Note the disagreement between tomorrow's expiration and the whole chain. October 23's own walls sit at $769 (puts) and $785 (calls). Across all expirations combined, the heaviest put strike is $760 and the heaviest call strike is $770. For the next session, the October 23 row is the one that applies.
Positioning and unusual flow
Market makers hedge the options they've sold. One rough estimate suggests their net gamma is negative, both across the chain and for October 23 alone. In that regime their hedging tends to amplify moves rather than dampen them, which fits the accelerating realized volatility. The estimate could not place a gamma-flip level today, so there is no clean "below here it gets worse" line to quote. A few flows stood out:
- October 27 $767 puts: open interest jumped by 36,716 contracts to 37,241, on 10,805 traded, worth roughly $6.5 million in premium. This is a large, fresh downside hedge placed just above spot for early next week.
- October 23 $763 calls: 61,268 contracts traded against just 1,106 open, about 55× turnover and roughly $22 million in premium. That is a heavy day-trade fight right at the money. Open interest barely changed, so most of it was opened and closed within the session.
- October 23 $769 puts: open interest at tomorrow's put wall fell by 6,478 contracts. Some of that downside protection was cashed in on Thursday's drop.
3 · Technical check
The chart-based technical model (2-day horizon, aimed at October 23) is bullish, with a target of $766.00 and a projected range of $757.50–$773.00. Its reference price of $764.02 matches the options snapshot. The direction runs against our slightly bearish positioning read, so this is a divergence. The target, however, sits comfortably inside the options-implied range, and the model's range is only slightly wider on top. Its case rests on a fresh MACD turn above its signal line and price reclaiming its short-term average on the heaviest recent volume. It acknowledges that ADX at 32 still describes a strong but weakening downtrend. Its dominant scenario is invalidated on a close below $761.25.
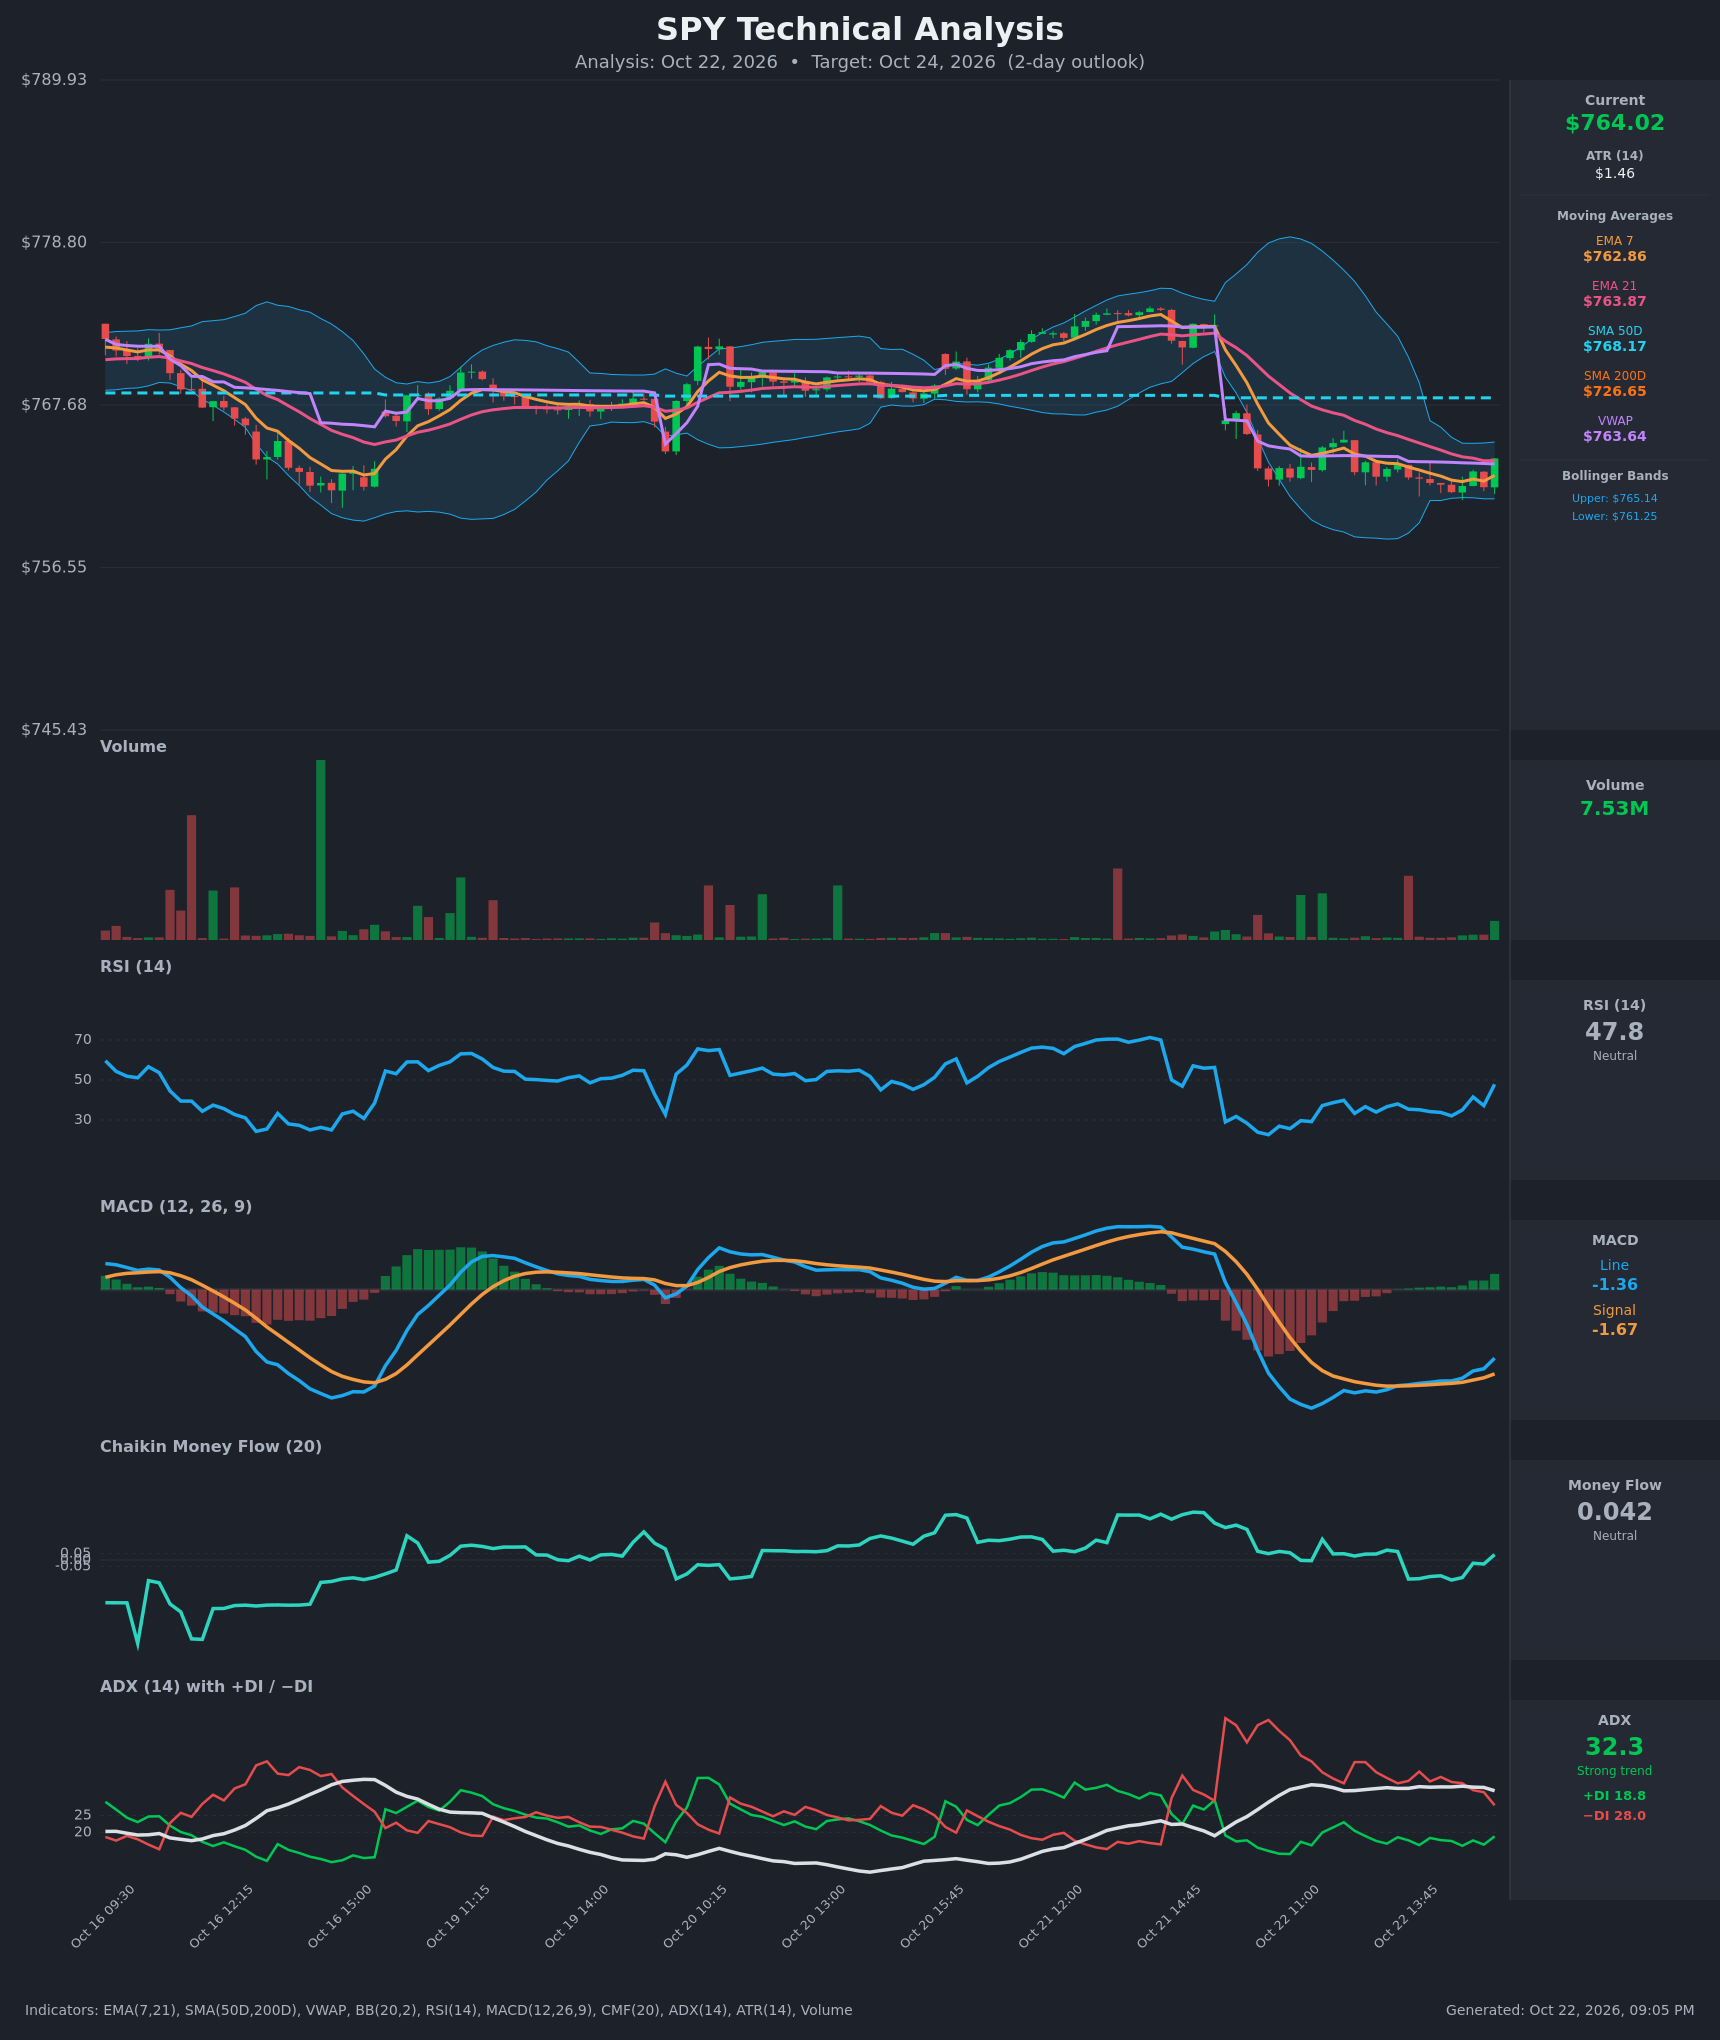
Model vs. Market: The options market implies $756.78–$771.14 into October 23; the 2-day technical model targets $766.00. The two agree on the size of tomorrow's move but disagree on direction. A close above $768.17 (the 50-day average) would favor the chart, while a break under $761.25 would side with the put builders.
The divergence shaped strike selection below. The bearish structure's short strike sits at $770, above both the model's $766 target and the 50-day average, so a modest technical bounce does not by itself break the trade.
Full technical write-up: Next-session report →
4 · Three ways the week can go
If SPY pushes above max pain and the call cluster ($770): Reclaiming $770 means clearing the heaviest call strike in the chain and the October 23 put wall just below it. Positioning thins out above there until $777 swing resistance, and October 23's own call wall sits much farther out at $785. With negative-gamma hedging, a clean break could extend rather than stall. That is the scenario where the bearish read is wrong.
If SPY drifts between $761 and $770: This is the pin case. Max pain at $770 sits above spot, and expirations sometimes gravitate toward that strike, so a drift back toward $767–$770 into the October 23 expiration would be ordinary behavior. It would also be consistent with the chart model's $766 target. Large gamma strikes at $765 and $767 can make the path choppy.
If SPY breaks below $760 (the whole chain's heaviest put strike): This is the acceleration case. Losing $760 puts the clustered $758 swing support and 100-day average in play, with the implied floor at $756.78 just beneath. Under the negative-gamma estimate, market-maker hedging can amplify selling rather than cushion it. The estimate cannot pin down a specific flip price today, so treat the whole $758–$760 zone as the fragile area.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 22, 2026. All structures are hypothetical. Verify live prices before trading, because these will be stale by the open. Because option premium is running rich versus delivered movement, the credit structures lead.
If you lean bearish: October 23 bear call spread
A credit spread means you collect premium up front and keep it if SPY stays below your short strike at expiration.
- Trade: Sell the October 23 $770 call / buy the October 23 $773 call
- Credit: $0.435 ($43.50 per spread) · Max profit: $43.50 · Max loss: $256.50 · Break-even: $770.44
- Why it fits: The short strike sits at max pain and the whole chain's heaviest call strike, above the chart model's $766 target and the 50-day average. You collect rich premium (about 5 points over delivered movement) while puts are being bought aggressively below.
- Makes sense only if: SPY stays under its 20-day average ($770.72) through tomorrow's session
- Invalidated if: SPY closes above $770
- Managing it: This is a one-day trade. Close it if SPY trades through $770 intraday rather than waiting for the close. Otherwise let it expire, or buy it back for a few cents late in the session.
- Liquidity note: The $770 calls traded 2¢ wide ($0.70/$0.72) and the $773 calls 1¢ wide ($0.27/$0.28). Fills should be easy.
- Analyze this position →
If you expect the range to hold: October 23 iron condor
An iron condor sells a put spread and a call spread together. You collect premium and keep it if SPY finishes between the short strikes.
- Trade: Buy the $755 put / sell the $757 put / sell the $771 call / buy the $773 call, all October 23
- Credit: $0.50 ($0.255 put side + $0.245 call side = $50 per condor) · Max profit: $50 · Max loss: $150 · Break-evens: $756.50 and $771.50
- Why it fits: The short strikes sit just at the implied range's edges ($756.78 / $771.14), and the 93rd-percentile premium means you are being paid unusually well for that one-day range.
- Makes sense only if: SPY opens near $764 without a large gap. Negative-gamma hedging is this trade's main enemy.
- Invalidated if: SPY closes outside $757–$771
- Managing it: If either short strike is touched, close the whole condor rather than defending it. One session leaves no time to recover.
- Liquidity note: The $757 puts traded 2¢ wide, the $755 puts 1¢, the $771 calls 2¢, and the $773 calls 1¢. Spreads are tight in dollar terms, but on these small premiums each cent matters, so work your order at the mid.
- Analyze this position →
If you lean bullish: October 23 bull call spread
A debit spread means you pay up front, and it gains value if SPY rises toward your short strike.
- Trade: Buy the October 23 $764 call / sell the October 23 $768 call
- Debit: $1.77 ($177 per spread) · Max profit: $223 · Max loss: $177 · Break-even: $765.77
- Why it fits: This is the chart model's case. It targets $766 with a stretch to the 50-day average at $768.17, and max pain at $770 sits above spot. Calls are cheap relative to puts given the steep skew, which makes the call side the better way to express an upside view.
- Makes sense only if: SPY holds above $761.25, the chart model's own invalidation
- Invalidated if: SPY closes below $761.25
- Managing it: Take profits near $767–$768 rather than waiting for expiration. Because the near-term move is fighting a flat-to-down short-term trend, an early exit is the disciplined choice.
- Liquidity note: The $764 calls traded 3¢ wide ($2.99/$3.02) and the $768 calls 3¢ wide ($1.22/$1.25). Liquidity is excellent.
- Analyze this position →
If none of these: no trade
Rich premium is a reason to consider selling. It does not oblige you to sell. Three things argue for standing aside tonight:
- Tail risk on one-day spreads. These spreads collect $43–$50 against $150–$257 of risk. One negative-gamma gap through a short strike erases several sessions of wins.
- Conflicting signals. Positioning and the chart model point in opposite directions.
- Why premium is rich. It reflects a realized-volatility pickup that is still accelerating (five-day movement running 1.4× the monthly pace), not calm conditions.
If you cannot watch the position during the session, or you don't want exposure to an opening gap, stepping aside and reassessing after tomorrow's close is a perfectly reasonable choice.
6 · Quick FAQ
What is SPY's expected move for October 23? About ±$7.18 (±0.94%), for a range of $756.78–$771.14, based on the options market's pricing as of the October 22 close.
Is SPY expected to go up or down in the next session? Options positioning as of October 22 leans slightly bearish, driven by heavy put building, steeper skew and bearish short-dated flow. That is a read of what traders have done, not a forecast. The actionable map is the $756.78–$771.14 range and the $770 max-pain line.
Are SPY options expensive right now? IV rank of 26.67/100 says option prices sit in the lower part of their past-year range. They are also running about 5.3 vol points above the movement SPY has actually delivered, which is richer than 93% of SPY's recent readings. Against the past year they look cheap. Against current conditions they look expensive, which favors defined-risk premium selling over outright option buying.
Where is SPY's biggest options support and resistance for October 23? The October 23 put wall is $769 and the call wall is $785. Across all expirations, the heaviest strikes are $760 (puts) and $770 (calls), and October 23 max pain is $770.
What invalidates this read? A close above $770.
Methodology & disclosures. Data: end-of-day options-chain snapshot for SPY, 2026-10-22, generated 2026-10-22T21:05:34.220Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.