AMZN Options Are Pricing a ±$9.41 Move Into September 25 — Our Read Says the Corridor Does the Work
The options market implies a $244.30–$263.12 range for Amazon into the September 25 expiration, with the heaviest call open interest parked at $260 and max pain sitting almost exactly on Friday's close. Here's what the flow actually shows — and three defined-risk ways to trade a split signal.
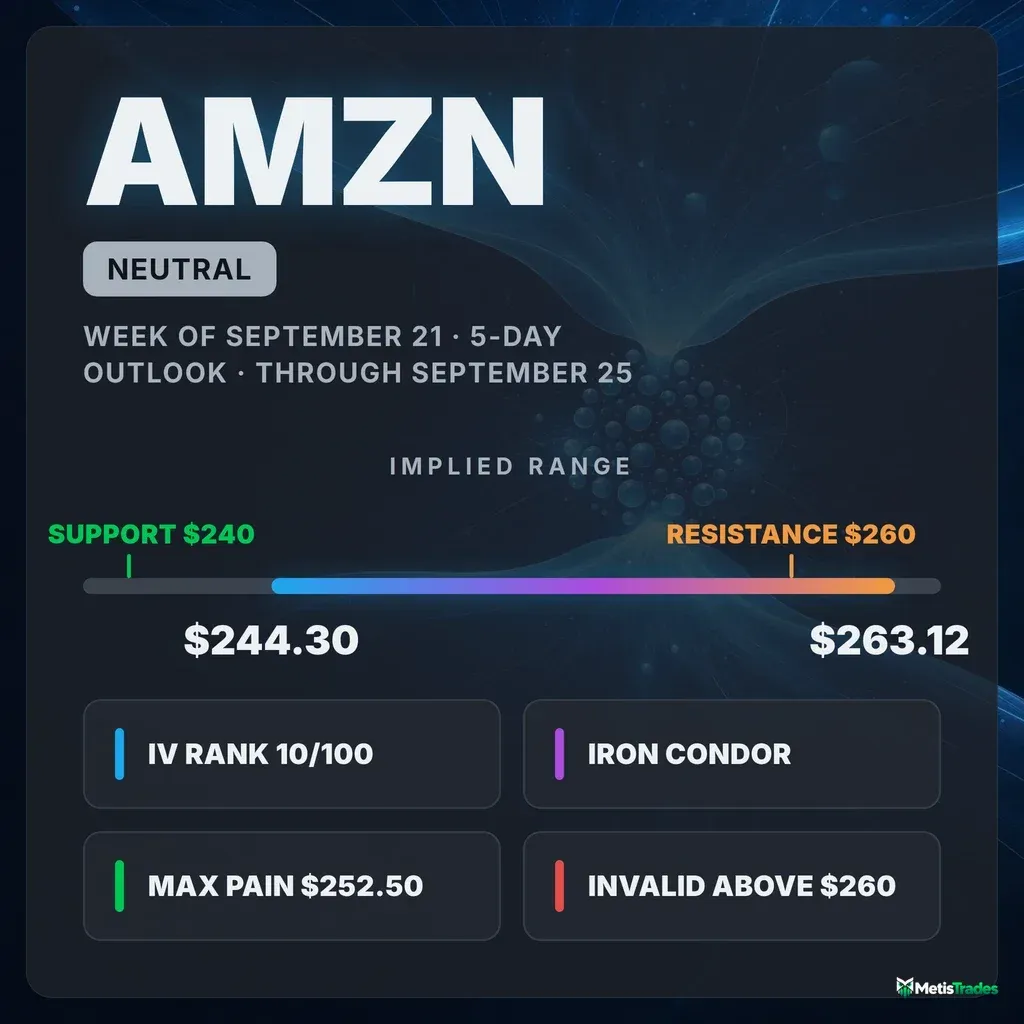
The options market implies a $244.30–$263.12 range into the September 25 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18 close
Explore the live AMZN options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into Sep 25) | $244.30 – $263.12 (±3.71%) |
| Major support | $240.00 (Sep 25 put wall) |
| Major resistance | $260.00 (Sep 25 call wall) |
| Max pain (Sep 25) | $252.50 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $260 |
| Volatility condition | Falling — IV rank 9.6/100 · premium fair: options priced ~2.7 vol pts above delivered movement |
| Technical check | Mixed (bullish, 3- and 5-day models) |
| Best-fitting strategy | Iron condor pinned to the Sep 25 rails |
| Analysis invalidated if | AMZN closes above $260.00 |
1 · What matters today
Amazon closed Friday, September 18 at $253.71, and the options market is pricing a move of about $9.41 either way into the September 25 expiration — a $244.30 to $263.12 range, derived from what at-the-money straddles cost. The flow underneath is genuinely split, and our bias comes out Neutral: traders chased calls hard into Friday's expiry, yet puts simultaneously got more expensive relative to calls. The single number that frames the next five days is $260 — the strike holding the biggest pile of open call contracts for this expiration, and also where one rough estimate places the dealer-hedging pivot. Max pain, the price at which the most option value would expire worthless, sits at $252.50, essentially on top of Friday's close. Two technical models lean mildly higher ($256.00 and $256.50), but both targets land comfortably inside the options-implied range.
2 · What the options market is pricing
What changed this week
The money moved to the call side, fast. Call open interest grew by 67,235 contracts while put open interest shed 46,392 in a single session, and the put/call open-interest ratio fell from 0.62 to 0.56 over five days — for every call contract held open there are now 0.56 puts, against a 7-day average of 0.63. Put/call volume told the same story: 0.36 on Friday (put volume relative to call volume; above 1 means puts dominate) versus a 7-day average of 0.46 and a 60-day median of 0.47. That is an unusually call-tilted session for this name, well beyond its own recent norm. Total option volume ran 1.21× its 20-day average, and the underlying traded 52.1 million shares against a 32.9 million 20-day average — expiry-day flow.
Where did the new positioning land? In the September 25 expiration itself: the $265 calls added 5,303 contracts of open interest on 5,289 contracts of volume, and the $260 calls added 4,594 on a heavy 15,717 traded. Into Friday's expiration, by contrast, the $260 puts shed 9,483 contracts of open interest — settled history, but it tells you hedges were being retired rather than rolled down. The counterweight: puts got pricier. And the price action gives none of it a mandate — our short-, medium- and long-term trend reads are all flat (price −1.2% over the past week, −2.5% over the past month, +2.7% over the past two and a half months), with only a faint bullish crossover in our momentum read on September 17 to show for the bounce.
Expected move
Into September 25, the options market is pricing a move of roughly ±$9.41, or ±3.71%, around Friday's $253.71 — that is the one-standard-deviation move implied by at-the-money option prices at that expiration. Here is how the rungs stack up (the September 21 and September 23 expirations are omitted: quote quality on those two was too poor to price a reliable expected move):
| Expiration | Implied move | Range around $253.71 |
|---|---|---|
| Sep 25 (7 days) | ±3.71% | $244.30 – $263.12 |
| Sep 30 (12 days) | ±4.81% | $241.51 – $265.91 |
| Oct 2 (14 days) | ±5.47% | $239.83 – $267.59 |
| Oct 16 (28 days) | ±7.97% | $233.49 – $273.93 |
The ladder climbs smoothly with time rather than jumping at any one rung — there's no kink in the curve to explain, which is itself information: the market isn't bracing for a dated event inside the next month.
Volatility
At-the-money implied volatility — the market's estimate of how much AMZN will move, baked into option prices — sits at 28.8%, with an IV rank of 9.6/100. That means today's reading is cheaper than roughly 90% of the past year's, and it has been drifting: down 1.5% on the day, 2.1% over five sessions and 7.5% over the past month, leaving it 1.7% under its own 30-day average and far below the 90-day average of 33.9%. The September 25 rung itself prices at 26.8%. The front-month read is unavailable today — Friday was an expiry day, which makes that particular comparison uncomputable — so we're reading levels rather than the slope across dates.
Realized movement has been quiet too: 20-day realized volatility is 26.1%, running below this stock's own recent norm, with the 10-day at 23.1%. The last five sessions have been fractionally busier than the trailing month, but only fractionally — about typical for AMZN.
Premium rich or cheap? The gap between what options are priced for and what the stock has actually delivered — the volatility risk premium — stands at about 2.7 vol points in favor of sellers. When that gap is positive, option sellers have been collecting more than realized movement cost them. Where today's gap sits versus this stock's own recent readings: the 44th percentile — richer than 44% of them, which is to say squarely average. That gap has also been narrowing, from about 5.7 points on September 10 to 2.7 now, as implied vol slid while delivered movement crept up. Put the two lenses together — an IV rank of 9.6 and a 44th-percentile premium over delivered movement — and the verdict is "fair, not rich." Premium selling here is a structure choice, not an edge; if you sell, sell defined-risk and don't expect the volatility itself to pay you.
Skew and sentiment
Here is the tension in one number. Puts and calls the same distance from the stock price don't cost the same, and right now the 25-delta put is running 2.7 vol points over the 25-delta call (30.6% versus 27.9%) — against a 60-day median of just 0.4 points for this name. Traders are paying up for downside protection at a pace that is unusually steep by AMZN's own history, and the steepening happened fast: the gap widened roughly 2.6 points over five sessions.
That sits directly against the volume picture. Call-side sweeps dominated the unusual-flow set (seven call contracts cleared the peer-relative bar versus three puts), net new open interest leaned hard to calls, and put/call volume at 0.36 is unusually low for this name. So: heavy call buying and expensive crash protection, at the same time.
Sentiment across the curve has cooled to match. Our read of short-dated options came in at −5 for contracts expiring inside a week and +3 for the one-week-to-one-month bucket — both essentially flat, and both a long way from where they sat a week ago (+19 and +20 on a 7-day average). The one-phrase summary for the whole curve is Calm. That cooling is driven almost entirely by the skew: in the front bucket, puts are 3.7 vol points richer than their own 60-day baseline.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $287.20 | 11.7% overhead; the ceiling of the past year's range |
| Whole-chain heaviest call strike | $280.00 | 115,347 open call contracts across all expirations — a longer-dated magnet, not this week's |
| Swing resistance | $266.98 | Next structural shelf above the implied range |
| Implied range high (Sep 25) | $263.12 | Top of the one-standard-deviation band |
| Call wall (Sep 25) | $260.00 | 13,334 open call contracts — the heaviest at this expiration; also the largest gamma strike chain-wide and the estimated hedging pivot |
| Swing resistance | $256.77 | Recent pivot cluster |
| 20-day moving average | $256.13 | Price sits 0.95% below it |
| 50-day moving average | $255.84 | Immediate overhead; also the technical models' named resistance |
| Friday's close | $253.71 | Starting point for every range above and below |
| Max pain (Sep 25) | $252.50 | Where the most option value would expire worthless — expirations sometimes gravitate toward it |
| Swing support / heavy gamma | $250.00–$250.38 | Second-largest gamma pile in the chain plus a pivot shelf |
| Sep 17 gap zone | $245.96–$251.07 | An unfilled 2.1% up-gap; gaps like this are common retest targets |
| Implied range low (Sep 25) | $244.30 | Bottom of the one-standard-deviation band |
| 200-day moving average | $240.30 | Price is 5.6% above it — the longer-term uptrend marker |
| Put wall (Sep 25) | $240.00 | 6,022 open put contracts at this expiration — and the whole chain's heaviest put strike too, at 66,422 |
| Swing support | $238.25 | Next shelf below the wall |
Two notes on that table. First, the walls for the September 25 expiration and for the whole chain combined agree on the downside ($240 either way) but disagree badly on the upside: the whole chain's heaviest call strike is $280, driven by far-dated positioning, while this expiration's call wall is $260. For the next five days, $260 is the number that matters. Second, the gamma-flip level and dealer-gamma regime are estimates built on an assumed convention about how dealers are positioned, not observed inventory — and those two estimates don't quite line up this week: the signed figure reads positive (hedging that tends to dampen moves) while spot sits about 2.5% below the estimated $260 pivot. Treat $260 as a level to watch, not a mechanical trigger.
Positioning and unusual flow
One rough estimate puts dealer gamma in positive territory for the September 25 expiration, the regime in which market-maker hedging tends to cushion moves rather than accelerate them — consistent with the calm implied by a 9.6 IV rank and a max-pain strike sitting $1.21 under the close.
Three flow items are worth naming. The loudest, in dollar terms, is the one we're not reading as a signal: about $21.5 million of premium changed hands in September 21 $275 puts that carried zero open interest, alongside similar prints at $277.50 and $267.50. Deep in-the-money contracts trading in size against no open interest usually reflect financing or exercise mechanics rather than a directional bet, so we discount them entirely.
The two that do matter both sit in the target expiration. The September 25 $260 calls traded 15,717 contracts against 13,334 open — about $2.3 million of premium — and added 4,594 contracts of open interest, which is exactly how a call wall gets built. One strike higher, the $265 calls turned over 5,289 contracts and added 5,303 of open interest, i.e. almost all of that volume was new positioning. Meanwhile the $255 calls saw the single largest premium print at this expiration, $4.1 million, in the tightest market on the board. Upside is where the week's money went — into strikes that sit above the wall and cap it.
3 · Technical check
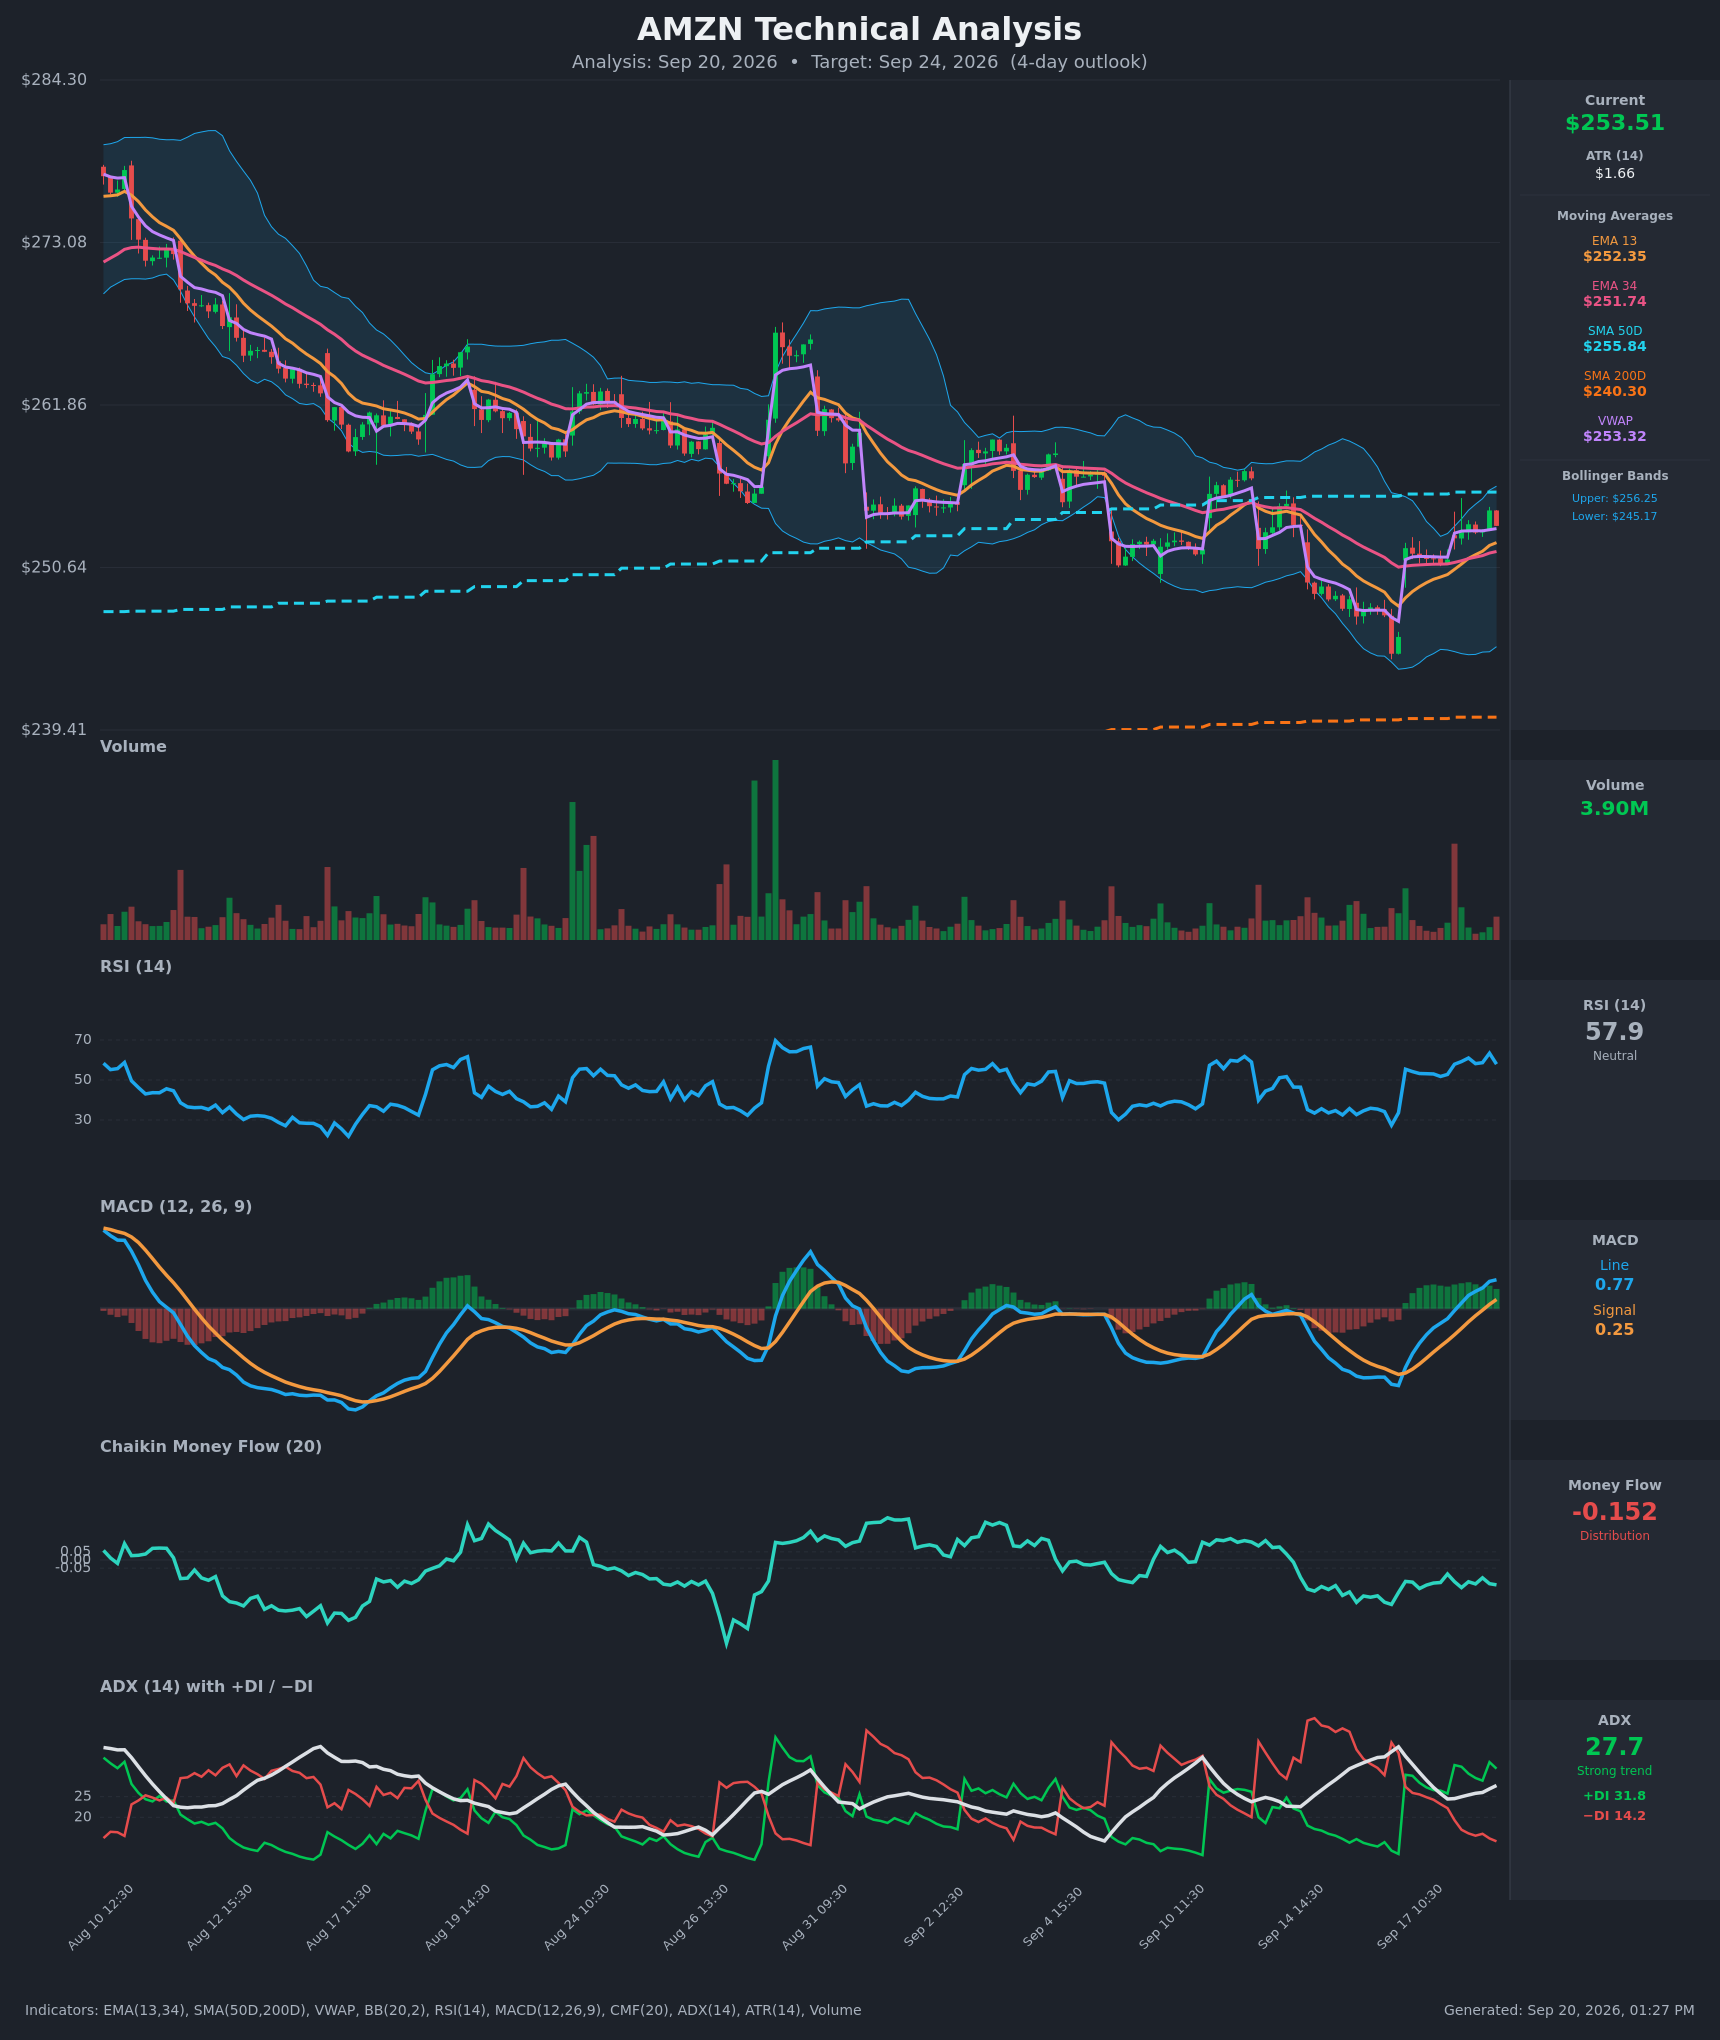
Both chart models lean the same way. The 3-day read (target date September 23) is bullish with a target of $256.00 and a projected range of $249.00 to $258.50; the 5-day read (target date September 25, the same date our options thesis runs to) is bullish with a target of $256.50 and a projected range of $247.50 to $259.50. Both reference prices ($253.51) sit within a rounding error of the options snapshot's $253.71, so the two datasets are describing the same market.
The decisive indicator reads cut both ways, which is why we call this mixed rather than a confirmation. On the constructive side, the trend-strength measure sits at 27.7 with the positive directional line (31.8) well clear of the negative one (14.2) — a genuine trend with buyers in control of the last two sessions, backed by a short-term moving-average crossover on September 18. On the cautionary side, the money-flow measure is at −0.152 and has stayed negative through the entire bounce from roughly $246 to $254: the rally has come on distribution, not accumulation. Both models cap their targets under the 50-day average at $255.84–$256.25 for exactly that reason, and both name a close back below $251.00–$251.74 as what breaks their setup.
Crucially, neither model's target escapes the options-implied range, and both of their projected ranges sit inside it. That means the technicals shade strike selection rather than overturning the bias: we've kept the short call of the range structure above the $260 wall and above the models' resistance zone, and anchored the bullish structure's short put to the $250 shelf that both reports name as support.
Model vs. Market: The options market implies $244.30–$263.12 into September 25; the 5-day technical model targets $256.50 with a $247.50–$259.50 range. The chart is asking for a modest grind up into the 50-day average while the options are pricing a wider two-sided band — a gap that resolves not with a target but with a level: a close above $260 says the chart won, a close below $250 says the sellers the money-flow read has been flagging were right all along.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If AMZN pushes above the call wall ($260): the heaviest open call interest at this expiration sits right there, and strikes like that tend to slow rallies as the dealers on the other side hedge into strength. It is also, by one rough estimate, the hedging pivot. A clean close through it leaves comparatively thin positioning up to the implied high at $263.12, then swing resistance near $266.98 — and it would be the cleanest evidence that the week's heavy call buying was directional rather than speculative lottery-ticket flow.
If AMZN drifts between the walls: this is the case the positioning favors. Max pain for September 25 is $252.50, $1.21 below Friday's close, and the estimated dealer-gamma regime is the kind that dampens rather than amplifies. Expiring open interest and hedging flows in that regime tend to pull price toward the middle of the corridor, with the 50-day average at $255.84 capping and the $250 gamma shelf catching. A week that ends between roughly $250 and $257 would surprise nobody reading this chain.
If AMZN breaks below the put wall ($240):
That requires a 5.4% slide — below the implied low of $244.30 and through the 200-day average at $240.30 — so it is the tail, not the base case. The route there runs through the unfilled September 17 gap ($245.96–$251.07) first. Note that spot currently sits about 2.5% below the estimated flip level near $260, which our positioning read calls an about-typical distance for this name; below such a pivot, one rough estimate suggests market-maker hedging amplifies selling rather than cushioning it, which is the mechanism that would turn a drift into a slide. The steep put skew says somebody is paying real money against that tail.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of September 18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you expect the range to hold: Sep 25 iron condor
- Trade: Sell the Sep 25 $245/$240 put spread and the Sep 25 $262.50/$267.50 call spread (four legs, one package). A credit structure: you collect premium up front and keep it if price stays between the short strikes.
- Credit: ~$1.07 · Max profit: $107 · Max loss: $393 · Break-evens: $243.93 and $263.57
- Why it fits: both short strikes sit at roughly 18-delta and straddle the implied rails, and the break-evens land just outside the $244.30–$263.12 range the market itself is pricing. Max pain at $252.50 sits dead center, and the estimated dampening gamma regime is the backdrop this structure wants.
- Makes sense only if: you accept a small credit for a wide, quiet corridor. With an IV rank of 9.6 and a merely average premium over delivered movement, you are not being paid a fat price for the risk — you are being paid for the corridor's width.
- Invalidated if: AMZN closes above $260.00 (or below $244.30).
- Managing it: close at roughly 50% of max credit; exit the whole package by September 23 regardless if neither side has decayed, because the last two sessions before expiration are where the gamma risk lives. If price closes through either short strike, close rather than hope.
- Liquidity note: the $245 puts traded 9¢ wide and the $262.50 calls 14¢ wide on Friday; the $240 put wing was 12¢ and the $267.50 call wing 4¢. Percentage-wise those wings are wide relative to their small marks, so enter as a single limit order on the package — legging in will leak most of the credit.
- Analyze this position →
If you lean bullish: Sep 25 $250/$245 put credit spread
- Trade: Sell the Sep 25 $250 put, buy the Sep 25 $245 put. You collect a credit and keep it as long as AMZN holds above $250 into expiration.
- Credit: ~$1.27 · Max profit: $127 · Max loss: $373 · Break-even: $248.73
- Why it fits: $250 is the shelf both technical models name as support, it carries the chain's second-largest gamma pile, and it sits above the implied low. The week's flow also fits: puts thinning, calls building, and a leading positioning read that has climbed while price fell — the kind of split that has historically preceded a turn, though it is an early and unconfirmed read by construction.
- Makes sense only if: you believe the call-side buying, not the steep put skew, is the honest signal. Those two are fighting, and this structure takes a side.
- Invalidated if: AMZN closes below $250.00.
- Managing it: take profit at ~50% of the credit; with the near-term trend reads flat and the longer trend going nowhere, don't hold a directional credit spread to the wire — flat trends whipsaw. Exit by September 23 if it hasn't worked.
- Liquidity note: the $250 puts traded 10¢ wide (about 4.5% of mid) and the $245 puts 9¢ — the tightest put pair at this expiration; fills should be straightforward.
- Analyze this position →
If you lean bearish: Sep 25 $260/$265 call credit spread
- Trade: Sell the Sep 25 $260 call, buy the Sep 25 $265 call. You collect a credit and keep it as long as AMZN stays below $260.
- Credit: ~$0.77 · Max profit: $77 · Max loss: $423 · Break-even: $260.77
- Why it fits: you are selling directly into the expiration's call wall — 13,334 open contracts at $260, the largest gamma strike in the chain, and the estimated hedging pivot, with the 50-day average at $255.84 standing in front of it. The steep 25-delta skew says the market is pricing downside risk more richly than upside, and price is below its 20-, 50- and 100-day averages.
- Makes sense only if: you read the heavy $260 and $265 call buying as speculative rather than a precursor to a breakout — because that same buying is what you are selling to.
- Invalidated if: AMZN closes above $260.00.
- Managing it: the risk/reward is the least attractive of the three (5.5:1), so treat it as a small position and close at ~50% of credit. Both technical models lean the other way, which argues for a short leash and an exit by September 23.
- Liquidity note: the $260 calls traded 13¢ wide on huge volume; the $265 calls were 17¢ wide on a $0.70 mark — wide in percentage terms, so use a package limit and expect to give up a cent or two.
- Analyze this position →
If none of these: no trade
There's a respectable case for standing aside. An IV rank of 9.6/100 means option prices are near the bottom of their yearly range, and the premium over delivered movement is merely average — so every credit structure above pays a thin credit against a multiple of that in risk, and every debit structure has to overcome a genuinely flat set of trend reads to pay off. Our bias is Neutral because the signals disagree, not because we've found a comfortable middle: heavy call buying and unusually steep put skew are pointing opposite ways, and when the cheapest thing in the market is the option itself, waiting for either the skew to normalize or the price to pick a side costs you nothing but patience. If you're already short premium elsewhere in this name, adding more here is paying for the privilege of being right about nothing much.
6 · Quick FAQ
What is AMZN's expected move this week? About ±$9.41, or ±3.71%, into the September 25 expiration — a $244.30 to $263.12 band, per the options market's straddle pricing as of September 18.
Is AMZN expected to go up or down over the next five days? Options positioning as of September 18 is genuinely split — call buying and call open-interest building on one side, unusually steep put skew on the other — so our read is Neutral, and that's a description of what traders have already done, not a forecast. The actionable map is the $244.30–$263.12 range plus the $240 and $260 levels.
Are AMZN options expensive right now? Two lenses, same answer. An IV rank of 9.6/100 says option prices are lower than about 90% of the past year's readings; on top of that, they're running roughly 2.7 vol points above the movement AMZN has actually delivered — richer than about 44% of this stock's own recent readings, which is to say average. Verdict: cheap versus the year, fair versus recent reality.
Where is AMZN's biggest options support and resistance? For the September 25 expiration, the put wall is $240.00 (6,022 open contracts) and the call wall is $260.00 (13,334). The whole chain combined puts its heaviest call strike much higher, at $280, but that's driven by far-dated positioning and isn't this week's ceiling.
What invalidates this read? A close above $260.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for AMZN, 2026-09-18, generated 2026-09-20T13:27:16.720Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.