ARM Options Are Pricing a $22.73 Move Into Nov. 20 — The Chart Model Sees Only a Drift to $186.50
ARM options imply a $167.80–$213.26 range into the November 20 expiration. Premium is running well below what the stock has actually delivered, and positioning is close to balanced. Here is the levels map and three defined-risk ways to trade it.
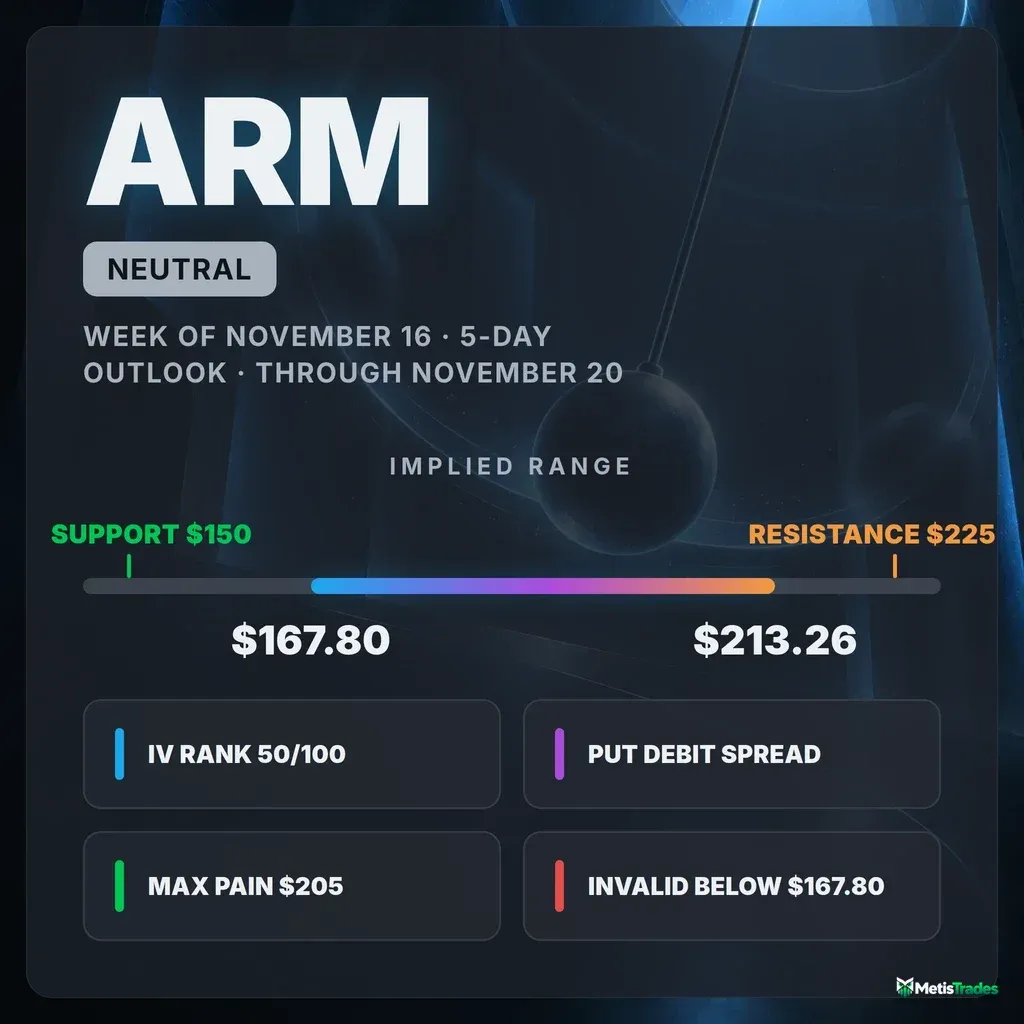
The options market implies a $167.80–$213.26 range for ARM into the November 20 expiration. Below: what is driving that range, where the walls sit, and three defined-risk ways to trade it.
Published Sunday, November 15, 2026 · Data as of Friday, November 13, 2026 close
Explore the live ARM options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into Nov 20) | $167.80 – $213.26 (±11.93%, ±$22.73) |
| Major support | $150 (Nov 20 put wall) |
| Major resistance | $225 (Nov 20 call wall) |
| Max pain (Nov 20) | $205 |
| Dealer gamma regime (estimate) | Negative — hedging tends to amplify moves; flip level ≈ $115 |
| Volatility condition | Neutral — IV rank 49.7/100 · premium thin: options priced ~22 vol pts below delivered movement |
| Technical check | Diverges (bearish, 3-day and 5-day; 5-day target $186.50) |
| Best-fitting strategy | Debit spreads over premium selling — put debit spread leads, entered only on a confirmed break lower |
| Analysis invalidated if | ARM closes below $167.80 |
1 · What matters today
ARM closed Friday, November 13, 2026 at $190.53. Our read of options positioning is neutral. Put buying has eased sharply from last week's panic, but traders are still paying more for downside protection than this stock normally does, so neither side has control. The options market is pricing a move of about $22.73 either way into the November 20 expiration, which gives a range of $167.80 to $213.26.
The most important fact is that ARM has been moving even more than that. Options are priced well below the movement the stock has actually delivered, which makes selling premium unattractive. The level that changes the picture is $167.80. A close below it breaks the range and points toward thinner positioning down near $150.
The chart-based technical model leans bearish but expects only a small drift, to $186.50.
2 · What the options market is pricing
What changed this week
The past week was a rebound. ARM gained 9.1% over five sessions after the early-November collapse, including a 10.3% gap down on November 5. Still, the week ended on two down gaps: −6.39% on November 12 and −1.65% on November 13.
The options flow tells a de-escalation story:
- Puts are thinning. Put open interest (contracts currently held open) shrank relative to calls. For every call held open there are now 1.37 puts, against a 7-day average of 1.64 and about 1.95 five sessions ago. That pace of put unwinding is unusually fast for ARM by its own recent standards.
- The momentum read turned neutral. Our options-flow momentum read sits essentially at zero today. Its 7-day average is clearly negative, so flow has gone from persistently bearish to neutral within about three sessions.
- The biggest open-interest addition was protective. It came in the December 18 $170 puts, which added 682 contracts to 5,284. That is a hedge being layered further out in time, not a bet on this week.
The bigger tension is between timeframes. The past week's bounce runs against a stock still down 16.4% over the past month and 21.5% over roughly the last 50 sessions. Near-term flow and the larger trend point in different directions, which argues for short-dated structures and quick profit-taking.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. Into the November 20 expiration it is ±$22.73, or ±11.93% of the $190.53 spot. That is a very wide band for a single week, and it reflects how violently ARM has traded.
| Expiration | Implied move | Range around $190.53 |
|---|---|---|
| Nov 20 | ±11.93% | $167.80 – $213.26 |
| Nov 27 | ±14.61% | $162.69 – $218.37 |
| Dec 4 | ±17.95% | $156.33 – $224.73 |
| Dec 18 | ±22.77% | $147.15 – $233.91 |
The rungs widen smoothly with time; there is no single-date hump. The front week, however, carries the richest per-day pricing. The Nov 20 at-the-money IV is about 86%, versus roughly 75% for the following weeks. Traders are paying extra for the next few sessions specifically.
Volatility
Implied volatility (IV) is the market's estimate of how much ARM will move, baked into option prices. ATM IV is 75.03%.
- IV rank is 49.7/100. IV rank shows where today's IV sits versus the past year, so 49.7 means it is cheaper than roughly half of the past year's range. On a percentile basis, IV sits above about two-thirds of the past year's daily readings.
- Direction is mixed. IV rose 4.2% on Friday but is down 3.2% over five sessions. It sits almost exactly on its 30-day average (74.9%) and below its 90-day average (78.0%).
- Term structure is unavailable today. The usual front-month comparison of option prices across expiration dates is unavailable because of the Friday expiry. The per-expiration table above shows the front week priced richest.
Realized volatility is the bigger story. Over the past 20 sessions ARM has moved at a 97.1% annualized pace, and over the past 10 sessions at 115.2%. Both run well above this stock's own recent norm, and the short-window pace is still accelerating relative to the month.
Premium is thin, not rich. The volatility risk premium is the gap between how much movement options are priced for and how much ARM has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them. Right now it is negative: options are priced about 22 vol points below what ARM has delivered.
That gap sits at the 22nd percentile of this stock's recent readings. In other words, premium is thinner than about four-fifths of them, and the gap is unusually depressed for ARM. The flip happened quickly. The gap was a positive 11–12 points in late October, turned negative on November 6, and bottomed near −29 points on November 11. That swing came from realized volatility exploding as the large gap days entered the 20-day window, not from options getting cheap in isolation.
The combination of a mid-range IV rank and a 22nd-percentile premium favors owning premium through defined-risk debit structures this week over collecting it.
Skew and sentiment
Skew means puts and calls the same distance from the stock price don't cost the same; when puts are pricier, traders are paying up for crash protection.
- Skew is still put-heavy, but easing. 25-delta puts trade at 76.2% IV against 73.2% for calls, so puts run about 3.0 vol points over calls. ARM's norm over the past 60 days is the reverse: calls about 3.2 points richer. Skew is therefore steeper than usual for this name. It has also flattened fast, from roughly 17 points on November 6 and a 7-day average near 9.2 points. Traders are still paying for protection, just much less urgently.
- Volume leans toward puts. The put/call ratio measures put activity relative to calls; above 1 means puts dominate. Put/call volume was 0.93 on Friday, below its 7-day average of 1.04 but well above ARM's 60-day median of about 0.62. Total option volume ran 1.53× its 20-day average.
- Short-dated sentiment is flat. Sentiment in options expiring within 7 days is essentially neutral, slightly negative, after averaging clearly positive over the past week. The 7–30 day group is slightly positive after averaging negative. The two have swapped places, and the overall regime reads Mixed. Longer-dated options (30–120 days) remain put-tilted.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 50-day moving average | $248.14 | Far overhead; marks how deep the two-month decline runs |
| 200-day moving average | $232.82 | Long-term trend line, well above price |
| Swing resistance / Nov 20 call wall | $225.46 / $225 | Heaviest Nov 20 call open interest (2,381) sits right on a price-structure ceiling |
| Large gamma strike / swing resistance | $220 / $219.39 | Third-largest gamma concentration across the chain |
| Upper implied rail (Nov 20) | $213.26 | Top of the priced one-week range |
| Large gamma strike / swing resistance | $210 / $208.90 | Near the November 11 bounce high |
| 20-day moving average | $205.53 | Short-term trend line ARM is trading below |
| Max pain (Nov 20) | $205 | Price where the most Nov 20 option value would expire worthless — sits above spot |
| Whole-chain call wall | $200 | Largest call open interest across all expirations (15,205); top gamma strike |
| Close | $190.53 | Friday's close |
| Whole-chain put wall | $190 | Heaviest put open interest across all expirations (11,920); second-largest gamma strike |
| Large gamma strike | $180 | Fifth-largest gamma concentration |
| Lower implied rail (Nov 20) | $167.80 | Bottom of the priced range; this article's invalidation level |
| Swing support | $163.13 | Near the early-November low area |
| Nov 20 put wall | $150 | Heaviest Nov 20 put open interest (2,445) |
| Gamma flip (estimate) | $115 | Rough estimate of where hedging behavior changes; far below price |
| 52-week low | $100.02 | Year's floor; the 52-week high is $452.70 |
A call wall or put wall is the strike with the biggest pile of open call or put contracts, and these often act like magnets or barriers. Note that the November 20 expiration's own walls ($225 and $150) bracket a much wider zone than the whole chain's walls ($200 and $190), which pin price from both sides. This week, the tighter $190–$200 band is where most of the gamma (hedging sensitivity) lives.
Positioning and unusual flow
Dealer gamma. Market makers hedge the options they've sold; in a negative-gamma regime, their hedging tends to amplify moves. One rough estimate puts both the whole chain and the November 20 expiration in negative territory. That fits a stock that has been gapping 5–10% at a time. The same estimate places the flip level near $115, far below price, so treat the regime label as a loose description of conditions, not a precise trigger.
Notable flow on Friday:
- Nov 20 $192.5 calls: 2,322 contracts traded against just 177 open, about $1.89 million in premium. This was the single heaviest dollar flow in the chain, concentrated right at the money.
- Nov 20 $197.5 calls: 2,079 contracts against 82 open, about $1.26 million. Traders were positioning for a short-term pop back toward the $200 whole-chain call wall.
- Nov 20 $150 puts: 2,109 contracts on 2,445 open. This is the crash-protection strike that defines this week's put wall, traded heavily even as most other puts were being closed.
Read together, near-dated speculators were playing a bounce while hedgers kept the far-downside insurance. That two-sided flow is why we read the setup as neutral.
3 · Technical check
Both technical reports lean bearish and expect little movement.
- 3-day report: bearish, targeting $187.60 by November 18 with a projected range of $183.00 to $193.00.
- 5-day report: bearish, targeting $186.50 by November 20 with a projected range of $183.50 to $196.00. It names $186.47 (the post-gap low) as support and $192.54 (the short-term moving-average cluster) as resistance.
Both targets sit well inside the options-implied range. Because the direction differs from our neutral options read, we classify the check as Diverges. The divergence is mild: a $4 drift, not a breakdown.
The decisive technical reads are a bearish MACD crossover below zero and a flag-like consolidation under the falling averages. Against that, money-flow (CMF) readings remain strongly positive, suggesting buyers are absorbing selling. The dominant scenario in both reports is invalidated by a close above $193.
Model vs. Market: The options market implies $167.80–$213.26 into November 20; the 5-day technical model targets $186.50. The chart model expects a quiet slide, while options are priced for a much bigger swing — and ARM has recently moved even more than options price. A daily close outside $183.50–$196.00 would show the market, not the model, had the size right.
The technical support at $186.47 and the $193 invalidation shaped two choices below: the trigger for the bearish structure and the stop for the bullish one.
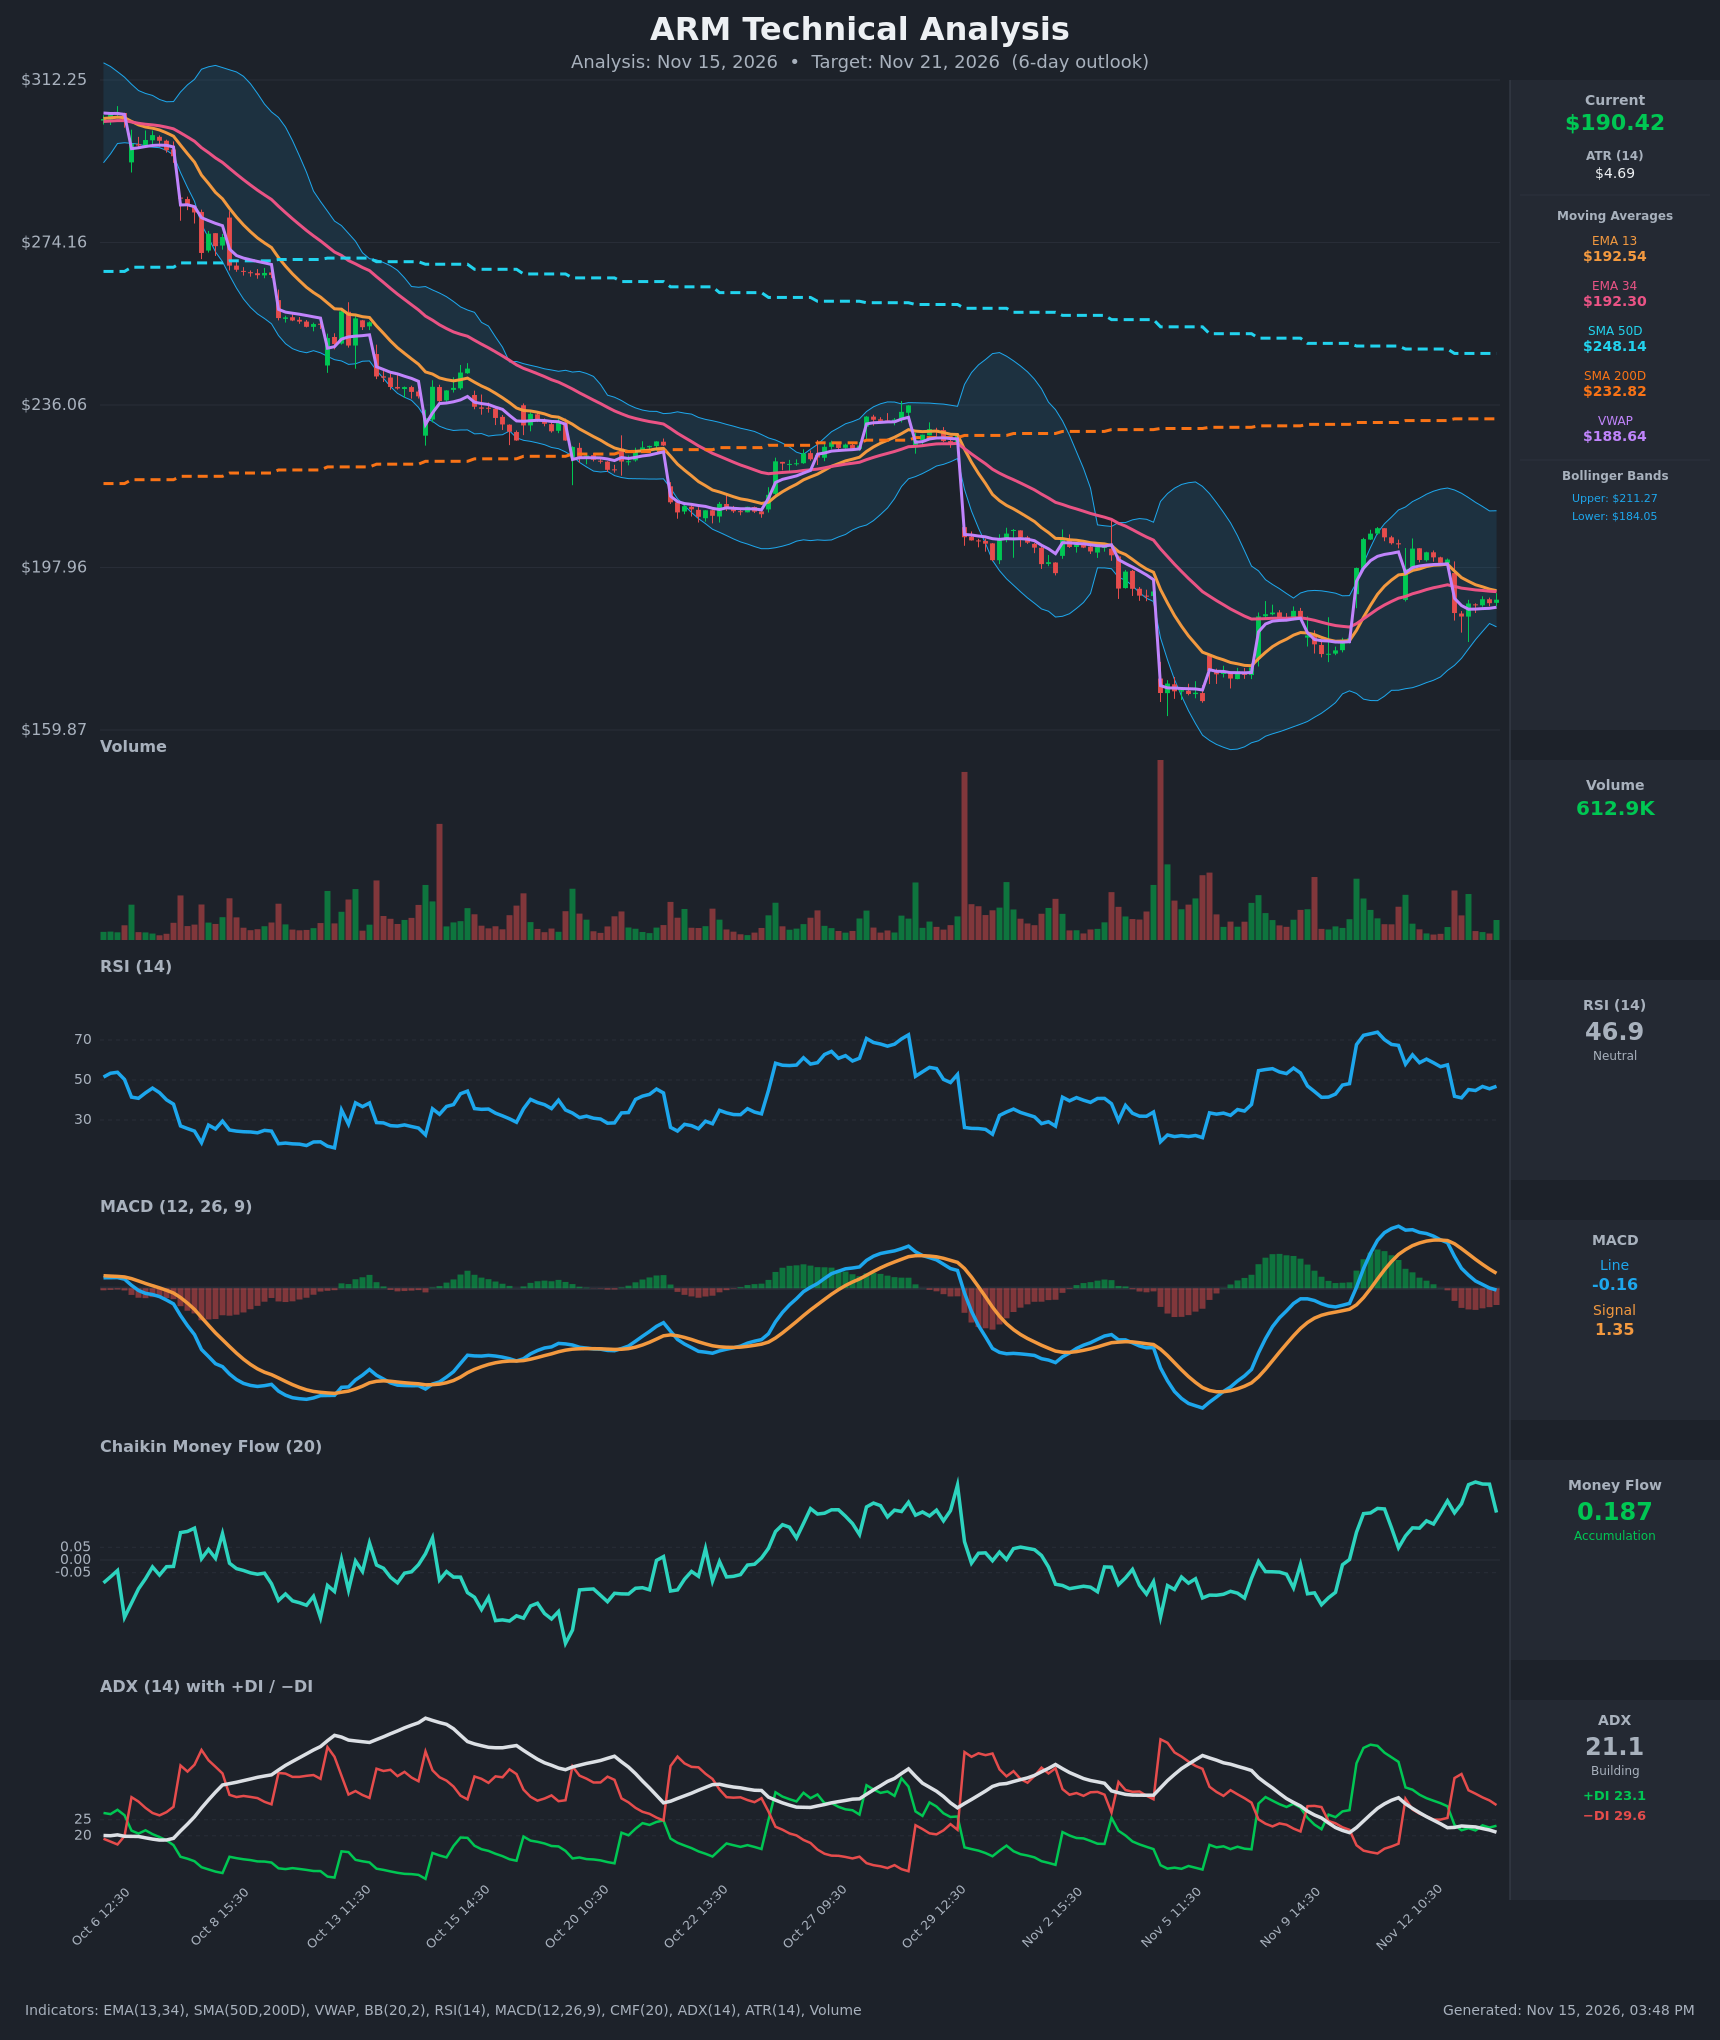
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the week can go
If ARM pushes above the call wall ($225): Getting there means clearing max pain ($205), the 20-day average ($205.53), the upper rail ($213.26) and the $220 gamma strike first. That is an 18% rally that would land well outside what options price. Above $225, positioning thins out until the 200-day average near $232.82. In a negative-gamma regime, a squeeze through stacked call open interest can feed on itself.
If ARM drifts between the walls: This is the base case. The whole chain's heaviest gamma sits at $190 and $200, which tends to keep price rotating inside that band. Max pain at $205 sits above spot, so expiring November 20 open interest exerts its pull upward rather than down. The technical model's $186.50 target sits just beneath this band.
If ARM breaks below the put wall ($150): This would require losing the $167.80 lower rail and the $163.13 swing support first. Below $150, open interest thins toward the early-2026 lows. One rough estimate places the gamma flip near $115, so dealer hedging may stay in its amplifying mode all the way down rather than cushioning a slide.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 13, 2026. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
Because premium is running thin versus delivered movement, the two debit structures lead and the credit structure comes last with a warning attached.
If you lean bearish: Nov 20 $185/$175 put debit spread
- Trade: Buy the Nov 20 $185 put, sell the Nov 20 $175 put. You pay a debit and profit if ARM falls toward or below $175.
- Debit: $3.23 ($323 per spread) · Max profit: $677 · Max loss: $323 · Break-even: $181.78
- Why it fits: Premium is thin, so buying options is the cheaper side right now. The spread targets the technical model's $183–$184 support zone. Puts are still priced over calls, and selling the $175 put offsets part of that cost.
- Makes sense only if: ARM closes below the $186.47 post-gap low. Don't front-run the break.
- Invalidated if: ARM closes above $193.
- Managing it: Take profits around 50–60% of max value. This is a short-term trade against a longer downtrend that just bounced hard, so don't overstay. Exit regardless by the November 19 close.
- Liquidity note: The $185 puts were quoted 20¢ wide ($6.45/$6.65) and the $175 puts 15¢ wide ($3.25/$3.40). Fills should be clean.
- Analyze this position →
If you lean bullish: Nov 20 $195/$205 call debit spread
- Trade: Buy the Nov 20 $195 call, sell the Nov 20 $205 call. You pay a debit and profit if ARM rallies toward $205.
- Debit: $3.30 ($330) · Max profit: $670 · Max loss: $330 · Break-even: $198.30
- Why it fits: Max pain for November 20 sits at $205, puts are being unwound quickly, and Friday's heaviest flow was near-dated calls at $192.50 and $197.50. The short leg sits right on max pain and the 20-day average.
- Makes sense only if: ARM reclaims the $192.54 moving-average cluster, which is the technical bounce trigger.
- Invalidated if: ARM closes below $186.47.
- Managing it: Close near 50% of max profit. A rebound fighting a two-month downtrend can fade quickly, so book gains early. Exit by the November 19 close.
- Liquidity note: The $195 calls were quoted 25¢ wide ($6.90/$7.15) and the $205 calls 15¢ wide ($3.65/$3.80).
- Analyze this position →
If you expect the range to hold: Nov 20 $160/$170 – $215/$225 iron condor
- Trade: Sell the $170/$160 put spread and the $215/$225 call spread, all Nov 20. You collect a credit and keep it if ARM stays between the short strikes.
- Credit: $2.27 ($226.50) · Max profit: $226.50 · Max loss: $773.50 · Break-evens: $167.74 and $217.27
- Why it fits: The short strikes sit roughly at the expected-move rails. The long call leg is the November 20 call wall, so the condor is built inside this expiration's own positioning.
- Health warning: You're selling premium that hasn't been rich lately. ARM's delivered movement has been running above what these options charge.
- Makes sense only if: Realized movement cools noticeably from its recent pace.
- Invalidated if: ARM closes below $167.80 or above $213.26.
- Managing it: Close at about 50% of the credit. If either short strike is touched on a close, exit rather than hope — in a negative-gamma regime, breaks tend to extend.
- Liquidity note: The $170 puts were quoted 5¢ wide, the $160 puts 3¢, the $215 calls 6¢ and the $225 calls 3¢. These are tight, liquid strikes.
- Analyze this position →
If none of these: no trade
Standing aside is a strong option this week:
- No directional edge. The positioning read is balanced, the technical lean is mild, and both debit spreads depend on a trigger that may never fire.
- Selling premium has been a losing proposition. The only non-directional structure collects premium that has recently been too thin to cover ARM's actual swings.
- Gap risk is severe. ARM has gapped 5–10% several times in two weeks.
If you can't watch the position daily, or you aren't comfortable losing the full debit or max loss on an overnight gap, no trade is the disciplined choice.
6 · Quick FAQ
What is ARM's expected move this week? About ±$22.73 (±11.93%) into the November 20 expiration, based on straddle pricing as of November 13, 2026. That implies a $167.80–$213.26 range.
Is ARM expected to go up or down over the next week? Options positioning as of November 13 leans neutral. Put protection is being unwound quickly, but puts still cost more than ARM's norm. That's a read of what traders have done, not a forecast. The actionable map is the $167.80–$213.26 range and the $150/$225 November 20 walls.
Are ARM options expensive right now? Not by the measure that matters most.
- IV rank of 49.7/100 puts option prices mid-range for the past year.
- Options are running about 22 vol points below the movement ARM has actually delivered, thinner than roughly four-fifths of this stock's recent readings.
That favors buying defined-risk premium over selling it.
Where is ARM's biggest options support and resistance? For November 20, the put wall is $150 and the call wall is $225. Across all expirations, open interest clusters much tighter, at $190 (puts) and $200 (calls).
What invalidates this week's read? A close below $167.80, the lower edge of the implied range.
Methodology & disclosures. Data: end-of-day options-chain snapshot for ARM, 2026-11-13, generated 2026-11-15T15:48:30.426Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.