BAC Options Are Pricing a $1.96 Move Into September 18 — And Premium Is the Richest It's Been All Quarter
Bank of America's options market implies a $60.73–$64.65 range into the September 18 expiration, with option prices running about 7 vol points above what the stock has actually delivered. Here's the positioning map, the levels that matter, and three defined-risk ways to trade it.

The options market implies a $60.73–$64.65 range into the September 18 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Sunday, September 13, 2026 · Data as of Friday, September 11, 2026 close
Explore the live BAC options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bearish tilt |
| Spot (Sept 11 close) | $62.69 |
| Options-implied range (into Sept 18) | $60.73 – $64.65 (±3.13%, or ±$1.96) |
| Major support | $50.00 — the Sept 18 put wall (the whole chain's heaviest put strike sits at $60.00) |
| Major resistance | $65.00 — the Sept 18 call wall |
| Max pain (Sept 18) | $60.00 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; pivot estimate ≈ $65.00 |
| Volatility condition | Rising on the week (−2.4% on the day, +12.5% over five sessions) — IV rank 21/100 · premium rich: options priced about 7.1 vol points above delivered movement |
| Technical check | Mixed (2-day model bearish, $62.35; 4-day model bullish, $63.10) |
| Best-fitting strategy | Short call spread — sell the Sept 18 $63 call, buy the $65 call |
| Analysis invalidated if | BAC closes above $63.55 |
1 · What matters today
Bank of America closed Friday, September 11 at $62.69, and the options market is pricing a move of about $1.96 in either direction — a $60.73 to $64.65 band — into the September 18 expiration. That figure comes from what straddles cost: it is the move the options market is pricing in, not a forecast.
Our read of the flow lands neutral with a mild bearish tilt. Puts have been quietly building in open interest, downside protection is priced a little richer than this name's own norm, and the front-dated sentiment read flipped negative on Friday after a week of call-friendly prints. Nothing in the data is dramatic — the signals disagree with each other more than they agree.
One thing is unambiguous: option prices are running about 7 vol points above the movement BAC has actually delivered, the richest that gap has been in months. That favors collecting premium over paying for it. The level that changes the picture is $63.55 — a close above it and the bearish tilt is gone.
2 · What the options market is pricing
What changed this week
Price barely moved: BAC is down 0.52% over the past five sessions and down 2.21% over the past twenty. Volatility did move. At-the-money implied volatility — the market's estimate of how much BAC will move, baked into option prices — sits at 22.88%, up 12.5% over five sessions and running about 10% above its own 30-day average of 20.8%, even after slipping 2.4% on Friday itself.
The positioning drifted the same way. The put/call open-interest ratio — how many put contracts are held open for every call — went from 0.95 to 1.03 over five sessions, against a 14-day average of 1.00: a steady, unspectacular build of downside contracts. Friday's put/call volume ratio was 0.64, still call-tilted in absolute terms, but heavier on puts than the 0.49 seven-day average. Total option volume ran at 0.83× its 20-day norm — a quiet tape, not a panic.
The single biggest open-interest change among still-live contracts was a build of 2,095 contracts in the December 18 $65 puts, taking that strike to 3,861 open — long-dated protection struck above the current price, which is hedging behaviour rather than a directional bet on this week. Into Friday's September 11 expiration, by contrast, the $63 calls shed 1,383 contracts of open interest on 12,135 contracts of volume as they settled worthless; that is history, not a live level.
The short- and long-term trend reads all come back flat: price is up 7.4% over the past two-and-a-half months but down 2.2% over the past month, with the momentum reads neutral across every window. There's no trend to lean on here — which is exactly why the range and the levels matter more than the direction this week.
Expected move
Into the September 18 expiration, the chain prices a 1σ move of ±3.13%, or ±$1.96 around $62.69 — a $60.73 to $64.65 range. That is derived from what at-the-money straddles cost; roughly two-thirds of outcomes historically land inside a band like that, and a third do not.
| Expiration | Implied move | Range around $62.69 |
|---|---|---|
| September 18 (7 DTE) | ±3.13% | $60.73 – $64.65 |
| September 25 (14 DTE) | ±4.19% | $60.06 – $65.32 |
| October 2 (21 DTE) | ±5.16% | $59.46 – $65.93 |
| October 9 (28 DTE) | ±6.04% | $58.90 – $66.48 |
The rungs step up smoothly — no kink, no hump, no single date the chain is bracing for. That is the profile of a market pricing ordinary time decay rather than a scheduled event inside the next month.
Volatility
IV rank is 21/100: today's implied volatility is cheaper than roughly 79% of the past year's readings, and the percentile measure agrees at 25. Front-month term structure — the comparison of option prices across expiration dates — is unavailable today, an artifact of Friday being an expiry day rather than missing data. Against its longer averages, ATM IV at 22.88% sits above the 30-day mean (20.8%) but below the 90-day mean (23.8%).
Underneath, the stock has gone quiet. Realized volatility over the past 20 days is 15.79%, unusually low compared against BAC's own recent history, and the ratio of the past week's movement to the past month's sits at 0.44 — the stock has been moving at well under half its own monthly pace, an unusually depressed reading for this name.
Premium rich or cheap: the gap between what options are priced for and what BAC has actually delivered — the volatility risk premium — is about 7.1 vol points in favour of the seller, and that gap sits richer than roughly 89% of this stock's own readings over the past three months. When it's positive, option sellers have been collecting more than realized movement cost them. The path matters too: that gap has roughly doubled since late August (it was near 2.8 points on August 28), driven by implied volatility firming while realized movement kept fading — no sign flip, just a widening. The combination — a modest IV rank of 21 but an 89th-percentile premium over delivered movement — favours collecting premium this week rather than owning it, and is the reason the credit structures lead Section 5.
Skew and sentiment
Puts and calls the same distance from the stock price don't cost the same here. The 25-delta skew — 25-delta put implied volatility minus the equivalent call — is running 3.0 vol points, against a 60-day median of 2.1 points and a seven-day average of 2.6. Concretely: the 25-delta put prices at 24.3% implied volatility versus 21.3% for the matching call. Traders are paying up for downside protection a little more than they normally do for this name, though the stretch is mild, not extreme.
Sentiment across the curve is genuinely split — the overall read is "mixed." The 0–7 day bucket scored −26 on Friday, driven entirely by open interest: call contracts in that window fell by 2,073 while puts added 1,151. That is a sharp turn — the same bucket printed +42 and +51 in the two prior sessions, and its seven-day average is a flat 0. Step out and the tone reverses: the 7–30 day bucket reads +8 and the 30–60 day bucket +43, both supported by call-side flow and call-side risk reversals richer than their own baselines. In plain terms, short-dated positioning got defensive on Friday while the month-plus tenors stayed constructive.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $65.23 | Price sits 3.89% below it; range position 87/100 |
| Call wall (Sept 18) & gamma pivot estimate | $65.00 | 58,674 calls open at this strike for the target expiration — the heaviest call pile, and the chain's single largest gamma strike overall; one rough estimate also places the dealer-hedging pivot here |
| Top of implied range | $64.65 | Upper rail of the ±$1.96 move priced into September 18 |
| Swing resistance | $63.55 | Heuristic swing-pivot cluster; the kill switch for this week's read |
| Spot | $62.69 | Friday's close, and the anchor for every range figure above |
| 20-day moving average | $62.62 | Price is 0.11% above it — effectively pinned to it |
| Swing support | $62.56 | Nearest price-structure floor |
| $62.50 strike | $62.50 | Second-heaviest gamma strike in the chain (49,795 calls, 33,506 puts open) — a magnet right under spot |
| 50-day moving average | $62.00 | Price is 1.11% above it; both technical models name it as support |
| Swing support | $60.95 | Next structural shelf below |
| Bottom of implied range | $60.73 | Lower rail of the September 18 expected move |
| Max pain (Sept 18) & chain's heaviest put strike | $60.00 | The price at which the most option value expires worthless for this expiration; also 98,286 puts open across all expirations here |
| Put wall (Sept 18) | $50.00 | 49,263 puts open — the biggest put pile for the target expiration, but far out of reach this week; it is legacy crash protection, not a live floor |
| 200-day moving average | $55.09 | 13.79% below spot — context only |
Note the disagreement worth flagging: the September 18 expiration's own put wall sits at $50.00, while the whole chain's heaviest put strike is $60.00. For a four-day window, treat $60.00 — which is also this expiration's max pain — as the level with gravity, and $50.00 as a marker of where long-dated insurance is parked.
Positioning and unusual flow
The dealer-gamma read is an estimate, not observed inventory: it comes back positive for both the whole chain and the September 18 expiration specifically, meaning market makers' hedging in this regime tends to dampen moves rather than amplify them. The same estimate places the pivot at $65.00 — the call wall — with spot sitting about 3.7% underneath it, modestly further below that pivot than has been typical for BAC lately. Read both numbers loosely.
Three flow items stood out among still-tradeable contracts:
- December 18 $67.50 puts — 1,910 contracts traded against just 218 open, nearly nine times the existing position, and about $1.18 million of premium changing hands. An in-the-money put that size, this far out, reads as structural hedging or a synthetic position, not a bet on next week.
- September 18 $61 puts — 3,312 contracts on 2,127 open (1.6× turnover), with open interest up 216. This is the target expiration's most-churned downside strike and sits right at the lower edge of the practical range.
- September 18 $62.50 calls — 4,063 contracts traded, $367,702 of premium, open interest up 516 to 11,930, and the tightest quoted market in the expiration. Right-at-the-money call interest that heavy is one reason $62.50 behaves like a magnet.
3 · Technical check
Two chart-model reads cover this window, and they disagree with each other — which is its own information.
The 2-day model (target date September 16) is bearish, projecting $62.35 with a range of $61.85 to $63.15. It cites a fresh EMA7/EMA21 bearish crossover, a MACD histogram that has been negative and widening, and a rising ADX at 23.2 with −DI above +DI. Its dominant scenario is a range breakdown below $62.60, invalidated by a reclaim and hold above $62.90. That read confirms our bearish tilt, and its whole projected band sits comfortably inside the options-implied $60.73–$64.65.
The 4-day model (target date September 18) is bullish, projecting $63.10 with a range of $61.55 to $64.20 — ADX at 27.2 with +DI dominant, a bullish MACD crossover, and a flag-style consolidation above rising moving averages. It diverges from the options read, though it carries its own caution: money-flow has dropped sharply into distribution territory while price has held, which the model itself flags as a bearish divergence. Both models name $62.00 as support and roughly $63.04–$63.05 as resistance.
Model vs. Market: The options market implies $60.73–$64.65 into September 18; the 4-day technical model targets $63.10, and the 2-day model targets $62.35. Both projections fit inside what options are pricing, so the disagreement is about direction within the range, not about magnitude — the range is the honest trade, and the $63.55 area is where the argument gets settled.
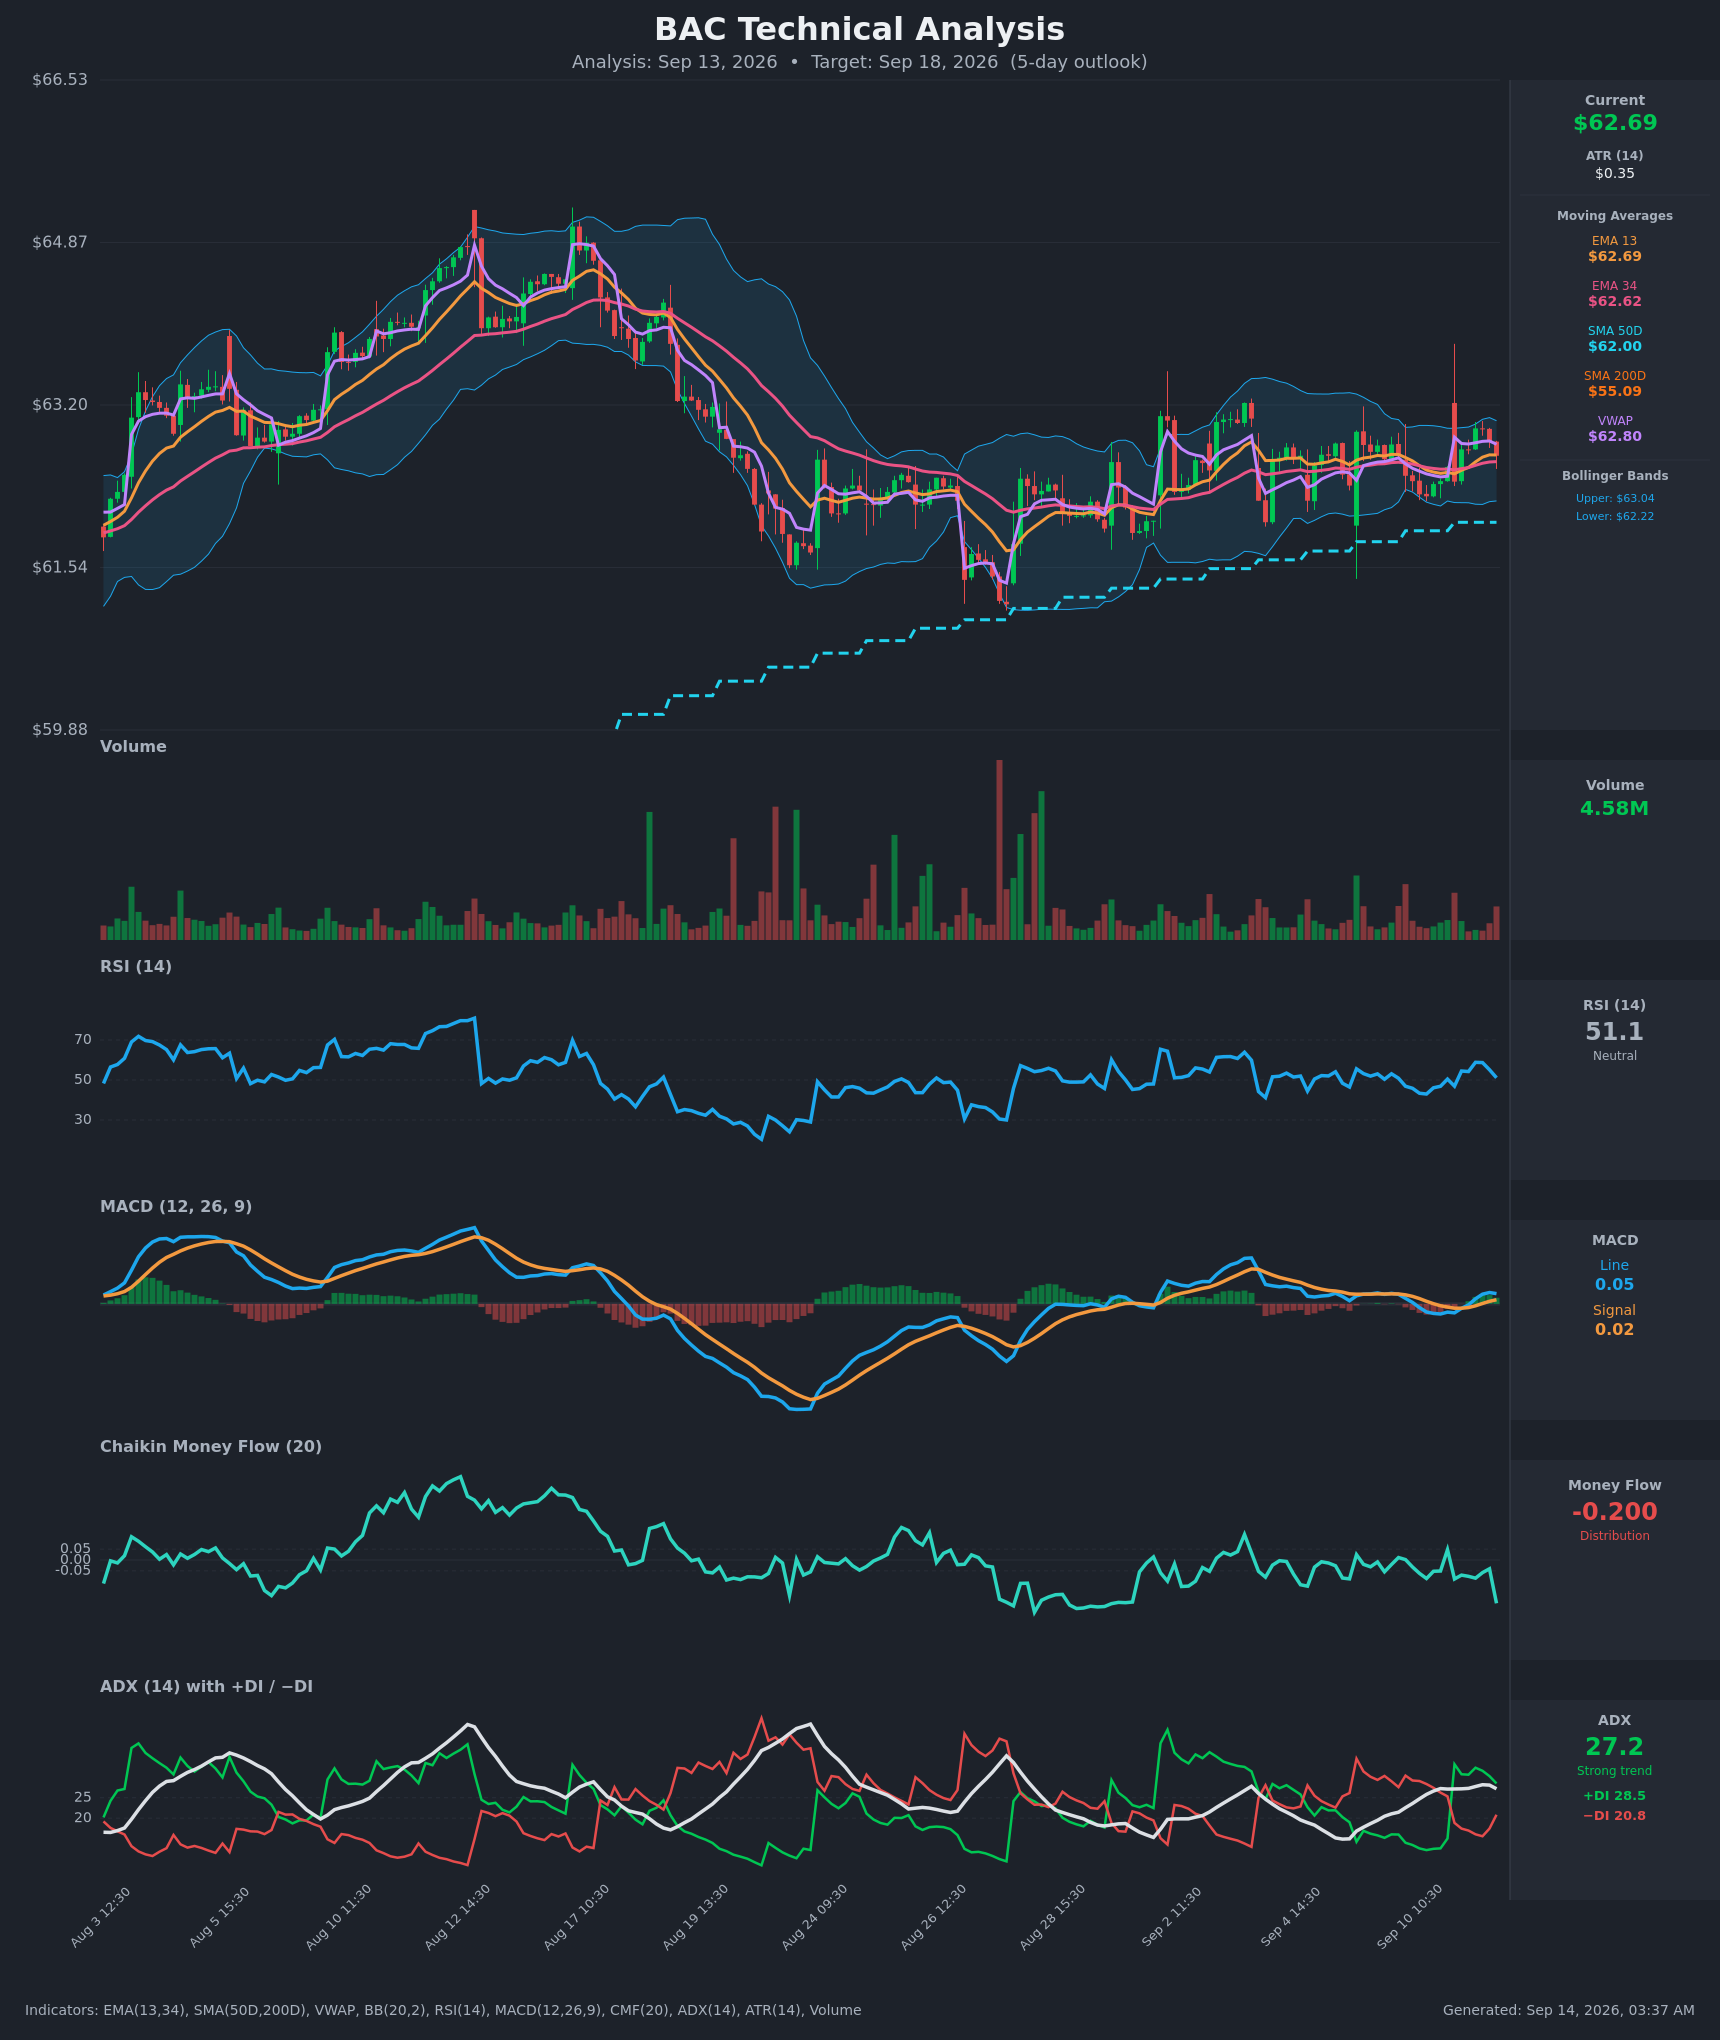
Net effect on strike selection: the split reads argued against pushing the short call strike too close to spot, and the shared $63.04–$63.55 resistance zone is where the featured spread's break-even lands.
Full technical write-ups: 2-day report → · 4-day report →
4 · Three ways the next four days can go
If BAC pushes above the call wall ($65.00): that strike carries 58,674 open calls for September 18 and is the chain's single largest gamma concentration. The heaviest call open interest overhead tends to slow rallies as it is defended and hedged; a clean break through it would leave thinner positioning until the 52-week high at $65.23. It would also take price above the estimated hedging pivot, where the mechanical dampening the estimate describes stops applying.
If BAC drifts between the levels: this is the base case the positioning supports. Max pain for September 18 sits at $60.00, $2.69 below spot — a downward pull, but a weak one over four days — while the $62.50 strike, second-heaviest by gamma in the whole chain, sits right under price and the 20-day average is at $62.62. With the gamma estimate reading positive, hedging flows in this regime tend to compress moves rather than extend them. A grind in the $62.00–$63.55 pocket is the path of least resistance.
If BAC breaks lower: the September 18 put wall at $50.00 is too far away to function as this week's floor, so the operative markers are the 50-day average at $62.00, the swing shelf at $60.95, the implied-range floor at $60.73, and the $60.00 max-pain and heaviest-put-strike cluster. Spot sits about 3.7% below the estimated gamma pivot at $65.00 — on the fragile side of that estimate — so a decisive break of $62.00 with volume is the branch where the dampening story stops being reassuring.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-09-11. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bearish (the featured structure): short call spread
- Trade: Sell the September 18 $63 call, buy the September 18 $65 call
- Credit: $0.56 ($0.665 − $0.105) · Max profit: $56 per spread · Max loss: $144 · Break-even: $63.56
- Why it fits: the long strike sits exactly at the $65.00 call wall, the break-even lands on the $63.55 swing-resistance shelf, and you are selling into an 89th-percentile premium over delivered movement with realized volatility unusually depressed for this name. It also expresses the mild bearish tilt without needing a decline — flat is a winner.
- Makes sense only if: you believe the $63.04–$63.55 resistance band holds for four sessions.
- Invalidated if: BAC closes above $63.55.
- Managing it: take profit at roughly 50% of the credit; with the short- and long-horizon trend reads flat and the 4-day chart model leaning the other way, don't hold for the last few cents — close by the September 16 checkpoint if BAC is trading through $63.
- Liquidity note: the $63 calls quoted 7¢ wide ($0.63/$0.70) on 2,671 contracts of volume and the $65 calls 3¢ wide on 4,330 — tight in absolute terms, but wide relative to these marks, so work limit orders at the mid rather than taking the offer.
- Analyze this position →
If you expect the range to hold: iron condor
- Trade: Sell the September 18 $61 put / buy the $60 put, and sell the $64 call / buy the $65 call
- Credit: $0.30 · Max profit: $30 · Max loss: $70 · Break-evens: $60.70 and $64.30
- Why it fits: you collect on both sides of a stock that has been moving at less than half its own monthly pace while its options are priced at an 89th-percentile premium. The short strikes bracket the practical map — $61 sits above the $60.00 max-pain/heaviest-put cluster, $64 sits under the $65.00 call wall — and both break-evens sit essentially at the edges of the implied $60.73–$64.65 range.
- Makes sense only if: you're comfortable that a $2 move in either direction inside four sessions is the tail, not the base case. Reminder on mechanics: you collect the credit up front and keep all of it only if BAC finishes between $61 and $64.
- Invalidated if: BAC closes outside $60.70–$64.30, at which point one side is already past break-even.
- Managing it: close at ~50% of max credit; exit the whole structure by September 17 regardless, because the last day of a four-strike short-gamma position is where a single gap does the damage.
- Liquidity note: the $61 puts traded 4¢ wide ($0.22/$0.26) on 3,312 contracts, the $60 puts 2¢ wide on 1,220, the $64 calls 5¢ wide on 3,777 and the $65 calls 3¢ wide on 4,330. Absolute spreads are small but they total roughly 14¢ against a 30¢ credit — leg in patiently or the fill eats half the edge.
- Analyze this position →
If you lean bullish: short put spread
- Trade: Sell the September 18 $62 put, buy the September 18 $61 put
- Credit: $0.25 ($0.49 − $0.24) · Max profit: $25 · Max loss: $75 · Break-even: $61.75
- Why it fits: it sides with the 4-day technical model ($63.10 target), the constructive 7–30 day and 30–60 day sentiment buckets, and the positive dealer-gamma estimate; the break-even at $61.75 sits below the 50-day average at $62.00 and above the $60.95 swing shelf. You're collecting a rich premium to be right slowly.
- Makes sense only if: you read Friday's front-dated put building as hedging into an intact range rather than the start of a slide — and you accept that this trade fights both max pain at $60.00 and the 2-day model's $62.35 target.
- Invalidated if: BAC closes below $62.00.
- Managing it: close at ~50% of max credit, or immediately if BAC closes through $62.00 — with the momentum reads flat there is no trend to bail you out, so exit rather than hope.
- Liquidity note: the $62 puts traded 6¢ wide ($0.46/$0.52) on 3,197 contracts and the $61 puts 4¢ wide on 3,312 — the two busiest put strikes in the expiration, so fills are workable at the mid.
- Analyze this position →
If none of these: no trade
Premium being rich is a real edge here — that 89th-percentile gap is not earnings-inflated, because there's no scheduled report inside this ladder to explain it. But rich is not the same as large. A four-day $1-wide credit spread on a $62 stock pays $25 to $56 against $70 to $144 of risk, and two round-trips of a 4–7¢ bid-ask spread can consume a fifth of that credit before the trade has done anything. If you cannot get filled near the midpoint, the arithmetic that makes premium-selling attractive stops working, and standing aside genuinely beats selling. The other honest reason to pass: the two technical reads point opposite ways inside the same range, so any directional version of this trade is a coin flip dressed in a credit. Waiting for a resolution of the $62.00/$63.55 boundaries costs you nothing but four days of theta you were never guaranteed to collect.
6 · Quick FAQ
What is BAC's expected move into September 18? ±$1.96, or ±3.13%, around the $62.69 close — a $60.73 to $64.65 range, per the options market's straddle pricing as of September 11.
Is BAC expected to go up or down over the next four days? Options positioning as of September 11 leans mildly bearish — puts building in open interest, skew 0.9 vol points steeper than its own 60-day norm, and the front-dated sentiment bucket flipping negative — but that's a read of what traders have done, not a forecast. The actionable map is the $60.73–$64.65 range and the $60.00 / $65.00 levels.
Are BAC options expensive right now? Two lenses, two answers. IV rank of 21/100 says option prices are lower than 79% of the past year's readings. But relative to the movement BAC has actually delivered, they're running about 7.1 vol points rich — richer than roughly 89% of this stock's own recent readings. On a relative basis, this is a seller's market; on an absolute basis, the dollars per contract are small.
Where is BAC's biggest options support and resistance? For the September 18 expiration, the call wall is $65.00 (58,674 contracts open) and the put wall is $50.00 (49,263 contracts). Because $50.00 is far out of reach this week, the practical downside marker is the $60.00 max-pain strike, which is also the whole chain's heaviest put strike.
What invalidates this week's read? A close above $63.55.
Methodology & disclosures. Data: end-of-day options-chain snapshot for BAC, 2026-09-11, generated 2026-09-14T03:37:14.624Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.