IBM Options Are Pricing a $12.53 Move: Our Read Sees a Pin Between $240 and $265
The options market implies a $245.28–$270.34 range for IBM into the November 6 expiration. Steep put skew is meeting call-heavy flow, and estimated dealer hedging favors a pin over a breakout. Here is the level map and three defined-risk ways to trade it.
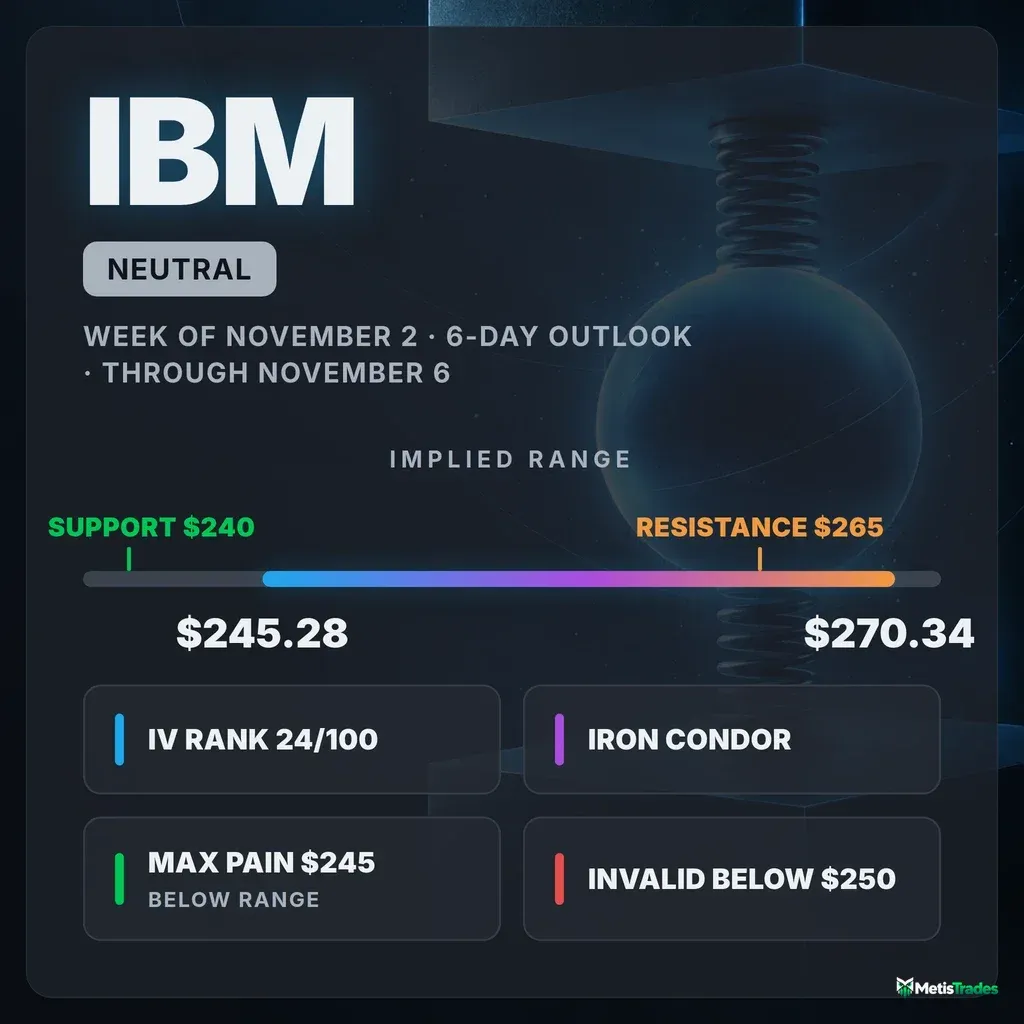
The options market implies a $245.28–$270.34 range into the November 6 expiration. Below: what is driving it, the level map, and three defined-risk ways to trade the next six days.
Published Saturday, October 31, 2026 · Data as of Friday, October 30, 2026 close
Explore the live IBM options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into Nov 6) | $245.28 – $270.34 (±4.86%, ±$12.53) |
| Major support | $240 (Nov 6 put wall) |
| Major resistance | $265 (Nov 6 call wall) |
| Max pain (Nov 6) | $245 |
| Dealer gamma regime (estimate) | Positive: hedging tends to dampen moves. Flip level ≈ $255 |
| Volatility condition | Falling. IV rank 23.68/100 · premium rich: options priced ~10 vol pts above delivered movement |
| Technical check | Mixed (bullish, 3-day and 6-day models; targets $259.50 / $259.80) |
| Best-fitting strategy | Iron condor (Nov 6 $235/$240 puts, $265/$270 calls), if you accept wide fills |
| Analysis invalidated if | IBM closes below $250 |
1 · What matters today
IBM closed Friday at $257.81. The options market is pricing a move of about $12.53 either way through the November 6 expiration, a $245.28–$270.34 range.
Our read is neutral. Traders keep buying short-dated calls, but they are also paying unusually steep prices for downside protection. Those two forces roughly cancel.
What tips the picture toward "range" is positioning. The biggest pile of call contracts for this expiration sits at $265, and the biggest pile of puts sits at $240. One rough estimate also says market makers are positioned to cushion moves rather than amplify them while IBM holds above about $255.
The level that changes the picture is $250. A close below it would push IBM through that cushion and its largest options node.
The chart-based models lean modestly bullish, but both targets sit comfortably inside the options range.
2 · What the options market is pricing
What changed this week
IBM gained 1.68% over the past five sessions. That caps a 15.8% run over the past 20 trading days, which carried the stock above all four of its major moving averages. The short- and long-term trend reads agree: bullish over the past month and the past two-plus months, flat over the past week. A very weak bearish momentum crossover printed on Friday, but it barely registers against that backdrop.
Option prices kept deflating. At-the-money implied volatility fell 4.6% over five days to 33.3%, far below its 30-day average of 42.9%. That is the tail end of the cool-down after IV spiked to roughly 67% on October 21.
Puts also thinned out relative to calls:
- Open interest (contracts currently held open): there are now 0.74 puts open for every call, versus a 7-day average of 0.79 and a 14-day average of 0.84.
- Volume: Friday's put/call volume ratio was 0.37, against a 7-day average of 0.43. Traders bought roughly 2.7 calls for every put.
The single biggest open-interest change was in the November 6 $265 calls, which added 687 contracts to reach 1,166. Into Friday's expiration, by contrast, the October 30 $260 puts shed 627 contracts. That is settled history now.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the November 6 expiration it is ±4.86%, or ±$12.53 around the $257.81 snapshot price.
| Expiration | Implied move | Range around $257.81 |
|---|---|---|
| Nov 6 | ±4.86% | $245.28 – $270.34 |
| Nov 13 | ±7.10% | $239.51 – $276.11 |
| Nov 20 | ±8.27% | $236.49 – $279.13 |
| Nov 27 | ±9.21% | $234.07 – $281.55 |
The ladder widens about the way time alone would predict, with one quirk. November 13 options carry slightly higher implied volatility (36.3%) than November 6 (35.1%), and almost all of that comes from the put side. The appetite for downside protection reaches past this week's expiration.
Volatility
Implied volatility (IV) is the market's estimate of how much IBM will move, baked into option prices. At 33.3% it sits well below both its 30-day average (42.9%) and its 90-day average (41.8%). It ticked up 2.2% on Friday but is down 8.3% over 30 sessions.
IV rank shows where today's IV sits versus the past year. At about 24/100, options are cheaper than roughly 76% of the past year's range, and IV is below about two-thirds of the past year's daily readings.
The front-month term-structure read, which compares option prices across expiration dates, is unavailable today because Friday was an expiry day. The roughly 60-day IV of 34.1% shows no stress at the back end.
For context, realized movement has been modestly calm by IBM's own standard. Its 20-day realized volatility of 23.1% runs somewhat below the stock's recent norm. "Below its norm" here means unusual for IBM, not versus the broader market.
Premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much IBM has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them. Today that gap is about 10 vol points: options are priced near 33% while the stock has delivered about 23%.
The VRP percentile places that gap at 76/100, richer than about three-quarters of this stock's own recent readings. Over the past week the gap edged back up from about 7 points.
So the two lenses split. IV rank says options are cheap versus the year. The premium gauge says they are rich versus what IBM is actually doing. That combination favors collecting premium over the next six days, as long as structures are defined-risk and sized for wide quotes.
Skew and sentiment
Skew means puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection.
IBM's 25-delta puts are priced at 35.8% IV versus 31.8% for comparable calls, a 4.0 vol-point premium. The stock's 60-day norm is −1.2 points, meaning calls are usually slightly richer. So puts are running about 5 points steeper than usual, which is stretched well beyond IBM's own recent history. Skew also steepened over the past five sessions while the stock rallied.
The put/call ratio measures put activity relative to calls; above 1 means puts dominate. That is the paradox here: volume is call-heavy at 0.37, noticeably more call-tilted than IBM's norm, while the price of protection keeps climbing.
Sentiment in short-dated options shows the same split:
- 0–7 day expirations: lean bullish (+29) on call open interest building.
- 7–30 day expirations: dead flat (−1), because rich put pricing offsets call-side flow.
- Overall: the regime reads "Mixed."
We read this as traders chasing the rally with short-dated calls while hedging the gains underneath. That is protection layered into an intact uptrend, not a bearish wager in its own right.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $332.46 | IBM is still 22% below it; far outside this window |
| Swing resistance | $311.80 | Only overhead price-structure level; well beyond reach |
| Upper implied range (Nov 6) | $270.34 | Top of the ±$12.53 expected move |
| Large-gamma strike | $270 | One of the five heaviest options nodes across the chain |
| Call wall (Nov 6) | $265 | Heaviest call open interest for this expiration; tends to slow rallies |
| Call wall (whole chain) | $260 | Heaviest call strike across all expirations (17,678 contracts) and the second-largest gamma node |
| Spot (Oct 30 close) | $257.81 | Reference price |
| Swing support | $256.30 | Nearest price-structure floor |
| Gamma flip (estimate) | $255 | Below this, one rough estimate says hedging accelerates selling instead of cushioning it |
| Swing support | $251.82 | Base of the late-October consolidation |
| Largest-gamma strike | $250 | Biggest options node in the chain; the article's invalidation level |
| 200-day moving average | $249.16 | Long-term trend line, 3.5% below spot |
| Max pain (Nov 6) | $245 | Price where the most option value would expire worthless |
| Lower implied range (Nov 6) | $245.28 | Bottom of the expected move |
| 100-day moving average | $241.63 | Intermediate trend line |
| Put wall (Nov 6) | $240 | Heaviest put open interest for this expiration, also a top gamma strike; swing support at $240.44 sits just above |
| 20-day moving average | $238.88 | Shows how far and fast the rally ran |
| 50-day moving average | $235.17 | Rising, but still below the 200-day |
| Put wall (whole chain) | $220 | Heaviest put strike across all expirations |
| 52-week low | $199.19 | Far below; context only |
Note that the November 6 walls ($265 / $240) differ from the whole chain's heaviest strikes ($260 / $220). For this six-day window, the expiration-specific walls are the ones that matter.
Max pain is the price where the most option value would expire worthless, and expirations sometimes gravitate toward it. For November 6 it sits at $245, about $12.81 below spot and right at the bottom edge of the implied range.
Positioning and unusual flow
Market makers hedge the options they've sold. In a positive-gamma regime, their hedging tends to dampen moves: selling into rallies and buying dips. One rough estimate puts IBM in that regime both across the whole chain and for the November 6 expiration alone. The estimated flip level is about $255, and spot sits roughly 1.1% above it, a typical distance for this name. That favors a pin over a breakout, but the cushion is thin.
Three trades stood out on Friday:
- Nov 6 $265 calls: 1,872 contracts traded, about $402,000 in premium, and open interest jumped from 479 to 1,166. That build is what created the call wall. Traders are reaching for upside, but they are also stacking open interest at a strike where hedging flows can slow a rally.
- Nov 6 $260 puts: 425 contracts traded against only 22 open, about $265,000 in premium. That is fresh short-dated protection struck just above spot, so this hedge pays on any slip.
- Jan 15 $255 puts: 959 contracts traded, about $1.35 million in premium, the largest dollar trade in the chain. That is longer-dated insurance sitting under the rally.
3 · Technical check
3-day model (target November 3): bullish. It targets $259.50, with a projected range of $254.30–$262.30. That target sits well inside the options-implied range, so the model agrees on magnitude but leans further upside than our neutral read.
The decisive inputs are strong money flow into the stock (Chaikin Money Flow at 0.295) against a weak trend-strength reading (ADX 18.3). In plain terms: buyers are in control, but the trend is grinding rather than accelerating. The model's dominant scenario is invalidated on a close below $255.90, almost exactly the gamma-flip estimate.
6-day model (target November 6): bullish. It targets $259.80, with a projected range of $253.00–$263.50. Its key levels are support at $255.90 and $253.46, and resistance at $259.27 and $262.00. Its dominant scenario is invalidated on a close below $254.50.
We classify both as Mixed: same general neighborhood, different lean. Notably, even the bullish case tops out below the $265 call wall. That supports placing the short call strikes there.
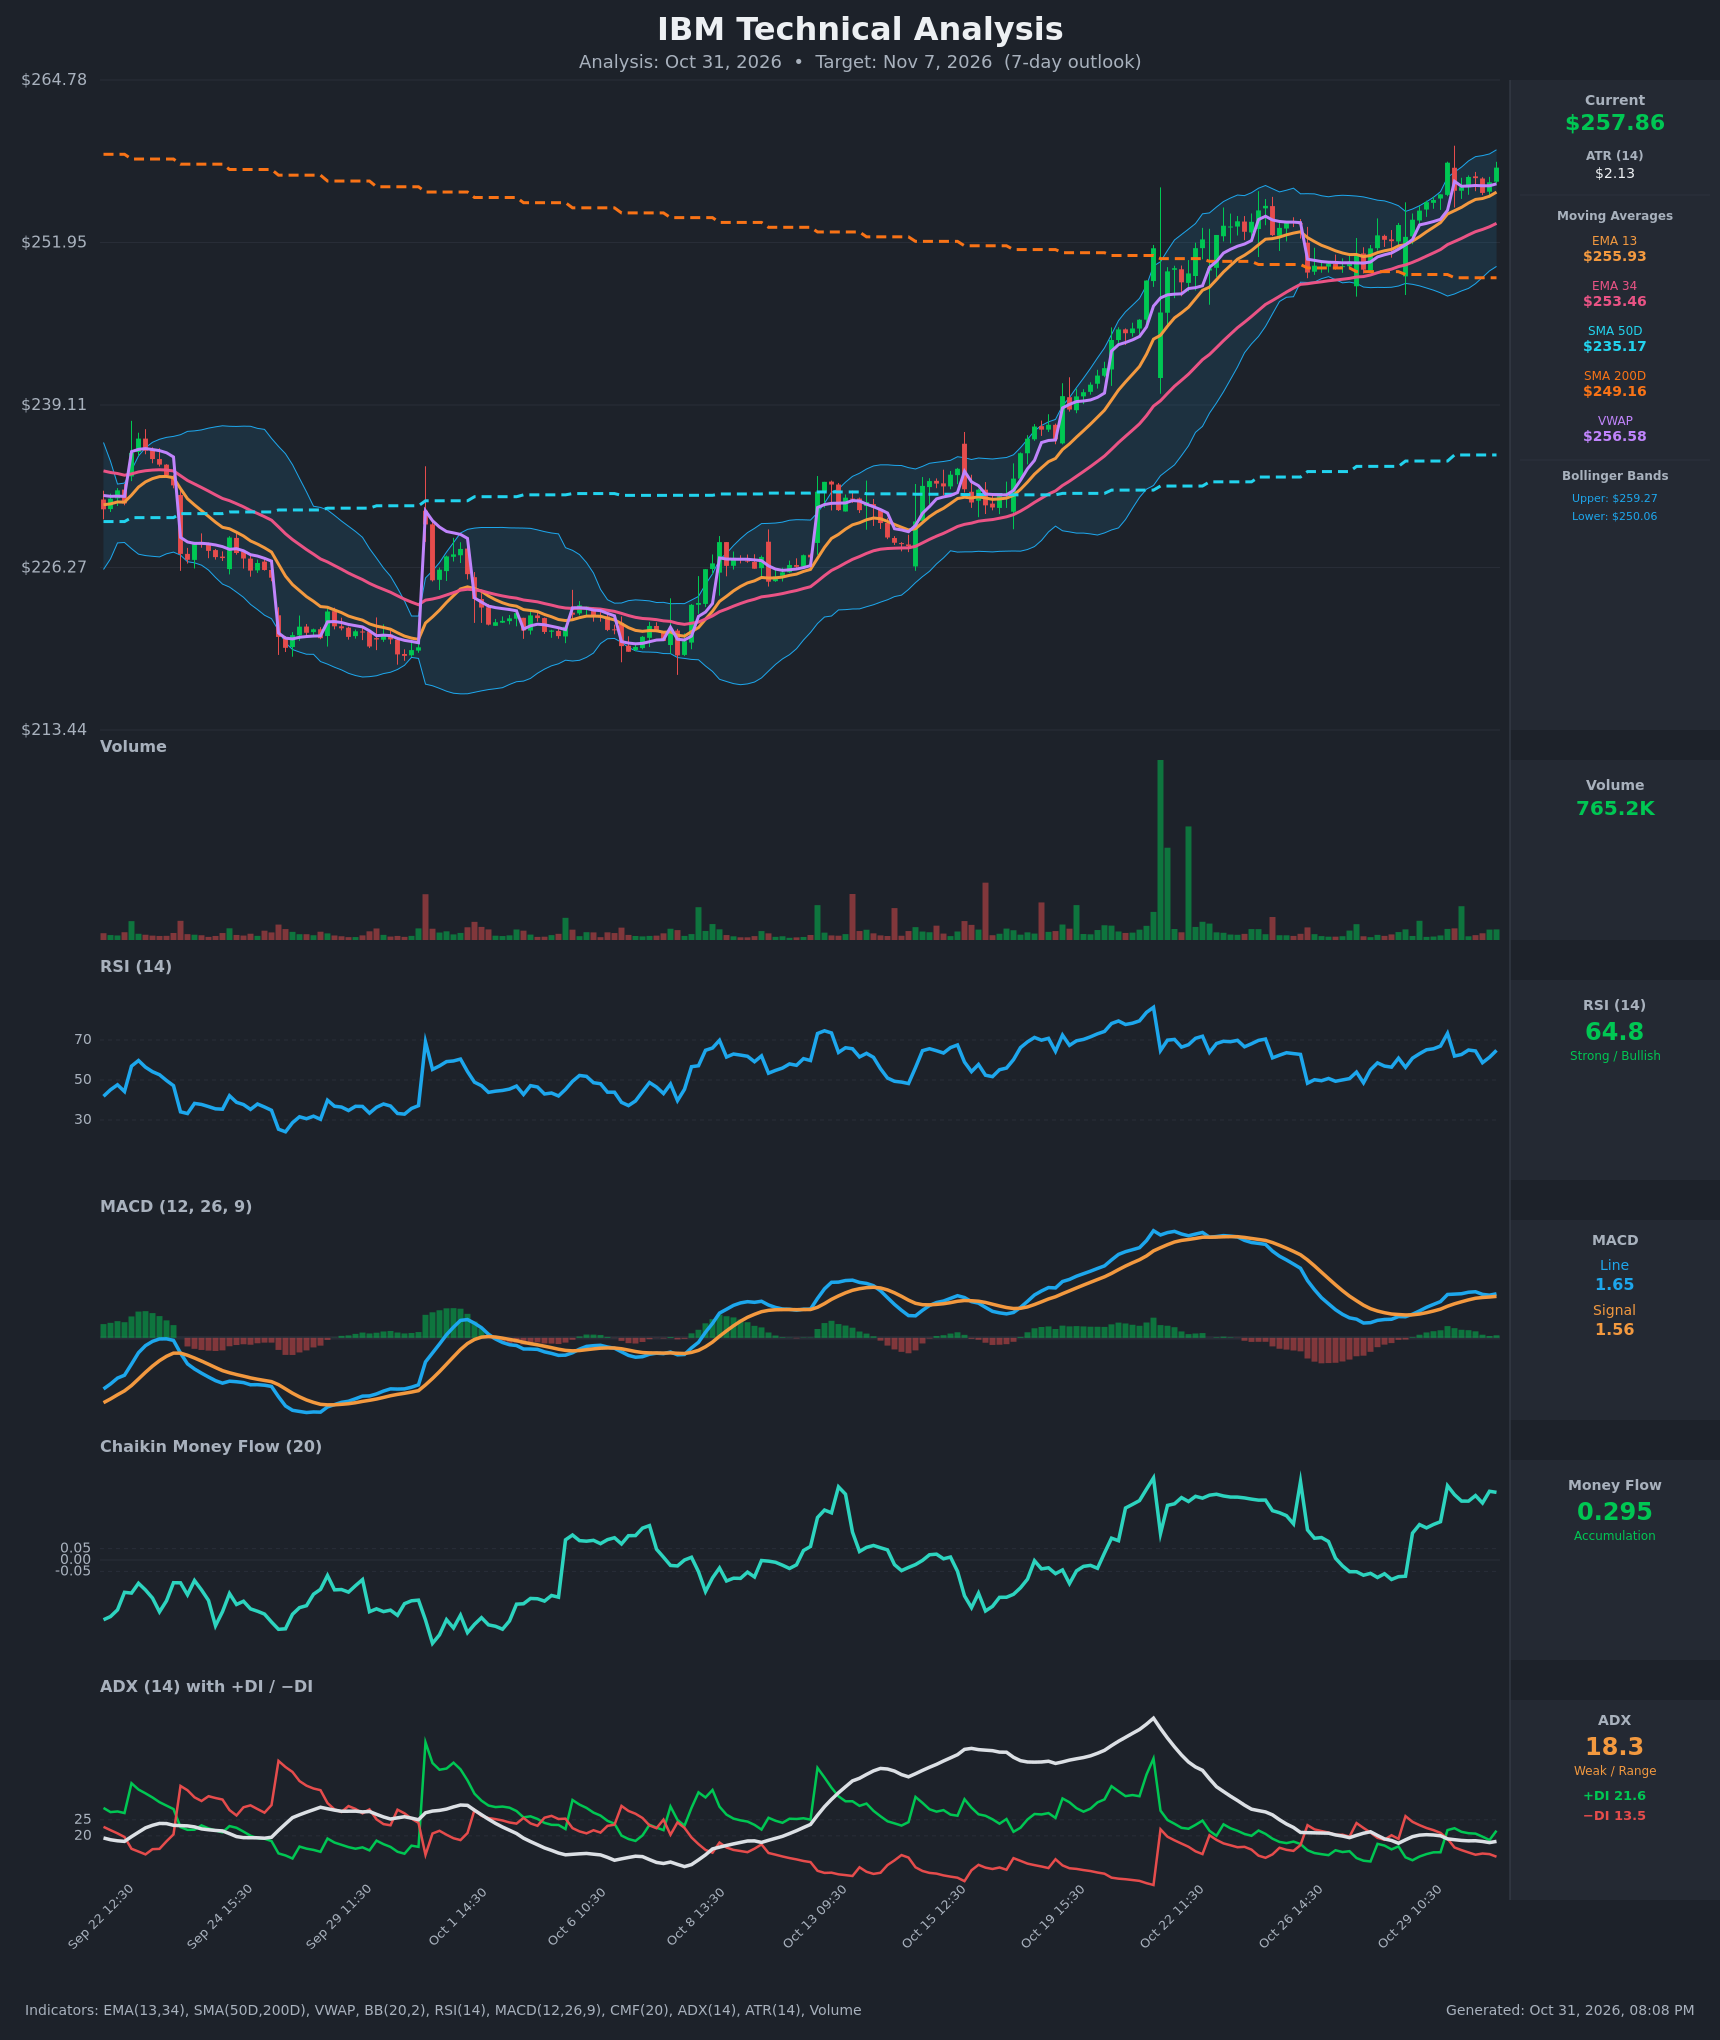
Model vs. Market: The options market implies $245.28–$270.34 into November 6; the 6-day technical model targets $259.80. The chart sees a slow grind higher. A drift to the $260 neighborhood fits both readings, and it would leave a range trade untouched.
Full technical write-ups: 3-day report → · 6-day report →
The technical read moved strike selection in one place: the iron condor's short call sits at $265, above both models' projected highs.
4 · Three ways the next six days can go
If IBM pushes above the call wall ($265): The heaviest call open interest for this expiration sits right there. In a positive-gamma setup, hedging flows tend to lean against a rally into that strike. A clean close through it would leave thinner positioning until the $270 gamma node and the $270.34 top of the implied range. That is the zone where the range read would be under real strain.
If IBM drifts between the walls: This is the pin case. Dealer hedging is estimated to cushion moves, and expiring open interest is spread between $240 and $265. Price tends to churn inside that band into November 6. Max pain at $245 sits below spot, so any late-week gravity points modestly lower rather than higher, toward the $250–$255 nodes.
If IBM breaks below the gamma flip (~$255) and then the $250 node: This is the acceleration case. Below the flip, one rough estimate says market-maker hedging amplifies selling rather than cushioning it. With puts already priced steeply, that is where protection buyers get paid. The path from there runs toward max pain at $245 and the $240 put wall.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 30, 2026. All structures are hypothetical. Verify live prices before trading; these will be stale by the open. Option premiums are rich relative to delivered movement right now, so the credit structures lead.
If you expect the range to hold: Iron condor
- Trade: Sell the Nov 6 $240/$235 put spread and the Nov 6 $265/$270 call spread. You collect a credit and win if IBM stays between the short strikes.
- Credit: $1.28 ($128 per condor) · Max profit: $128 · Max loss: $372 · Break-evens: $238.72 and $266.28
- Why it fits: The short strikes sit exactly on the November 6 put wall ($240) and call wall ($265), with estimated positive dealer gamma between them. You are selling premium that runs about 10 vol points above delivered movement, at the 76th percentile of IBM's recent readings.
- Makes sense only if: IBM holds above the ~$255 gamma flip estimate for most of the window.
- Invalidated if: IBM closes above $265 or below $240.
- Managing it: Close at about 50% of max credit. Exit regardless by the close on November 5 to avoid expiration-day pin risk. If either short strike is breached on a closing basis, close the whole position rather than hope.
- Liquidity note: The $265 calls traded 30¢ wide on heavy volume. The $270 calls were 26¢ wide, the $240 puts 20¢, and the $235 puts 5¢. Every leg is wider than 5% of its price, so work the order at mid and expect some slippage on a credit this small.
- Analyze this position →
If you lean bullish: Put credit spread
- Trade: Sell the Nov 6 $250/$245 put credit spread. You collect premium and win if IBM stays above $250 at expiration.
- Credit: $0.90 · Max profit: $90 · Max loss: $410 · Break-even: $249.10
- Why it fits: The short strike sits at the chain's largest gamma node, beneath swing support at $251.82 and just above the 200-day average at $249.16. You collect rich put premium, thanks to the steep skew, while the trend is still pointing up.
- Makes sense only if: The call-heavy flow keeps absorbing dips, with support at $255–$256.
- Invalidated if: IBM closes below $250.
- Managing it: Take profits at 50–60% of the credit. If IBM closes below $255 early in the window, consider cutting size, because max pain at $245 sits right at your long strike.
- Liquidity note: The $250 puts were 27¢ wide and the $245 puts 31¢. Fills at mid are not guaranteed.
- Analyze this position →
If you lean bearish: Put debit spread
- Trade: Buy the Nov 6 $255/$245 put debit spread. You pay up front and profit if IBM falls toward $245.
- Debit: $2.71 · Max profit: $729 · Max loss: $271 · Break-even: $252.29
- Why it fits: The long strike sits at the gamma flip estimate, where one rough estimate says hedging turns from cushion to accelerant. The spread targets max pain at $245. Selling the $245 put recovers part of the steep put premium you are paying for.
- Makes sense only if: IBM loses $255 on a closing basis. Steep skew alone is not a reason to own downside.
- Invalidated if: IBM closes above $260.
- Managing it: The multi-week trend is bullish and only the past week's momentum has flattened, so keep this one short-dated and quick. Take half off near $250 and exit the remainder by November 5.
- Liquidity note: The $255 puts traded 85¢ wide and the $245 puts 31¢. This is the widest structure here, so leg in patiently.
- Analyze this position →
If none of these: no trade
Premium is rich versus delivered movement, so standing aside needs a reason. Here it has one: execution. Nearly every November 6 leg trades at 10–40% of its own price in bid-ask width. On a $1.28 condor credit, giving up 20–30¢ per side at entry and exit can eat most of the edge the premium gauge advertises.
The cushion is also thin. Spot is only about 1% above the gamma flip estimate, and put buyers are clearly preparing for a slip. If you cannot get fills near mid, or you would rather not hold short gamma through a week where both sides are actively hedging, sitting out costs you nothing.
6 · Quick FAQ
What is IBM's expected move this week? About ±$12.53 (±4.86%) into the November 6 expiration, a $245.28–$270.34 range, per straddle pricing as of October 30.
Is IBM expected to go up or down over the next week? Options positioning as of October 30 reads neutral. Call buying and steep put hedging roughly offset each other, and estimated dealer hedging favors a pin. That is a read of what traders have done, not a forecast. The actionable map is the $245.28–$270.34 range, with support at $240 and resistance at $265.
Are IBM options expensive right now? Versus the past year, no: IV rank of about 24/100 means option prices are lower than roughly three-quarters of the year's range. Versus what IBM has actually been doing, yes: they run about 10 vol points above delivered movement, richer than 76% of this stock's own recent readings. That combination favors defined-risk premium selling, if fills cooperate.
Where is IBM's biggest options support and resistance? For November 6, the put wall is $240 and the call wall is $265. Across all expirations, the heaviest strikes are $220 (puts) and $260 (calls).
What invalidates this week's read? A close below $250.
Methodology & disclosures. Data: end-of-day options-chain snapshot for IBM, 2026-10-30, generated 2026-10-31T20:08:04.856Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.