INTC Options Are Pricing a $9.47 Swing Into Sep 25 — But the Positioning Read Is Leaning the Other Way From the Chart
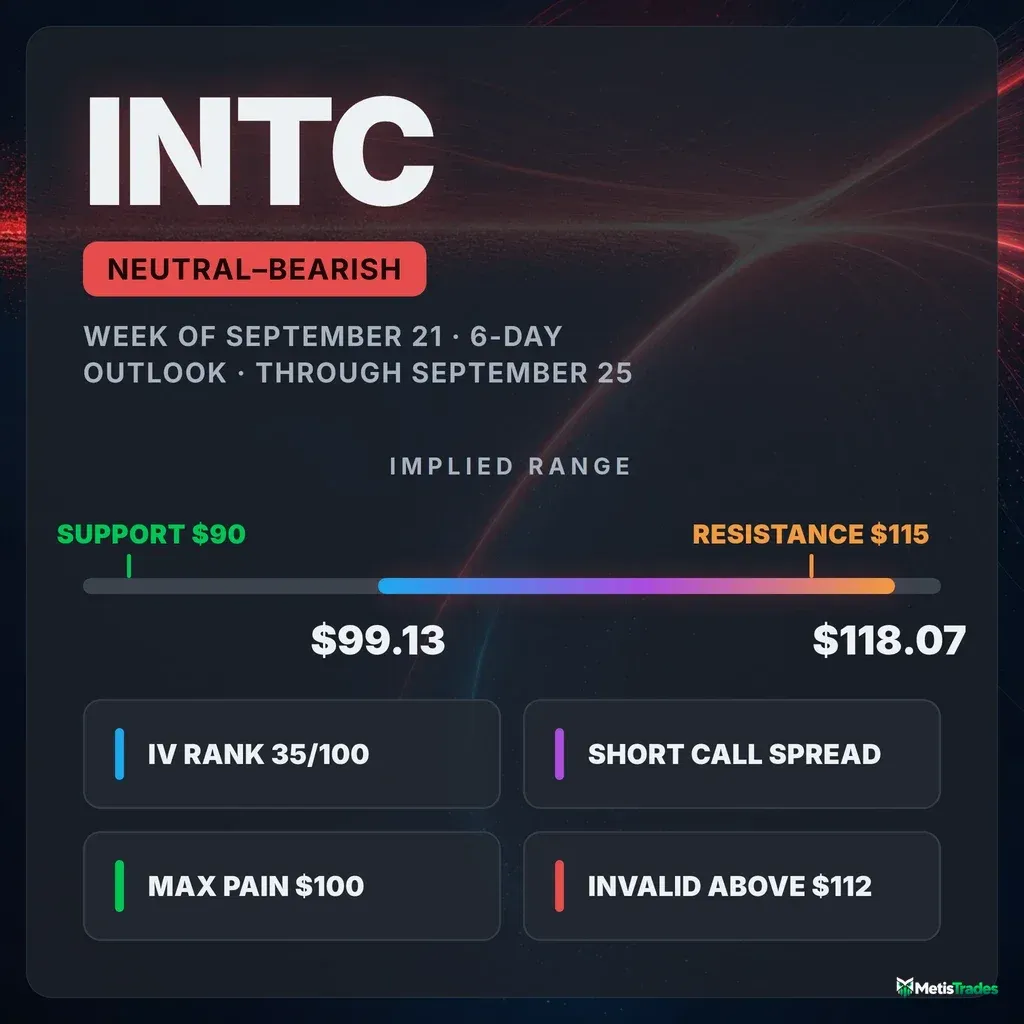
Intel's options market implies a $99.13–$118.07 range into the September 25 expiration, with the week's call wall parked at $115 and max pain down at $100. Our positioning read comes out neutral with a bearish tilt — against two bullish technical models — and premium is rich enough to favor selling it.
Listen to this analysis — prefer audio? This INTC outlook is also available as a podcast episode:
The options market implies a $99.13–$118.07 range into the September 25 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Saturday, September 19, 2026 · Data as of Friday, September 18, 2026 close
Explore the live INTC options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bearish tilt |
| Options-implied range (into Sep 25) | $99.13 – $118.07 (±8.72%, about ±$9.47) |
| Major support | $90.00 (put wall, Sep 25 expiration) |
| Major resistance | $115.00 (call wall, Sep 25 expiration) |
| Max pain (Sep 25) | $100.00 |
| Dealer gamma regime (estimate) | Positive — market-maker hedging tends to dampen moves; flip level ≈ $70 |
| Volatility condition | Easing from the summer highs — IV rank 35/100 · premium rich: options priced about 3.5 vol points above the movement INTC has actually delivered |
| Technical check | Diverges (bullish, 3-day and 6-day chart models) |
| Best-fitting strategy | Short call spread — sell the Sep 25 $115 call, buy the $118 |
| Analysis invalidated if | INTC closes above $112.00 |
1 · What matters today
Intel closed Friday, September 18 at $108.60 after a 5.5% five-day run and an 17.9% move over the past month. The options market is pricing roughly $9.47 up or down — a $99.13 to $118.07 band — into the September 25 expiration. That is an enormous implied swing for six days, and it is the single most important fact here: whatever you think about direction, this is a stock the market expects to move.
Our read of the options data comes out neutral with a bearish tilt. The reason is not price — price has been strong — it is that the flow underneath it has been quietly leaning the other way: traders have been bidding up downside protection relative to this name's own norm, and our leading positioning read has been diverging from price for several sessions. Two technical models disagree and point higher. The level that settles it: a close above $112.00 kills this read.
2 · What the options market is pricing
What changed this week
The stock did the heavy lifting: INTC is up 5.50% over the trailing five sessions and 17.88% over twenty, including a 3.61% opening gap higher on September 17 (prior close $101.05, open $104.70) that followed a 6.92% gap down on September 14. This has been a violent, two-sided tape, not a smooth trend.
Implied volatility — the market's estimate of how much INTC will move, baked into option prices — rose 8.47% over five days to 63.8%, even as it sits 17.72% below where it was a month ago. In other words, the chain re-priced upward into Friday's expiry week after a month of steady cooling.
Open interest tells a more interesting story. The put/call open-interest ratio — how many put contracts are held open for every call — drifted from 0.60 to 0.58 over five days, versus a 7-day average of 0.63 and a 14-day average of 0.65. Puts have been thinning, not building, in stock terms. But the day-over-day flow flipped on Friday: call open interest grew 85,261 contracts while put open interest grew 99,538. Put/call volume came in at 0.56, right on its 3-day average of 0.53 and below its 7-day 0.59 — so the pace of put activity is normal; it was the net new positioning that tilted put-side for a day.
The single biggest forward-looking open-interest build was in the September 25 $115 calls, which added 8,391 contracts on 8,156 of volume — the week's call wall was effectively built in one session. Further out, the October 16 $120 calls added 9,160 contracts and the October 30 $120 calls added 8,387. (Into Friday's expiration, the settled $112 calls shed and gained OI violently — +22,382 contracts — but those are history now, not a live magnet.)
One note on the bigger picture: the short- and long-term trend reads currently agree in direction — bullish over the past week and the past month, flat over the past two-and-a-half months. But the momentum composite itself flipped from bullish to bearish on September 16, two days before Friday's close. Price kept going; the flow behind it turned. That tension is the whole story of this article.
Expected move
The expected move is the range the options market is pricing in — derived from what at-the-money straddles cost. Into September 25, that is ±8.72%, or about ±$9.47, giving a band of $99.13 to $118.07 around Friday's $108.60 close.
| Expiration | Implied move | Range around $108.60 |
|---|---|---|
| Sep 21 (3 days) | ±3.91% | $104.35 – $112.85 |
| Sep 23 (5 days) | ±6.51% | $101.53 – $115.67 |
| Sep 25 (6 days) | ±8.72% | $99.13 – $118.07 |
| Oct 2 (14 days) | ±12.15% | $95.41 – $121.79 |
The ladder is unusually steep between the first two rungs. The September 21 contracts carry an at-the-money IV of just 43.2%, while September 25 carries 63.0% — a 20-point step-up across two trading days. The Monday expiration is being priced as a quiet session; the back half of the window is being priced for real movement.
Volatility
At-the-money IV is 63.80%, with an IV rank of 35/100 — precisely 34.88, meaning today's IV is cheaper than roughly 65% of the past year's readings for this name. IV percentile sits at 44.8. Direction is mixed: down 1.9% on the day, up 8.5% over five days, down 17.7% over thirty. Current IV sits just above its 30-day average (62.6%) and far below its 90-day average (80.0%) — the summer's volatility regime has genuinely cooled.
The front-month read is unavailable today: Friday was an expiry day, and front-month IV can't be interpolated from a same-day-expiring contract, so there's no term-structure slope to quote.
Two readings versus this stock's own recent history are worth noting. Twenty-day realized volatility — how much INTC has actually been moving — is 60.29%, which sounds enormous but is actually well below this stock's own recent norm. At the same time, the ratio of 5-day to 20-day realized movement is 1.30 and sits well above its norm: the last week has been far choppier than the month around it. That combination — a calm-by-Intel-standards month containing a very jumpy week — is exactly what the two-sided gaps show.
Premium rich or cheap. The volatility risk premium is the gap between how much movement options are priced for and how much INTC has actually delivered — when it's positive, option sellers have been collecting more than realized movement cost them. Today that gap is about +3.5 vol points (63.8% implied against 60.3% delivered), and it sits at the 74th percentile versus this stock's own recent readings — richer than roughly three-quarters of them. The path matters too: the gap was negative as recently as September 15 and has climbed back positive over the last three sessions as implied volatility firmed. That combination — an IV rank of 35 but a 74th-percentile premium over delivered movement — favors collecting premium over the next six days rather than owning it. This stock's options are not expensive versus their own year; they are expensive versus what the stock has actually been doing lately.
Skew and sentiment
Skew measures whether puts and calls the same distance from the stock price cost the same. For INTC they normally don't — calls usually carry the premium. The 25-delta skew reading is −0.6 vol points today (25-delta put IV 63.96% against 25-delta call IV 64.55%), meaning calls are still nominally richer. But the 60-day median is −3.4 vol points, and the 7-day average is −2.1. So the call premium has collapsed from about three and a half points to barely half a point in a matter of weeks: traders have been paying up for downside protection relative to how this name usually prices it, and that shift is stretched versus its own history. Our read of the flow flags this as the single most bearish input in the entire dataset.
Volume-based sentiment cuts the other way. Put/call volume is 0.56 — for every 100 call contracts traded, 56 puts — versus a 60-day median of 0.52 and a 14-day average of 0.52. That's mildly put-heavy but unremarkable. Total option volume ran 1.28× its 20-day average. Peer-relative unusual flow favored calls 15 contracts to 13.
Sentiment in short-dated options — how the chain is positioned across expiration dates — reads +3 in the 0–7 day bucket (essentially flat, against a 7-day average of +14) and +19 in the 7–30 day bucket (versus a 7-day average of +23). The 30–60 day bucket is isolated at +81, far above its neighbors — localized positioning building well beyond this article's window. For the six days that matter here, the near-dated read has gone flat while the money builds further out.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $142.35 | Context only; INTC sits 23.7% below it, at the 70th percentile of its 52-week range |
| Swing resistance cluster | $126.64 | Nearest heuristic resistance from swing-pivot clustering — an estimate, not a guaranteed reaction zone |
| Implied range high (Sep 25) | $118.07 | Top of the six-day band the options market is pricing |
| Call wall (Sep 25 expiration) | $115.00 | Heaviest call open interest for this expiration — 12,939 contracts, nearly all of it added Friday. Rallies into heavy call OI tend to slow |
| Technical resistance (6-day model) | $112.00 | Chart model's resistance; also our invalidation level |
| Technical resistance (3-day model) | $111.90 | The September 17 swing high |
| Whole chain's heaviest call strike | $110.00 | 192,632 contracts across all expirations and the single largest gamma strike — note this differs from the Sep 25 expiration's own call wall at $115 |
| Last close / spot | $108.60 | Reference for everything above and below |
| Nearest swing support | $107.04 | First structural shelf; the 3-day chart model puts its support cluster at $107.20 |
| 100-day moving average | $106.80 | Price sits just 1.69% above it — the closest major average |
| Technical support (6-day model) | $105.00 | Chart model's support shelf and the invalidation for its bullish scenario |
| Swing support | $103.03 | Second structural shelf |
| Max pain (Sep 25) | $100.00 | The price where the most option value would expire worthless — expirations sometimes gravitate toward it. It sits 7.9% below spot |
| Implied range low (Sep 25) | $99.13 | Bottom of the six-day band |
| 50-day / 20-day moving averages | $97.09 / $95.87 | Price is 11.9% and 13.3% above them — the rally is extended versus its own averages |
| Put wall (Sep 25 expiration) | $90.00 | Heaviest put open interest for this expiration — 3,367 contracts. Far below spot, and thin: there is no dense downside shelf inside the week |
| Whole chain's heaviest put strike | $80.00 | 59,004 contracts across all expirations — longer-dated hedging, not a level for this week |
Two things stand out. First, the aggregate and the week disagree on where the ceiling is: the whole chain's heaviest call strike is $110, but the September 25 expiration's own call wall is $115. For this week, use $115. Second, the week's put wall at $90 is both far away and shallow — the downside inside this expiration has no meaningful options-based floor until well below the implied range.
Positioning and unusual flow
The dealer gamma estimate reads positive both for the whole chain and for the September 25 expiration specifically, with a flip level estimated around $70. Read that as: under the standard sign assumption, market makers' hedging currently tends to dampen moves rather than amplify them, and spot sits roughly 40% above the flip estimate — comfortably on the supportive side and unusually far from it for this name. This is an estimate built on an assumed dealer convention, not observed inventory, so treat it as a rough regime read rather than a fact.
Three non-expired flow items worth naming:
- Sep 21 $110 calls — 16,258 contracts traded against 1,645 open, nearly ten turns of the open interest, for about $1.83 million of premium. Short-dated upside chasing into a Monday expiration priced at just 43% IV.
- Sep 25 $115 calls — 8,156 traded, open interest up 8,391 to 12,939. This is where the week's ceiling got built, and the fact that open interest rose more than volume traded means real new positions, not day-trading churn.
- Oct 2 $110 puts — 2,923 traded on 429 open, about $1.72 million of premium. Protection being bought just past this article's window.
Our leading positioning read — a composite built only from flow, skew and term-structure inputs, with price and IV trend deliberately excluded so it can move ahead of confirmed momentum — currently sits at a negative reading and has been in a divergence state since September 15. Over the trailing ten sessions, price rose 5.6% while that score fell roughly 48 points. That is the classic shape of conditions that have historically preceded a turn. It is an early, unconfirmed read by construction, not a confirmed turn and not a signal to trade.
3 · Technical check
Both chart models supplied for this window are bullish, and both diverge from the options read.
The 3-day model (target date September 22) projects $110.30 with a forecast range of $105.90 to $111.70. Its case: price holds above the EMA13/EMA34 stack and VWAP, ADX at 25.9 with +DI (37.6) well above −DI (21.6) confirms a strong directional trend, and money flow flipped back positive into the close after a shallow dip. Its own invalidation is a close back below $107.20.
The 6-day model (target date September 25 — our expiration) projects $111.50 with a forecast range of $104.50 to $112.50, reading the September 17–18 action as a bull flag within an intact uptrend. Its dominant scenario (45%) is a breakout above $111.50 toward $114–$115, invalidated on a close below $105.00. Its bearish alternative carries 28%.
Model vs. Market: The options market implies $99.13–$118.07 into September 25 — a band nearly nineteen dollars wide. The 6-day technical model targets $111.50 inside a forecast range of $104.50–$112.50, barely eight dollars wide. The chart model is both more directional and dramatically more confident than the options chain; the options chain is pricing genuine two-way risk that the chart read does not contemplate. If INTC simply grinds to $111 and stops, the chart wins and the option buyers lose. If either tail in that $99–$118 band gets touched, the chart model is outside its own range.
How this shaped the trades below: the technical read did not flip the headline bias — it can't, on its own — but it did pull the short call strike away from spot. With two models pointing at $110–$112, selling a call spread at $112 would be fighting a live uptrend at the exact level both models target. The short strike sits at the $115 call wall instead, safely above both projections.
Full technical write-ups: 3-day report → · 6-day report →
4 · Three ways the next six days can go
If INTC pushes above the call wall ($115): That strike holds 12,939 contracts of call open interest, nearly all of it added in a single session — and heavy call OI overhead tends to slow rallies as dealers hedge into them. A clean break through leaves comparatively thin positioning until the top of the implied range at $118.07. This is also the branch that kills the article's read outright, and it would do so at $112.00, well before $115.
If INTC drifts between the walls: Max pain for this expiration sits at $100.00, almost eight percent below spot — an unusually wide gap, and a reminder that expirations sometimes pull toward where the most option value expires worthless. The dealer gamma estimate is positive here, meaning hedging flows currently tend to cushion rather than accelerate moves. In practice that argues for chop inside the $105–$115 band rather than a clean trend in either direction, which is precisely the scenario the premium-selling structures below are built for.
If INTC breaks below the structural shelf ($107.04): There is very little options-based support inside this expiration. The week's put wall is all the way down at $90.00 and holds only 3,367 contracts. Between the $107 shelf and max pain at $100 the chain is thin, and the two most recent gaps in this name were 6.9% and 3.6% — this stock moves in jumps. Spot remains far above the gamma flip estimate (~$70), so the supportive hedging regime should stay intact even on a meaningful drop; the risk is speed, not regime change.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-09-18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
Premium is rich versus what this stock has actually delivered (about 3.5 vol points, 74th percentile against its own history), so credit structures lead here. All three use the September 25 expiration — the outlook target — and all three have a defined maximum loss.
If you lean bearish (the bias-aligned structure): short call spread
- Trade: Sell the Sep 25 $115 call, buy the Sep 25 $118 call
- Credit: $0.57 · Max profit: $57 per spread · Max loss: $243 · Break-even: $115.57
- Why it fits: The short strike is the week's call wall — the heaviest call open interest at this expiration, 12,939 contracts — and it sits above both chart models' targets ($110.30 and $111.50) and above the top of the 3-day implied range ($112.85). You are selling into the single strike where positioning is densest, in a week where premium sits at the 74th percentile of its own recent richness.
- Makes sense only if: you accept that the two technical reads point higher and that a 63.8% IV stock can cover $6.40 in six days without trying hard.
- Invalidated if: INTC closes above $112.00
- Managing it: Close at roughly 50% of max credit; exit no later than Wednesday, September 23 regardless of P&L, because the last two days of a 63% IV weekly are where gamma risk dominates the remaining theta. If INTC closes through $115, close the position rather than hope for the pin.
- Liquidity note: The $115 calls are quoted 7¢ wide (about 4.7% of mid) on 8,156 contracts of volume; the $118 calls are 6¢ wide on 637 contracts. The short leg fills easily; work the long wing with a limit.
- Analyze this position →
If you expect the range to hold: iron condor, shaded bearish
- Trade: Sell the Sep 25 $98/$94 put spread and the Sep 25 $116/$120 call spread (four legs, one order). A condor collects premium on both sides and pays maximum if the stock finishes between the two short strikes.
- Credit: $0.89 · Max profit: $89 · Max loss: $311 · Break-evens: $97.11 and $116.89
- Why it fits: The short put at $98 sits below the implied range low ($99.13); the short call at $116 sits just above the call wall ($115). The call side is deliberately closer to spot than the put side — that is the bearish tilt expressed as strike placement rather than as a directional bet. The positive dealer gamma estimate supports the case for chop over trend inside this window.
- Makes sense only if: you genuinely expect INTC to stay inside an 18-point box for six days — which the options market itself is only giving roughly even odds.
- Invalidated if: INTC closes outside $105.00–$112.00; at that point one side is live and the structure should be managed, not held.
- Managing it: Take 50% of max credit and leave. Roll or close the tested side if the stock closes through either short strike. Do not carry this into the final session.
- Liquidity note: The $116 calls are 12¢ wide (about 9% of mid) and the $94 puts are 6¢ wide on a 19¢ mid — in percentage terms both wings are wide, so enter as a single four-leg limit order at the mid and be patient rather than legging in.
- Analyze this position →
If you lean bullish (siding with the charts): short put spread
- Trade: Sell the Sep 25 $105 put, buy the Sep 25 $100 put. You collect the credit up front and keep it if INTC finishes above $105.
- Credit: $1.25 · Max profit: $125 · Max loss: $375 · Break-even: $103.75
- Why it fits: This is the structure for a reader who weights the two bullish chart models over the positioning read. The short strike sits below the $107.04 swing shelf and the 100-day moving average at $106.80, and the long wing is bought right at max pain ($100.00). A 25% credit-to-width ratio is respectable for a six-day spread.
- Makes sense only if: the September 17 gap holds. The short strike is only 3.3% below spot against an implied move of 8.72% — there is no comfortable cushion here, and that is the honest cost of fighting the positioning read.
- Invalidated if: INTC closes below $105.00
- Managing it: Because the near-term direction is running against a flat two-and-a-half-month trend, take profits early — 40–50% of max credit — rather than holding for the last few cents. Close on any daily close below $107.04.
- Liquidity note: The $105 puts are 11¢ wide on 4,268 contracts of volume; the $100 puts are 7¢ wide on 6,217. Both fill easily.
- Analyze this position →
If none of these: no trade
Premium is rich and not distorted by any scheduled event, so the case for selling it is real — which means standing aside has to clear a higher bar than usual. Here is where it clears: an 8.72% implied move over six days means the short strikes on every structure above are only two to three points outside a one-standard-deviation band, and the last two sessions in this name produced gaps of 6.9% and 3.6%. A 3.5-vol-point edge does not compensate you for gap risk of that size if you cannot watch the position. The condor's $89 of credit against $311 of risk assumes you will actively manage a tested side; if you can't, the honest answer is that this is a week to read the chain rather than trade it. There is also no clean directional consensus — our positioning read tilts one way, both chart models the other — and "rich premium plus no directional edge plus a stock that gaps 7%" is a fine description of a week to sit out.
6 · Quick FAQ
What is INTC's expected move this week? About ±$9.47, or ±8.72%, into the September 25 expiration — a range of $99.13 to $118.07 — per the options market's straddle pricing as of Friday, September 18.
Is INTC expected to go up or down over the next six days? Options positioning as of September 18 leans neutral with a bearish tilt — downside protection has gotten relatively more expensive versus this name's own norm and our leading positioning read has diverged from a rising price — but that is a description of what traders have already done, not a forecast. The actionable map is the $99.13–$118.07 range, the $115 call wall and the $107.04 shelf below.
Are INTC options expensive right now? Two lenses. IV rank of 35/100 says option prices are lower than 65% of the past year's readings. But they are running about 3.5 vol points above the movement INTC has actually delivered over the past twenty days — richer than roughly 74% of this stock's own recent readings. Net verdict: cheap versus the year, rich versus what the stock is doing. That favors collecting premium this week.
Where is INTC's biggest options support and resistance? For the September 25 expiration, the put wall is $90.00 and the call wall is $115.00. Note that the whole chain's heaviest call strike is $110.00 — that's driven by longer-dated expirations, not this week.
What invalidates this read? A close above $112.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for INTC, 2026-09-18, generated 2026-09-19T22:24:12.071Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.