MARA Options Are Pricing a $1.47 Move Into September 25 — But the Call Wall Sits Below Spot
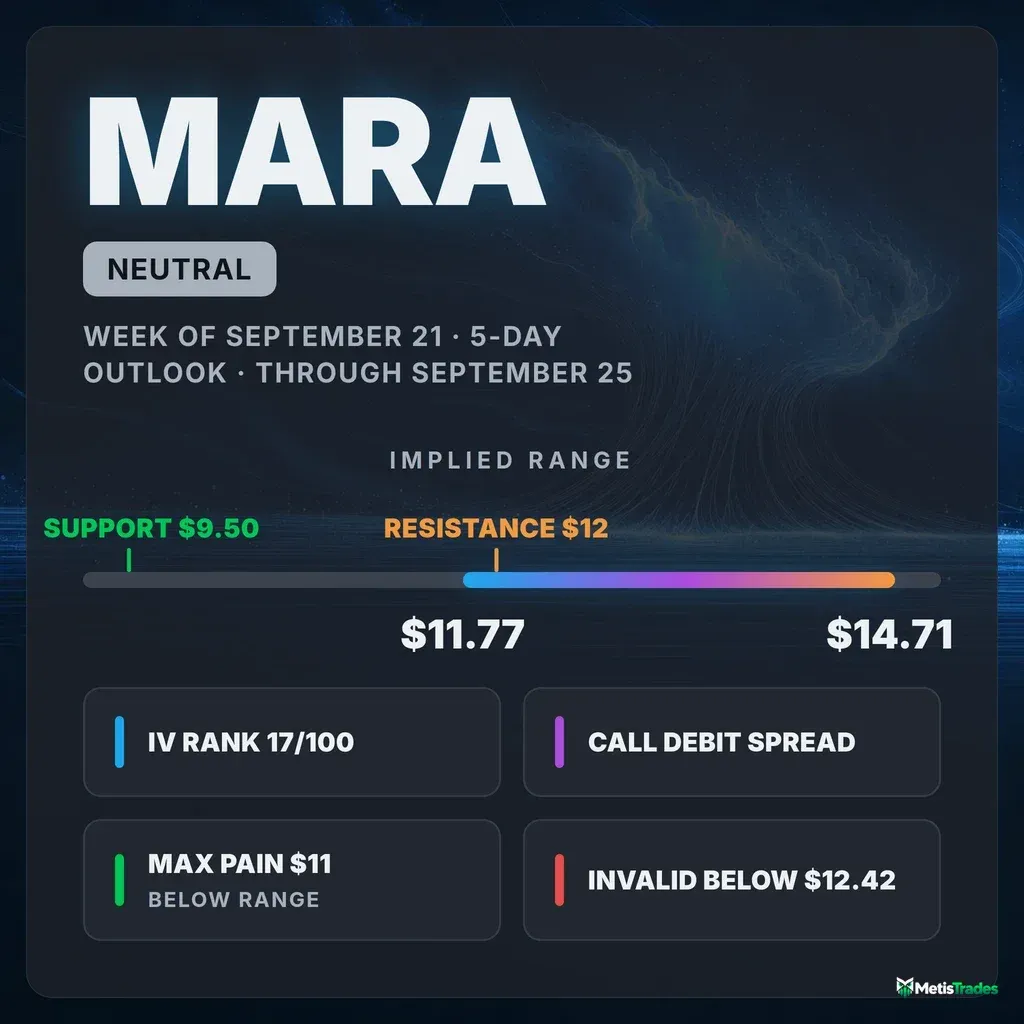
MARA ripped 10.5% in five sessions and the options market now implies an $11.77–$14.71 range into the September 25 expiration. The odd part: that expiration's heaviest call open interest sits at $12.00, already $1.24 under the stock.
Listen to this analysis — prefer audio? This MARA outlook is also available as a podcast episode:
The options market implies an $11.77–$14.71 range into the September 25 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18 close
Explore the live MARA options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into September 25) | $11.77 – $14.71 (±11.10%, or about ±$1.47) |
| Major support | $9.50 — the September 25 put wall (10,147 contracts); nearest structural support is $12.42 |
| Major resistance | $12.00 — the September 25 call wall (12,237 contracts), already below spot |
| Max pain (September 25) | $11.00 |
| Dealer gamma regime (estimate) | Positive — market-maker hedging tends to dampen moves; flip level ≈ $12.50 |
| Volatility condition | Falling — IV rank 17.1/100 · premium thin: options priced about 7 vol points below delivered movement |
| Technical check | Mixed (chart model bullish, 3-day and 5-day, targeting $13.65) |
| Best-fitting strategy | Long call vertical ($13/$14, September 25) — only if you want directional exposure while premium is cheap |
| Analysis invalidated if | MARA closes below $12.42 |
1 · What matters today
MARA closed Friday, September 18 at $13.24 after a 10.5% five-session run, and the options market is pricing about $1.47 up or down through the September 25 expiration — a range of roughly $11.77 to $14.71. That figure comes from what straddles cost: it is the market's own estimate of movement, not a forecast of direction.
Our read of the options data lands neutral, and the reason is worth stating plainly. Flow, sentiment across expirations and skew all lean mildly positive. But the September 25 expiration's heaviest pile of call open interest — contracts currently held open — sits at $12.00, which the stock has already run straight through. Price is now perched above its own options structure, with max pain at $11.00 well below. That combination nets out flat.
The level that changes the picture is $12.42, the shelf Friday's gap cleared. The chart model is more committed than we are: bullish, targeting $13.65 by September 25.
2 · What the options market is pricing
What changed over the past week
Friday was the story. MARA gapped up 4.12% at the open (prior close $11.64, open $12.12) and finished at $13.24 — up 10.5% over five trading days and 18.7% over twenty. Total option volume ran 2.88× its 20-day average, and it was overwhelmingly call-side: put/call volume came in at 0.28, meaning only 28 puts traded for every 100 calls, against a 7-day average of 0.38 and a 14-day average of 0.41. That is unusually call-tilted even measured against this stock's own recent norm.
Open interest tells a slightly different story. The put/call open-interest ratio drifted from 0.66 to 0.72 over five sessions — for every 100 call contracts held open there are now 72 puts, up from 66. Traders chased calls intraday while quietly adding downside protection to their books. The single biggest non-expired open-interest change was the September 25 $12 calls, up 3,668 contracts to 12,237 — which is precisely why that strike is the expiration's call wall. Into the September 18 expiration that settled Friday, the $12 calls traded 72,645 contracts for about $9.0 million of premium against 81,275 open — settled history now, but it shows where the week's fight was.
Implied volatility — the market's estimate of how much MARA will move, baked into option prices — barely budged on the day (+1.0%) and is down 15.7% over thirty. The short- and long-term trend reads agree on direction, which is rare enough to note: price is up over the past week and up 18.7% over the past month, while the ~50-day read is essentially flat (+0.2%). The bounce is real but it is a bounce inside a two-month round trip.
Expected move
Into September 25, the options market is pricing about ±$1.47 (±11.10%) around the $13.24 close — a range of $11.77 to $14.71. Here is how that scales out:
| Expiration | Implied move | Range around $13.24 |
|---|---|---|
| September 25 | ±11.10% | $11.77 – $14.71 |
| October 2 | ±15.94% | $11.13 – $15.35 |
| October 9 | ±19.70% | $10.63 – $15.85 |
| October 16 | ±22.94% | $10.20 – $16.28 |
The rungs step up smoothly with time rather than jumping — there is no event bump anywhere in this ladder, just implied volatility of roughly 80–83% stretched over more days.
Volatility
At-the-money implied volatility is 83.1%, with an IV rank of 17.1/100 — today's IV is cheaper than about 83% of the past year's readings. It sits below both the 30-day average (84.4%) and the 90-day average (88.5%), and the rank itself has slid from a 7-day average of 25.7 and a 14-day average of 28.6. The front-month read is unavailable today (Friday was an expiry day, so the nearest-expiration figure can't be interpolated), so there is no term-structure line this session.
Meanwhile the stock itself is getting more active, not less: MARA's five-day realized movement is running about 24% hotter than its own 20-day pace, a reading well above its own norm, and price momentum is running well above its norm too.
Premium: cheap, not rich. The volatility risk premium — the gap between how much movement options are priced for and how much MARA has actually delivered — is about 7 vol points negative: implied volatility near 83% against 20-day realized volatility of 90.4%. When that number is positive, option sellers have been collecting more than realized movement cost them; here it is the other way around. It sits at the 36th percentile of this stock's own recent readings, meaning it is thinner than roughly two-thirds of them. The gap has been narrowing steadily all month (it was about 14 vol points negative on August 31), but it has not flipped. Combine that with an IV rank of 17 and the verdict is one-sided: this is a week that favors owning premium rather than collecting it. Anyone selling here is selling something that hasn't been rich for weeks.
Skew and sentiment
Skew measures whether puts and calls the same distance from the stock price cost the same. On MARA they don't — and not in the usual direction. The 25-delta put trades at 83.5% implied volatility against 85.7% for the 25-delta call, so puts are running 2.2 vol points cheaper than calls, against a 60-day norm of 1.4 points cheaper. Traders here are paying up for upside, not for crash protection, and slightly more so than is typical for this name.
Sentiment across expirations is genuinely mixed. The 0–7 day bucket reads slightly negative, driven by call open interest coming off after Friday's expiry. The 7–30 day and 30–60 day buckets both read firmly positive, on call-side open-interest building and call-dominated delta-weighted flow. In short: the front is flat, the next month leans bullish. Our leading positioning read adds a wrinkle — price has climbed about 5% over the past ten sessions while that positioning score has drifted lower, the kind of gap that has historically shown up before momentum turns. It is an early, unconfirmed observation, not a turn.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Swing resistance | $15.32 | Heuristic swing-pivot cluster above the implied range |
| Largest gamma strike (chain-wide) | $15.00 | Third-heaviest total gamma across all expirations |
| Swing resistance | $14.87 | Next pivot cluster overhead |
| Implied range top (Sept 25) | $14.71 | Upper rail of the options-implied move |
| Secondary call OI cluster (Sept 25) | $14.50 | 10,852 contracts — the first real overhead pile above spot for this expiration |
| Swing resistance | $14.41 | Nearest pivot resistance |
| Spot / last close | $13.24 | Friday, September 18 close |
| Swing support | $13.16 | Nearest pivot support, right under spot |
| Heaviest gamma strike (chain-wide) | $13.00 | Largest total gamma·OI across all expirations — a natural magnet |
| Gamma flip level (estimate) | $12.50 | One rough estimate: below here, hedging tends to amplify rather than cushion moves |
| Swing support / breakout shelf | $12.42 | The ceiling Friday's gap cleared; our invalidation level |
| 100-day moving average | $12.24 | Price sits 8.2% above it |
| Call wall (Sept 25) | $12.00 | 12,237 contracts — also the chain-wide heaviest call strike at 118,521; already below spot |
| Implied range low (Sept 25) | $11.77 | Lower rail of the options-implied move |
| 20-day / 50-day moving averages | $11.41 / $11.19 | Price is 16–18% extended above both |
| Max pain (Sept 25) | $11.00 | Where the most option value would expire worthless |
| Put wall (Sept 25) | $9.50 | 10,147 contracts — the heaviest put OI for this expiration, far below spot |
Note the disagreement worth flagging: the whole chain's heaviest put strike is $10.00 (97,385 contracts), while the September 25 expiration's own put wall is $9.50. For this week, use $9.50 — and recognize that it is nearly 30% below spot, which means there is no meaningful options-based floor anywhere near current price for this expiration.
Positioning and unusual flow
The dealer gamma estimate for September 25 reads positive — under the standard (and unverified) assumption about how dealers are positioned, hedging in this regime tends to dampen moves rather than accelerate them. Spot sits about 5.6% above the estimated flip level of $12.50, comfortably on the supportive side, though closer to it than this stock's own typical reading. Treat all of that as an estimate, not observed dealer inventory.
Three non-expired flow items stood out Friday:
- September 25 $13 calls — 61,543 contracts traded against 9,144 open, about $4.4 million of premium. The single largest dollar flow in any live expiration, and it is right at the money.
- September 25 $13.50 calls — 43,746 contracts against 4,101 open, roughly $2.1 million. Open interest only rose 991, so most of that was same-day round-tripping, not new positions.
- October 23 $9.50 puts — 7,918 contracts against just 95 open, about $127,000 of premium. A turnover ratio above 80× on a strike 28% below spot is the week's one clear piece of cheap disaster hedging.
3 · Technical check
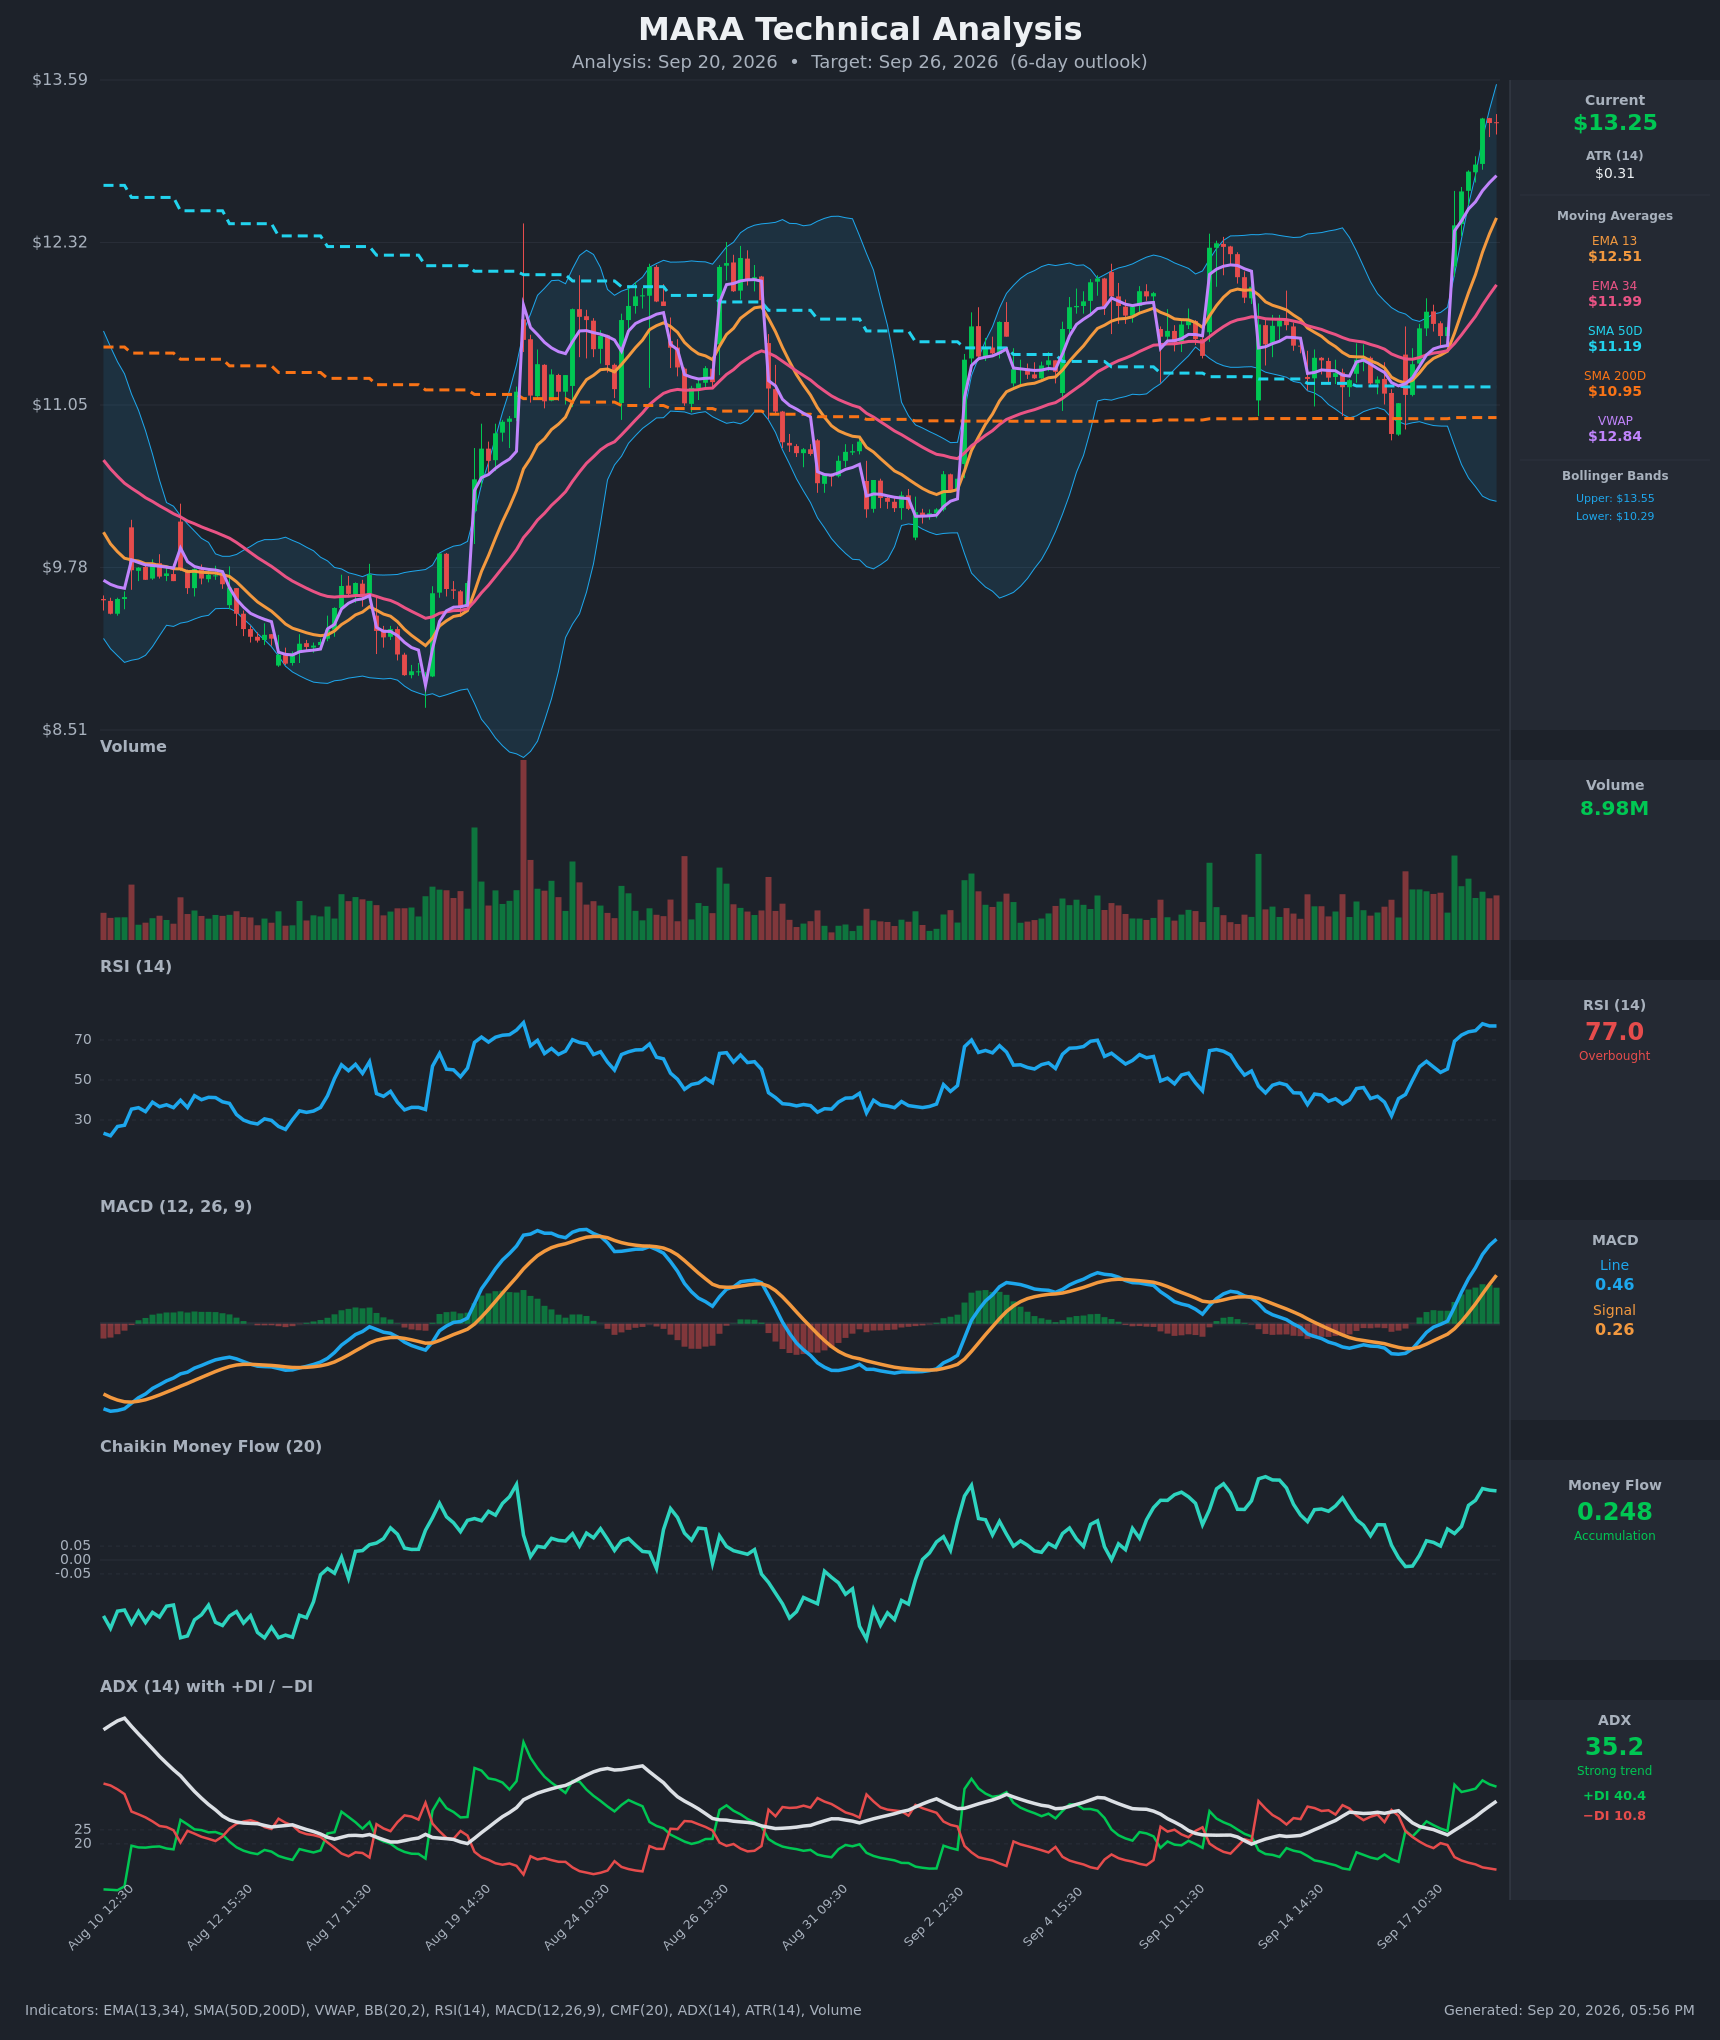
Both chart-model reports are bullish. The 3-day report (target date September 23) projects $13.65 within a $12.75–$13.75 band; the 5-day report (target date September 25) also targets $13.65, within $12.75–$13.80. Their reference price of $13.25 matches the options snapshot's $13.24 closely enough to treat the two as the same session.
The supporting reads are decisive rather than marginal: ADX at 35.2 with +DI at 40.4 against −DI at 10.8 is one of the strongest directional trend confirmations in that dataset, and money flow has been positive throughout the advance. The counterweight is RSI at 77 — deeply overbought — with price pressing the upper Bollinger band at $13.55. The model's own dominant scenario (50% weight) invalidates on a close back below VWAP at $12.84.
Model vs. Market: The options market implies $11.77–$14.71 into September 25; the 5-day technical model targets $13.65 inside a much narrower $12.75–$13.80 band. Both point at roughly the same center — the disagreement is entirely about width. Options are paying for a tail the chart model doesn't expect, which is exactly the setup where a defined-risk structure beats an outright directional bet.
The TA did move one strike: the call vertical below keeps its short leg at $14.00 rather than $13.50, so it still profits fully inside the chart model's projected ceiling.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If MARA pushes above $14.50: the September 25 call wall at $12.00 is already behind price, so the usual "heaviest call OI caps the rally" logic doesn't apply this week. The next genuine overhead pile is the $14.50 strike with 10,852 contracts open, sitting right beneath the implied ceiling at $14.71. A clean move through there leaves thin options positioning until $15.00, where the chain's third-largest gamma concentration sits.
If MARA drifts between $12.42 and $14.50: this is the base case the positioning supports. The estimated gamma regime is positive, which tends to damp rather than amplify day-to-day swings, and the chain's heaviest total-gamma strike is $13.00 — essentially where the stock closed. Max pain for September 25 is $11.00, far below, so there is no meaningful pull toward it unless price first loses the breakout shelf.
If MARA breaks below $12.42: that is the gap shelf Friday cleared, and just underneath it sits the estimated gamma flip at $12.50 — below which one rough estimate suggests market-maker hedging starts amplifying selling rather than cushioning it. Spot currently sits closer to that flip estimate than is typical for this stock. Because this expiration's put wall is all the way down at $9.50, there is very little options-based support between here and the $11.00 max-pain area if that shelf fails.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of September 18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bullish: September 25 $13/$14 call debit spread
- Trade: Buy the September 25 $13 call, sell the September 25 $14 call
- Debit: $0.39 · Max profit: $0.61 · Max loss: $0.39 · Break-even: $13.39
- Why it fits: With the premium gap negative — options priced about 7 vol points below what MARA has actually delivered — buying defined premium is the structurally cheaper side of this market. The short $14 leg sits just above the chart model's $13.80 ceiling, so the spread reaches max value inside the zone both the model and the implied range consider reachable.
- Makes sense only if: you want the bullish exposure the chart is showing and accept that our own options read is flat, not bullish.
- Invalidated if: MARA closes below $12.42.
- Managing it: the short-term trend is running well ahead of a flat ~50-day trend, which argues for taking profits early rather than holding to expiration — close at roughly 65–70% of max value, and exit the whole thing by September 24 regardless rather than fighting the last day of time decay.
- Liquidity note: the $13 calls traded $0.71 × $0.72 (1.4% wide) on about $4.4 million of premium, and the $14 calls $0.32 × $0.33 — the tightest pair on the board.
- Analyze this position →
If you expect the range to hold: September 25 $12/$11 put · $14.50/$15.50 call iron condor
- Trade: Sell the $12 put, buy the $11 put, sell the $14.50 call, buy the $15.50 call — all September 25
- Credit: $0.23 · Max profit: $0.23 · Max loss: $0.77 · Break-evens: $11.77 and $14.73
- Why it fits: those break-evens land almost exactly on the options-implied rails of $11.77 and $14.71, so the structure pays as long as MARA stays inside the move the market itself is pricing. The short call is parked at $14.50, where 10,852 contracts of call open interest already sit.
- Health warning: you're selling premium that hasn't been rich lately. IV rank is 17/100 and implied volatility is running below realized — this is the least attractive week of the past month to be short options, and the $0.23 credit against $0.77 of risk reflects that.
- Makes sense only if: you believe Friday's thrust exhausts itself into a digestion range, and you are comfortable being short gamma on a stock whose five-day realized movement is accelerating.
- Invalidated if: MARA closes below $12.42 or above $14.50.
- Managing it: close at about 50% of max credit; exit regardless by September 24. If either short strike is breached on a closing basis, close the tested side rather than hoping for a retrace.
- Liquidity note: the $12 puts traded $0.14 × $0.15 and the $14.50 calls $0.20 × $0.22 — fine. The protective wings are the problem: the $11 puts are $0.03 × $0.04 and the $15.50 calls $0.08 × $0.10, penny markets that are percentage-wide. Work the four legs as a single order and expect slippage.
- Analyze this position →
If you lean bearish: September 25 $13/$12 put debit spread
- Trade: Buy the September 25 $13 put, sell the September 25 $12 put
- Debit: $0.32 · Max profit: $0.68 · Max loss: $0.32 · Break-even: $12.68
- Why it fits: this is the mean-reversion expression. Price is 16% above its 20-day and 18% above its 50-day moving average, max pain for the expiration sits at $11.00, and the short $12 leg is pinned at the expiration's call wall — the strike with the most contracts that would lose their value on a retreat. With puts 2.2 vol points cheaper than calls, the downside leg is also the cheaper one to own.
- Makes sense only if: you think the gap shelf at $12.42 fails and the estimated flip at $12.50 opens the trapdoor.
- Invalidated if: MARA closes above $14.50 — through the overhead open-interest cluster.
- Managing it: take profit near $12.10–$12.20 rather than waiting for the full $12.00 pin; cut at half the debit if the stock closes back above $13.55.
- Liquidity note: the $13 puts traded $0.46 × $0.47 (about 2.2% wide) on roughly $277,000 of premium; the $12 puts are a penny wide at $0.14 × $0.15.
- Analyze this position →
If none of these: no trade
Standing aside is defensible here, and the case is specifically about premium. IV rank at 17/100 with implied volatility running below realized means credit structures are being paid poorly for real risk — the condor above collects $0.23 to carry $0.77, on a stock that moved 13.7% in a single session on Friday. And on the debit side, cheap premium is only an edge if you have a directional view; our options read is flat, which means a long vertical is a bet on the chart, not on the flow. If you don't hold that view independently, the honest answer this week is to wait for either the $12.42 shelf to be tested or implied volatility to catch back up to what MARA is actually delivering.
6 · Quick FAQ
What is MARA's expected move into September 25? About ±$1.47, or ±11.10% — a range of $11.77 to $14.71 around the $13.24 close, per straddle pricing as of September 18.
Is MARA expected to go up or down over the next five days? Options positioning as of September 18 reads neutral — call-heavy flow and positive sentiment in the 7–30 day expirations are offset by a stock trading well above its own open-interest structure — but that's a read of what traders have done, not a forecast. The actionable map is the $11.77–$14.71 range and the $12.42 / $14.50 levels.
Are MARA options expensive right now? No. IV rank of 17.1/100 says option prices are lower than about 83% of the past year's readings, and on top of that they're running roughly 7 vol points below the movement MARA has actually delivered over the last 20 days — thinner than about two-thirds of this stock's own recent readings. That favors owning premium over selling it.
Where is MARA's biggest options support and resistance? For the September 25 expiration, the put wall is $9.50 (10,147 contracts) and the call wall is $12.00 (12,237 contracts) — with the unusual feature that the call wall now sits below the stock. The first meaningful overhead cluster is $14.50.
What invalidates this read? A close below $12.42.
Methodology & disclosures. Data: end-of-day options-chain snapshot for MARA, 2026-09-18, generated 2026-09-20T17:55:58.123Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.