MSTR Options Are Pricing a $15 Move Into Sep 25 — and Premium Has Rarely Been Cheaper
The options market implies a $138.77–$169.07 range for MSTR into the September 25 expiration, and after a 17.5% five-day surge, option prices are running roughly 37 vol points below what the stock has actually delivered. Here's the positioning map and three defined-risk ways to trade it.
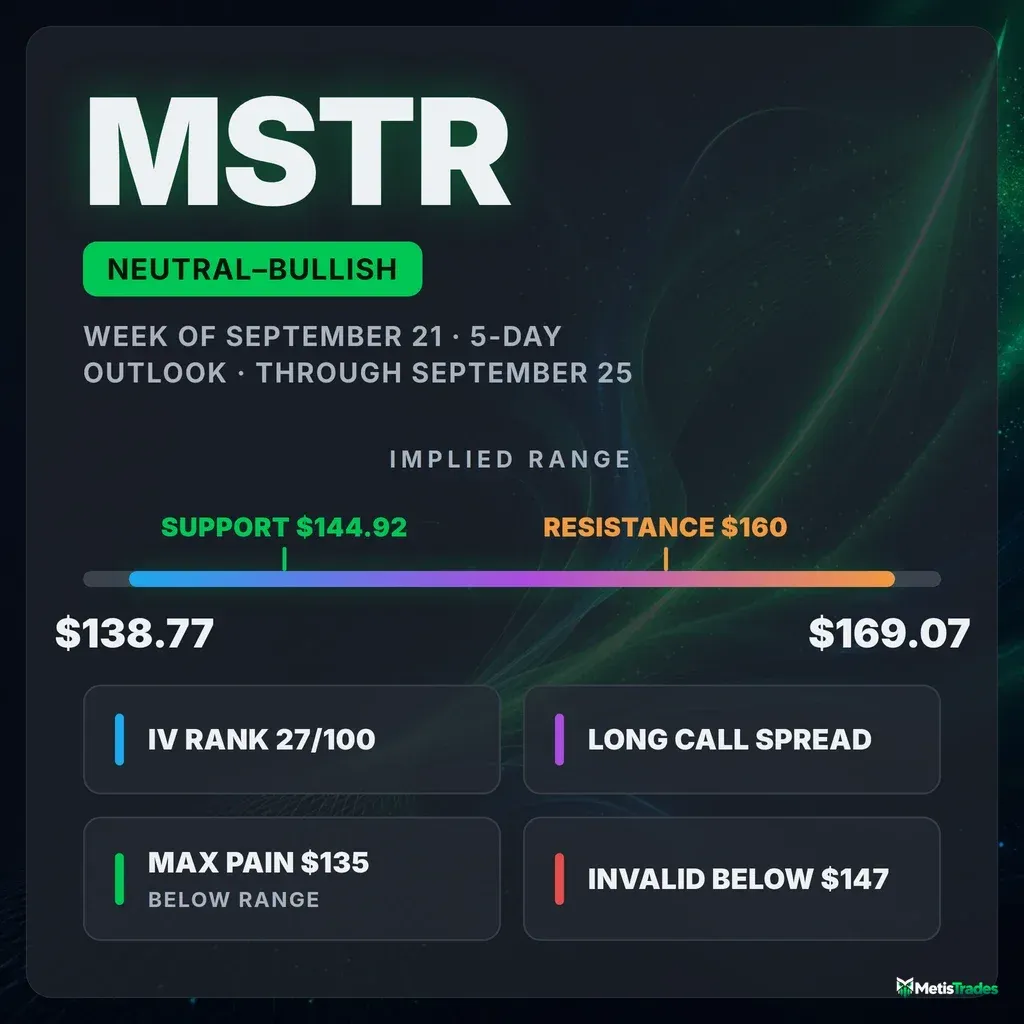
The options market implies a $138.77–$169.07 range into the September 25 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18, 2026 close
Explore the live MSTR options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bullish |
| Options-implied range (into Sep 25) | $138.77 – $169.07 (±9.84%, or about ±$15.15) |
| Major support | $144.92 (nearest swing support; the Sep 25 put wall sits far below at $95.00) |
| Major resistance | $160.00 (heaviest Sep 25 call open interest above spot) |
| Max pain (Sep 25) | $135.00 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $55 |
| Volatility condition | Neutral — IV rank 26.5/100 · premium thin: options priced ~37 vol points below delivered movement |
| Technical check | Confirms (bullish, 3-day and 5-day chart models) |
| Best-fitting strategy | Sep 25 $155 / $162.50 long call spread |
| Analysis invalidated if | MSTR closes below $147.00 |
1 · What matters today
MSTR closed Friday, September 18 at $153.92 after a 17.5% five-day run, and the options chain flipped with it. Put open interest drained, call buying dominated, and 25-delta calls now cost about 8.5 vol points more than the matching puts — traders are paying up for upside, not protection. Our read of that flow lands slightly bullish. The options market is pricing a move of roughly $15.15 either way into the September 25 expiration, a $138.77–$169.07 range. The single most useful fact this week: option prices have fallen far behind how much this stock is actually moving, which makes owning premium — not selling it — the cheaper side of the trade. Both chart models also point higher into next week. A close below $147.00 kills the read.
2 · What the options market is pricing
What changed this week
The whole positioning picture reversed in two sessions. Put/call open interest — how many put contracts are held open for every call — sits at 0.48, against a seven-day average of 0.76 and a 14-day average of 0.72. For every call contract open there are now about half as many puts, and that ratio was above 0.8 five sessions ago: hedges were lifted, not added. Put/call volume tells the same story at 0.46 versus a 0.69 seven-day average, with total option volume running 3.7× its 20-day norm. The biggest live open-interest build of the day was the September 25 $141 calls, which added 11,861 contracts to close at 12,109 open — the $135 calls on the same expiration added 9,609. Into Friday's expiration, flow was frantic but is now settled history: the $150 calls traded 104,850 contracts and the $145 calls 52,112.
Implied volatility barely reacted: ATM IV finished at 70.0%, up 7.3% on the day but only 2.6% over five sessions and 0.7% over 30 — still under its 30-day average of 70.7% and well under its 90-day average of 76.8%. The stock gapped; the options didn't reprice. The short-, medium- and long-horizon trend reads all point the same way (price +17.5% over the past week, +37.0% over the past month, +63.9% over roughly two months), so there's no near-term-versus-long-term tension to resolve here — one direction, three timeframes.
Expected move
The expected move is the move the options market is pricing in, derived from what at-the-money straddles cost. Into September 25 that's ±9.84%, or roughly ±$15.15 around the $153.92 close.
| Expiration | Implied move | Range around $153.92 |
|---|---|---|
| Sep 25 (7 DTE) | ±9.84% | $138.77 – $169.07 |
| Oct 2 (14 DTE) | ±13.59% | $133.00 – $174.84 |
| Oct 16 (28 DTE) | ±19.37% | $124.11 – $183.73 |
The rungs scale almost exactly as the square root of time, with no hump anywhere on the ladder — there's no single dated event the chain is bracing for inside this window.
Volatility
ATM IV of 70.0% carries an IV rank of 26.5/100 — where today's implied volatility sits versus the past year, meaning option prices are cheaper than about 73% of the last twelve months' readings. The percentile measure is a touch higher at 39.7. The front-month read is unavailable today (Friday was an expiry day, so the nearest-expiration IV can't be interpolated), which also means there's no term-structure comparison across dates this session.
The stock itself is another matter. Twenty-day realized volatility — how much MSTR has actually been moving — is running at 107%, well above this name's own recent norm, and five-day movement is about 19% faster than its own monthly pace. The chain has 70% implied volatility priced against a stock delivering 107%.
Premium rich or cheap. That gap is the volatility risk premium: the difference between how much movement options are priced for and how much MSTR has actually delivered. When it's positive, option sellers collect more than realized movement costs them. Here it is deeply negative — about 37 vol points below delivered movement, which is thinner than roughly 99% of this stock's own recent readings, and one of the most stretched negative readings in its recent history. The gap has widened steadily for three weeks (it was about 12 vol points negative at the end of August) as realized volatility climbed while implied volatility stood still. The combination — IV rank 26.5 and a 1st-percentile discount to delivered movement — favors owning premium this week, not collecting it. Selling defined-risk credit here means writing options that have been systematically underpriced against this stock's actual behavior.
Skew and sentiment
Skew measures whether puts and calls the same distance from the stock price cost the same. Normally puts are richer — traders pay up for crash protection. Not here: 25-delta puts are priced at 68.1% implied volatility against 76.6% for 25-delta calls, so calls carry an 8.5 vol point premium, against a 60-day median of 2.6 points for this name. Upside options are the expensive ones, and unusually so versus this stock's own history. That is a call-chase, not a hedging bid.
Sentiment across the curve is split by tenor. The 0–7 day bucket reads a shade negative at −6 (a small put-side open-interest build in the shortest-dated contracts), while the 7–30 day bucket reads a strong +78 on richer calls, call-side open interest building, and delta-weighted volume heavily to the call side. Our summary read of the curve is a bullish recovery with the positioning being built further out rather than in the front week. Day-over-day, the pace of new call open interest and the drain in put open interest both sit well above this symbol's own norms.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Top of 1-month implied range | $183.73 | Upper rail of the Oct 16 expected move |
| Top of 5-day implied range | $169.07 | Upper rail of the Sep 25 expected move |
| Upper strike cluster (Sep 25) | $165.00 | 846 calls open; heavy new turnover Friday |
| Heaviest Sep 25 call OI above spot | $160.00 | 2,939 calls open — the first real overhead pile; also a top-five gamma strike chain-wide |
| Chart-model resistance (estimate) | $158.00 | Upper Bollinger Band per the technical reports |
| Friday's close | $153.92 | Reference price for every level here |
| Gamma/OI cluster | $150.00 | 2,669 Sep 25 calls open plus the chain's third-largest gamma pile; 41,624 contracts traded Friday |
| Chart-model support (estimate) | $147.99 | VWAP per the technical reports; $147.00 is the stated invalidation |
| Nearest swing support | $144.92 | First price-structure shelf beneath spot |
| Call wall, Sep 25 | $141.00 | Heaviest Sep 25 call OI (12,109) — but now below spot after Friday's gap |
| Swing support | $139.78 | Prior consolidation shelf |
| Bottom of 5-day implied range | $138.77 | Lower rail of the Sep 25 expected move |
| 200-day moving average | $137.04 | Price sits 12.3% above it |
| Max pain, Sep 25 | $135.00 | Where the most option value would expire worthless; also the whole chain's heaviest call strike (74,260 open) |
| 20-day moving average | $131.64 | Price sits 16.9% above it |
| Put wall, Sep 25 | $95.00 | Heaviest Sep 25 put OI (5,481) — far out of play this week |
| Gamma flip estimate | ≈ $55 | One rough estimate of where hedging would turn from dampening to amplifying — nowhere near spot |
Two things about this ladder deserve flagging. First, the September 25 expiration's own walls disagree with the whole-chain aggregate: across all expirations the heaviest call strike is $135 and the heaviest put strike is $100, while the week's own expiration carries its call wall at $141.00 and its put wall at $95.00. Use the Sep 25 row for anything about this week. Second, that $141.00 call wall is $12.92 below Friday's close — the biggest pile of calls on the week's expiration is already deep in the money. It is functioning as a magnet and a floor, not a ceiling. The first genuine overhead pile is $160.00.
Positioning and unusual flow
The dealer gamma estimate for the September 25 expiration is positive, meaning that under the standard (unverified) assumption about how market makers are positioned, their hedging should dampen moves rather than amplify them into this expiration. The estimated flip level — below which that hedging would flip to amplifying selling — sits around $55, an unusually distant reading for this name and effectively irrelevant this week. Treat both as estimates, not observed dealer inventory.
Three live (non-expired) flow items stand out, all on the September 25 expiration:
- $150 calls: 41,624 contracts traded against 2,669 open — more than 15 times the standing position, and about $33.5 million of premium changing hands in a single session.
- $155 calls: 35,926 traded against 1,080 open, a 33× turnover and roughly $20.0 million of premium. This is fresh, at-the-money upside positioning, not roll activity.
- $140 puts: 14,039 traded against 854 open. Not everything was one-way — someone bought downside insurance roughly 9% beneath spot, close to the lower implied-move rail.
3 · Technical check
Both chart models read bullish and both confirm the options positioning. The 3-day model targets $157.50 with a projected band of $149.50–$159.50; the 5-day model, which lands exactly on the September 25 expiration, targets $158.50 with a projected band of $148.50–$161.00. Each target sits comfortably inside the options-implied $138.77–$169.07 range, which is the textbook definition of confirmation rather than divergence.
The supporting reads are unusually clean: ADX at 35.4 with +DI at 45.9 against −DI at 10.5 describes a strong, freshly established uptrend, and money-flow (CMF 0.509) shows sustained accumulation over the past three weeks rather than a one-bar spike. The obvious caution is RSI at 78.2 — deep in overbought territory after a two-session vertical move. Both reports flag a cooling-off dip toward the $147–$150 zone as a live scenario, and the dominant scenario's invalidation is a close below $147.00. That's the number this article adopts.
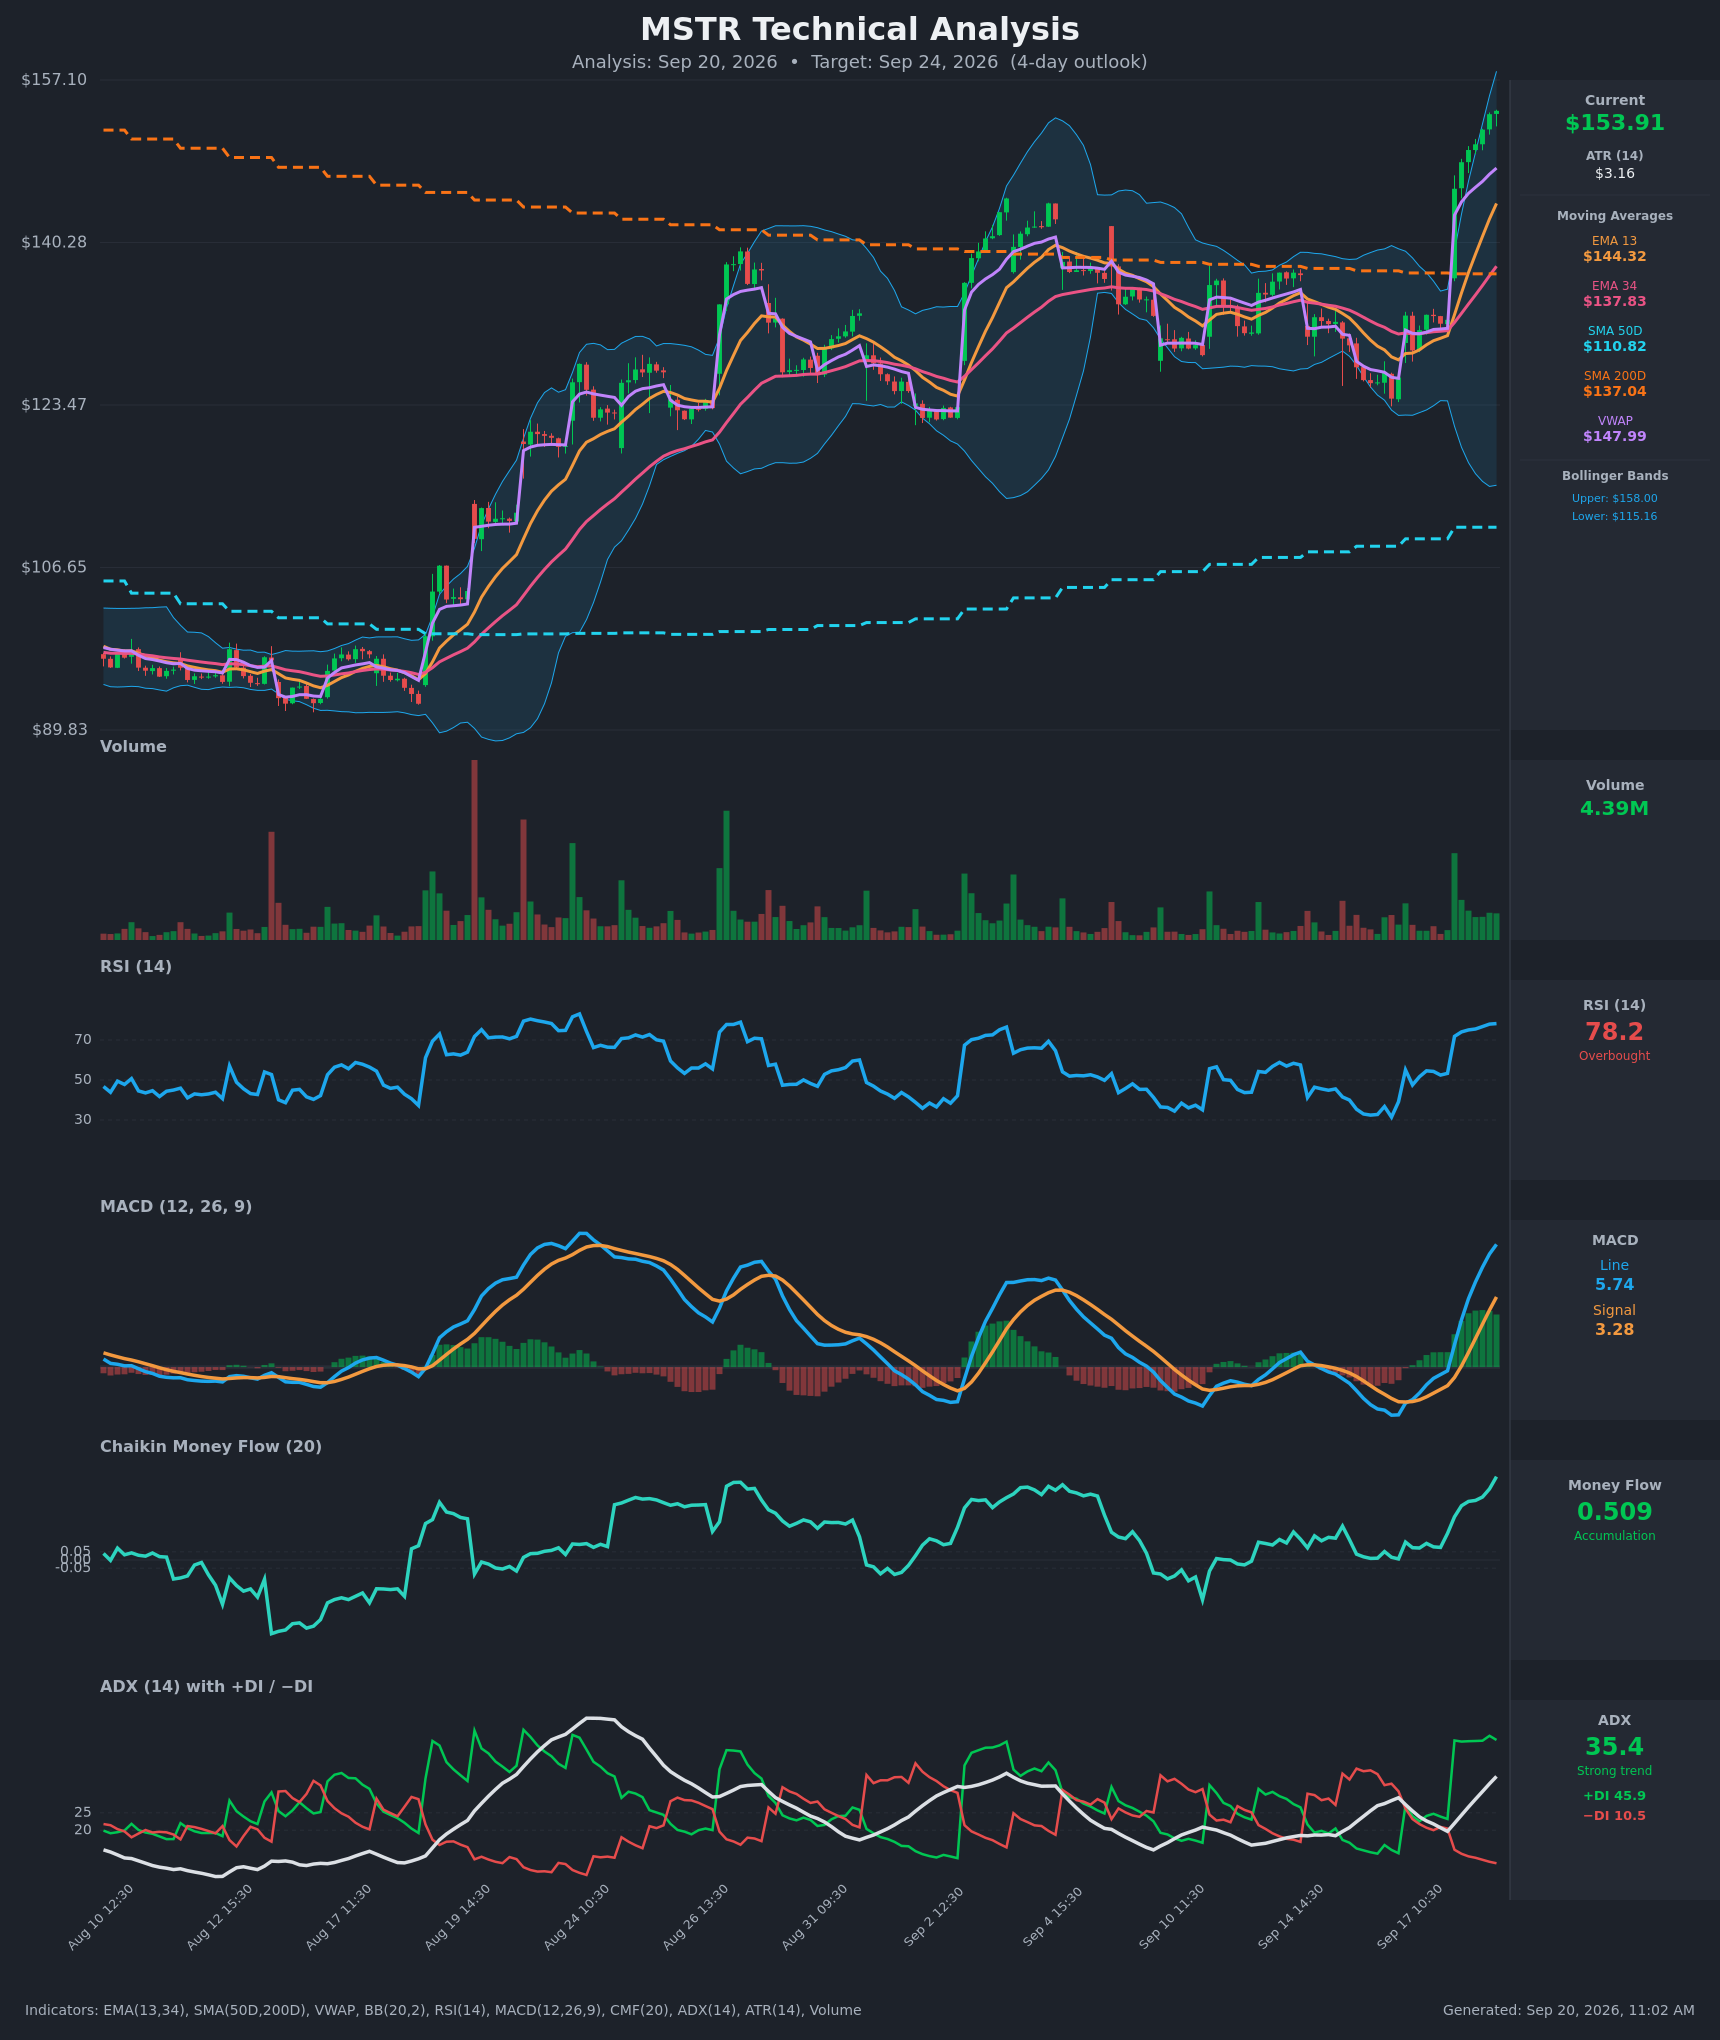
Model vs. Market: The options market implies $138.77–$169.07 into September 25; the 5-day technical model targets $158.50 inside a much tighter $148.50–$161.00 band. The chart model is far more confident about both direction and magnitude than the options chain, which is bracing for a nearly ±10% two-sided move — and given that realized volatility is running at 107%, the wide options range is the more honest one. That gap argues for structures that profit from a moderate move up rather than a precise one.
The TA did one concrete thing below: it pulled the short strike of the bullish spread in toward $162.50 rather than reaching for the top of the implied range.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If MSTR pushes above $160.00: That is the first genuinely heavy overhead strike on the September 25 expiration (2,939 calls open) and a top-five gamma pile chain-wide. Heavy call open interest overhead tends to slow rallies as hedging flows lean against the move; above it, positioning thins out quickly until the $165.00 strike cluster and the $169.07 upper implied rail. Note that both chart models put their own resistance near $158.00, which sits just under this level.
If MSTR drifts between $147.00 and $160.00: This is the base case the positioning supports. Max pain for the week sits at $135.00 — well below spot and outside the implied range — so the usual "expiration gravitates toward max pain" story would require an 12% slide and is a weak pull from this distance. Far more relevant is the $141.00 call wall now sitting below spot: with 12,109 deep-in-the-money calls there, and a positive estimated gamma regime for the week, hedging flows tend to cushion dips back toward that zone rather than accelerate them.
If MSTR breaks below $144.92: The nearest swing shelf gives way and the map thins to $139.78, the $138.77 lower implied rail and the 200-day average at $137.04. Spot sits unusually far above the estimated gamma flip level (~$55) for this name, so the amplifying-hedging scenario isn't in play — this would be a plain unwind of a two-day, 17.5% gap, not a structural break. It is also the branch where the bullish read is simply wrong.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-09-18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bullish: Sep 25 $155 / $162.50 long call spread
- Trade: Buy the Sep 25 $155 call at $5.58, sell the Sep 25 $162.50 call at $3.13. You pay the difference up front; that payment is your entire risk, and you profit if MSTR finishes above your break-even at expiration.
- Debit: $2.45 ($245) · Max profit: $505 · Max loss: $245 · Break-even: $157.45
- Why it fits: This is the structure the volatility picture argues for — with option prices running about 37 vol points under delivered movement, paying premium is the cheap side, and a debit spread caps what you pay for it. The short strike at $162.50 sits between the $160.00 call pile and the $169.07 upper implied rail, and just above both chart models' targets ($157.50 and $158.50).
- Makes sense only if: you believe the call-side flow and the confirmed uptrend carry through a stretched RSI, and you accept that a flat week loses money on a debit structure.
- Invalidated if: MSTR closes below $147.00.
- Managing it: take profits at roughly 60–70% of the $505 maximum rather than holding for the last few cents into a 0-DTE gamma scramble; exit by September 24 regardless. The short-term trend has run 17.5% in five sessions, so earlier profit-taking beats patience here.
- Liquidity note: the $155 calls traded 5¢ wide (about 0.9% of mid) on 35,926 contracts — as good as this chain gets; the $162.50 calls are 15¢ wide (~4.8%), so work the spread as a package rather than legging in.
- Analyze this position →
If you lean bearish: Sep 25 $150 / $140 long put spread
- Trade: Buy the Sep 25 $150 put at $4.00, sell the Sep 25 $140 put at $1.13. Again a debit: you pay up front, and that is the whole risk.
- Debit: $2.87 ($287) · Max profit: $713 · Max loss: $287 · Break-even: $147.13
- Why it fits: it's the disciplined way to fade an overbought two-day gap without shorting 107%-realized-vol stock. The break-even lands essentially on the $147.00 invalidation level, and the short strike sits at the lower implied rail region near the $138.77 boundary. The same thin-premium argument that favors buying calls favors buying puts — this is not an expensive hedge right now.
- Makes sense only if: you read RSI 78.2 and a $12.92 gap above the week's heaviest call strike as exhaustion rather than continuation. Note this fights the options flow, the skew and both chart models.
- Invalidated if: MSTR closes above $160.00.
- Managing it: this is a fast-decaying 7-day position — close at 50% of the maximum or by September 23 if the pullback hasn't started.
- Liquidity note: the $150 puts traded 10¢ wide (2.5% of mid) on 7,906 contracts, the $140 puts 4¢ wide on 14,039 — both easy fills.
- Analyze this position →
If you expect the range to hold: Sep 25 $140/$135 – $167.50/$172.50 iron condor
- Trade: Sell the $140 put at $1.13 / buy the $135 put at $0.56, and sell the $167.50 call at $2.13 / buy the $172.50 call at $1.44, all Sep 25. You collect the credit up front and keep it if MSTR finishes between the short strikes.
- Credit: $1.26 ($126) · Max profit: $126 · Max loss: $374 · Break-evens: $138.74 and $168.76
- Why it fits: the break-evens land almost exactly on the options-implied rails ($138.77 and $169.07), so you are being paid for the market's own boundary rather than guessing one. The estimated positive gamma regime for this expiration supports the dampening case.
- Health warning: you're selling premium that hasn't been rich lately — quite the opposite. Options are priced roughly 37 vol points below what MSTR has actually delivered, a 1st-percentile reading against this stock's own recent history. A $126 credit against $374 of risk on a name realizing 107% volatility is a thin edge at best, and the mechanical reason the condor looks wide is that the underlying really has been moving that much.
- Makes sense only if: you specifically expect the post-gap consolidation both chart reports describe, and you size it small.
- Invalidated if: MSTR closes outside $138.74–$168.76 — at that point the position is at or past a break-even and should be closed, not defended.
- Managing it: close at 50% of the credit; exit the tested side outright rather than rolling into an expiration week on a 107%-vol name.
- Liquidity note: the $140 puts are 4¢ wide and the $135 puts 2¢; the $167.50 calls 9¢ (4.3% of mid). The $172.50 long call is the weak leg at 9¢ on a $1.44 mid (~6.3%) — expect to give up a few cents there.
- Analyze this position →
If none of these: no trade
There is an honest case for sitting this one out. MSTR has moved 17.5% in five sessions and 37.0% in a month; a 7-day option on that stock is a coin flip with a spread attached, and the implied range is nearly ±10% wide for a reason. Income-focused traders in particular should note that the usual reason to show up — rich premium — is absent: IV rank 26.5 and a 1st-percentile volatility risk premium mean credit sellers are being underpaid relative to how much this stock actually moves, so standing aside genuinely beats selling premium here. If you have no view on whether a vertical two-day gap continues or unwinds, the October expirations will still be there once realized volatility and implied volatility reconverge.
6 · Quick FAQ
What is MSTR's expected move into September 25? About ±$15.15, or ±9.84% — a $138.77 to $169.07 range around the $153.92 close, per the options market's straddle pricing as of September 18.
Is MSTR expected to go up or down over the next five days? Options positioning as of September 18 leans slightly bullish — put open interest drained to 0.48 puts per call while 25-delta calls now cost 8.5 vol points more than puts — but that's a read of what traders have already done, not a forecast. The actionable map is the $138.77–$169.07 range plus the $144.92 support and $160.00 resistance levels.
Are MSTR options expensive right now? Two lenses, same answer. IV rank of 26.5/100 says option prices are lower than about 73% of the past year's readings; on top of that they're running roughly 37 vol points below the movement MSTR has actually delivered over the past 20 days — thinner than about 99% of this stock's own recent readings. Options here are cheap, which favors buying premium over selling it.
Where is MSTR's biggest options support and resistance? For the September 25 expiration, the put wall is $95.00 and the call wall is $141.00 — but that call wall now sits below the $153.92 spot, so the first meaningful overhead pile is the $160.00 strike, and the nearest structural support is $144.92.
What invalidates this week's read? A close below $147.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for MSTR, 2026-09-18, generated 2026-09-20T11:02:35.862Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.