MU Options Are Pricing a $117 Move by October 2 — Positioning Still Leans Bullish
Micron's options market implies a $965.18–$1,199.38 range into the October 2 expiration, with the September 28 earnings report sitting inside that window. Here is what the positioning shows, where the key levels are, and three defined-risk ways to trade it.
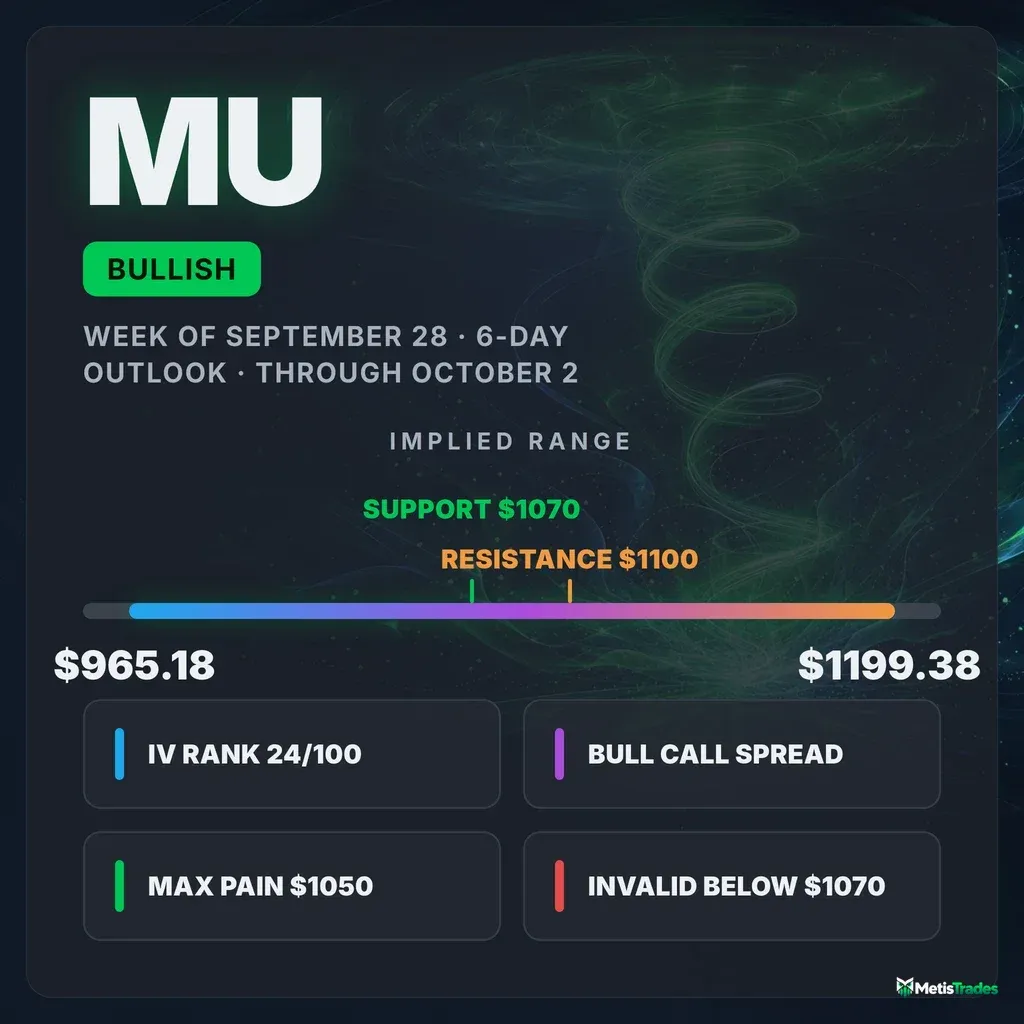
The options market implies a $965.18–$1,199.38 range into the October 2 expiration. Here is what's driving it, where the levels sit, and three defined-risk ways to trade it.
Published Saturday, September 26, 2026 · Data as of Friday, September 25, 2026 close
Explore the live MU options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Bullish |
| Options-implied range (into October 2) | $965.18 – $1,199.38 (±10.82%, about ±$117.10) |
| Major support | $1,070 (October 2 put wall) |
| Major resistance | $1,100 (October 2 call wall) |
| Max pain (October 2) | $1,050 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $1,010 |
| Volatility condition | Falling — IV rank 23.58/100 · premium rich: options priced ~10 vol pts above delivered movement (earnings-inflated) |
| Next earnings | September 28 (after close) — before the October 2 expiration |
| Technical check | Confirms (bullish; 3-day chart-model target $1,090, range $1,063–$1,105; 6-day target $1,097, range $1,049–$1,114) |
| Best-fitting strategy | Bull call spread (October 2 $1,080/$1,100), if you accept earnings-gap risk |
| Analysis invalidated if | MU closes below $1,070 |
1 · What matters today
Our read of MU's options positioning is bullish. The main reason: new money is leaning to the call side across nearly every measure we track — call buying, fresh open contracts, and sentiment in both near-dated and one-month options — and the stock has climbed 6.5% over the past five sessions. Options are pricing a move of about $117 in either direction by October 2, which puts the implied range at roughly $965 to $1,199. Overhead, the $1,100 strike holds the biggest pile of open call contracts for that expiration and tends to act like a ceiling. The level that changes the picture is $1,070: a close below it breaks the nearest put-side support and undercuts the bullish read. With the September 28 earnings report inside this window, options past that date carry a large extra premium. The chart-based technical models also lean bullish.
2 · What the options market is pricing
What changed this week
MU finished Friday at $1,082.28, up 6.54% over five trading days and 15.7% over twenty. Options flow leaned the same way. For every call traded on Friday, only 0.47 puts changed hands. The seven-day average is 0.52 and the 14-day average is 0.61, so traders kept tilting toward calls. The open-interest ratio (contracts currently held open) sat at 0.49 puts per call, roughly in line with its seven-day average of 0.49 but well below the 14-day average of 0.66. Put hedges were shed aggressively during mid-September and have not come back.
Implied volatility, the market's estimate of how much MU will move, baked into option prices, rose 2.0% over five days but fell 3.8% on Friday alone. The biggest forward-looking open-interest build was in the October 2 $1,050 calls, which added 1,518 contracts to reach 4,229. The October 2 $1,060 calls added 1,171, and the $1,100 calls added 679 to reach 7,502.
Into Friday's expiration, the now-settled September 25 $1,120 calls added 2,654 contracts of open interest. That is history now, but it shows how far upside bets were reaching.
The momentum read also turned back up: a bullish crossover fired on September 22, reversing the September 14 bearish turn. The short- and long-term trend reads agree. The past week, the past month, and the past two-plus months (price up 26.8% over roughly 50 sessions) all point the same direction.
Expected move
The expected move is the move the options market is pricing in, derived from what at-the-money straddles cost. For the October 2 expiration, that works out to ±$117.10, or ±10.82%, around the $1,082.28 snapshot price. Here is the ladder:
| Expiration | Implied move | Range around $1,082.28 |
|---|---|---|
| September 28 | ±3.09% | $1,048.84 – $1,115.72 |
| October 2 | ±10.82% | $965.18 – $1,199.38 |
| October 9 | ±12.70% | $944.83 – $1,219.73 |
| October 23 (~1 month) | ±16.63% | $902.30 – $1,262.26 |
The ladder is anything but smooth. The implied move more than triples between September 28 and October 2, then grows only modestly after that. That step-up is the earnings report, covered below.
Volatility
MU's at-the-money implied volatility is 60.17%. That sounds high in absolute terms, but for this stock it is low.
- IV rank is 23.58/100. IV rank shows where today's IV sits versus the past year, so today's reading is cheaper than about 76% of the past year's readings.
- IV percentile is 14.3. Only about 14% of the past year's days had lower IV.
- IV is below its averages. It sits under its 30-day average of 62.5% and far below its 90-day average of 84.7%, and it is down 7.5% over 30 snapshots.
The front-month term-structure read, which compares option prices across expiration dates, is unavailable today (expiry day). The per-expiration table above tells the story anyway.
On the stock-movement side, 20-day realized volatility is 50.2%. That is running well below this stock's own recent norm. Here "norm" means compared against MU's own recent history, so "unusually low" is unusual for MU, not versus the broader market. MU has been trending more smoothly than it usually does.
Premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much MU has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them. Right now, options are priced about 10 vol points above what MU has delivered over the past 20 days. That sits in the 89th percentile of this stock's own recent readings, meaning it is richer than about 89% of them. The gap peaked near 15 points on September 22 and has eased since.
Normally, IV rank 24 plus an 89th-percentile premium over delivered movement would argue for collecting premium. This week it doesn't carry that meaning: much of that richness is the market pre-pricing the September 28 report, not free premium. Selling it means selling the earnings gap.
Earnings on the calendar
MU reports on September 28, after the close. That lands after the September 28 expiration settles but before October 2. Options that expire after a scheduled report price in its extra jump risk, and the chain shows it plainly. September 28 options carry about 34% implied volatility (±3.09%). October 2 options carry about 78% (±10.82%). That jump is the market bracing for the report. For the record, each of the last four reports beat expectations; the most recent came in at $24.89 per share against an expected $20.98.
Skew and sentiment
Skew describes the fact that puts and calls the same distance from the stock price don't cost the same; when puts are pricier, traders are paying up for crash protection. The broad 25-delta reading is unavailable today because the call side could not be priced cleanly. For context, the 60-day norm for MU is about 1.7 vol points in favor of calls, so this name normally carries a mild upside tilt rather than crash-protection demand. Within one-month options, the same comparison shows calls running about 4.4 vol points richer relative to puts than their recent baseline. Traders are paying extra for upside, not downside.
Flow and sentiment tell the same story:
- Put/call volume is 0.47. The put/call ratio measures put activity relative to calls, and anything above 1 means puts dominate. Friday's call-buying pace was unusually heavy for this name compared with its own history.
- Unusual contracts leaned to calls. Among contracts that cleared a high peer-relative volume bar, calls outnumbered puts 16 to 10.
- Short-dated sentiment is positive but cooling. Sentiment reads +22 in 0–7 day options and +41 in 7–30 day options, with every expiration bucket leaning bullish. Both readings are down from seven-day averages of +40 and +50.
The direction is intact, but the intensity has come off the September 22 peak.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $1,255 | Also the upper swing-resistance marker; 13.8% above the close |
| Heavy call strike (whole chain) | $1,200 | 15,341 open calls across expirations, most in October 16 |
| Implied range top (October 2) | $1,199.38 | Upper edge of the one-standard-deviation move |
| Call wall (October 2 and whole chain) | $1,100 | 7,502 open calls for October 2 and 34,832 chain-wide; also the largest gamma strike — a likely magnet or ceiling |
| Swing resistance | $1,089.29 | Heuristic pivot cluster just above spot |
| Spot (snapshot / close) | $1,082.28 | Reference price for everything chain-derived |
| Put wall (October 2) | $1,070 | 1,001 open puts — the nearest put-side support and our invalidation level |
| Max pain (October 2) | $1,050 | Where the most option value would expire worthless; also the second-largest gamma strike |
| Swing support | $1,038.01 | First heuristic support cluster below |
| Gamma flip (estimate) | ≈ $1,010 | One rough estimate of where dealer hedging shifts from cushioning to amplifying |
| Put wall (whole chain) | $1,000 | 9,497 open puts chain-wide, concentrated in October 16 |
| 20-day moving average | $994.14 | Price is 8.9% above it |
| Implied range bottom (October 2) | $965.18 | Lower edge of the one-standard-deviation move |
| 50-day moving average | $941.62 | Price is 14.9% above it |
The October 2 put wall ($1,070) and the whole chain's heaviest put strike ($1,000) disagree. The $1,000 pile sits mostly in later expirations, so for this window the $1,070 level is the one that applies. The call wall is $1,100 in both views.
Positioning and unusual flow
Market makers hedge the options they've sold. One rough estimate suggests they are in a positive-gamma regime, both chain-wide and for October 2 specifically, and in that regime their hedging tends to dampen moves rather than amplify them. That fits the corridor between $1,070 and $1,100, with max pain at $1,050 as a gravity point below. Spot sits about 7.6% above the estimated flip level near $1,010, roughly typical for this name. The caveat is that positive gamma cushions normal trading days; it does not stop an overnight earnings gap.
Notable flow on Friday:
- October 2 $1,100 calls. About $24.7 million in premium traded (6,317 contracts), the largest of any contract. That reinforces $1,100 as the week's reference ceiling.
- October 2 $1,082.50 calls. 373 contracts traded against just 6 open, about 62 times open interest. That is fresh at-the-money positioning ahead of the report.
- December 18 $1,080 puts. 1,647 contracts traded against 238 open, roughly $18.8 million in premium and top-percentile volume versus peers. Someone bought longer-dated protection even as short-dated flow leaned bullish, which looks like hedging an intact rally rather than betting against it.
3 · Technical check
Near-term chart report (target September 29): bullish, with a target of $1,090 and a projected range of $1,063–$1,105. That sits inside the options market's September 28 range of $1,048.84–$1,115.72, so it confirms the options read. The report describes a flag-style consolidation above rising short-term averages. It flags a fresh MACD bearish cross as a momentum stall rather than a reversal, and its dominant scenario is invalidated on a close below $1,070 — the same level as the October 2 put wall.
6-day chart report (target October 2): bullish, with a target of $1,097 and a projected range of $1,049–$1,114. That is well inside the $965.18–$1,199.38 options range and also confirms. It cites a strong trend read (ADX near 38, buyers firmly in control) and positive money flow as the decisive supports.
The 6-day target sits between the $1,080 long strike and the $1,100 call wall, which is why the featured bullish spread uses exactly those strikes.
Model vs. Market: The options market implies $965.18–$1,199.38 into October 2; the 6-day technical model targets $1,097, within a $1,049–$1,114 range. The chart model's range is less than a third as wide as what options are paying for, because the chain is pricing the September 28 report's jump risk while the chart reads trend. The report outcome will decide which width was right.
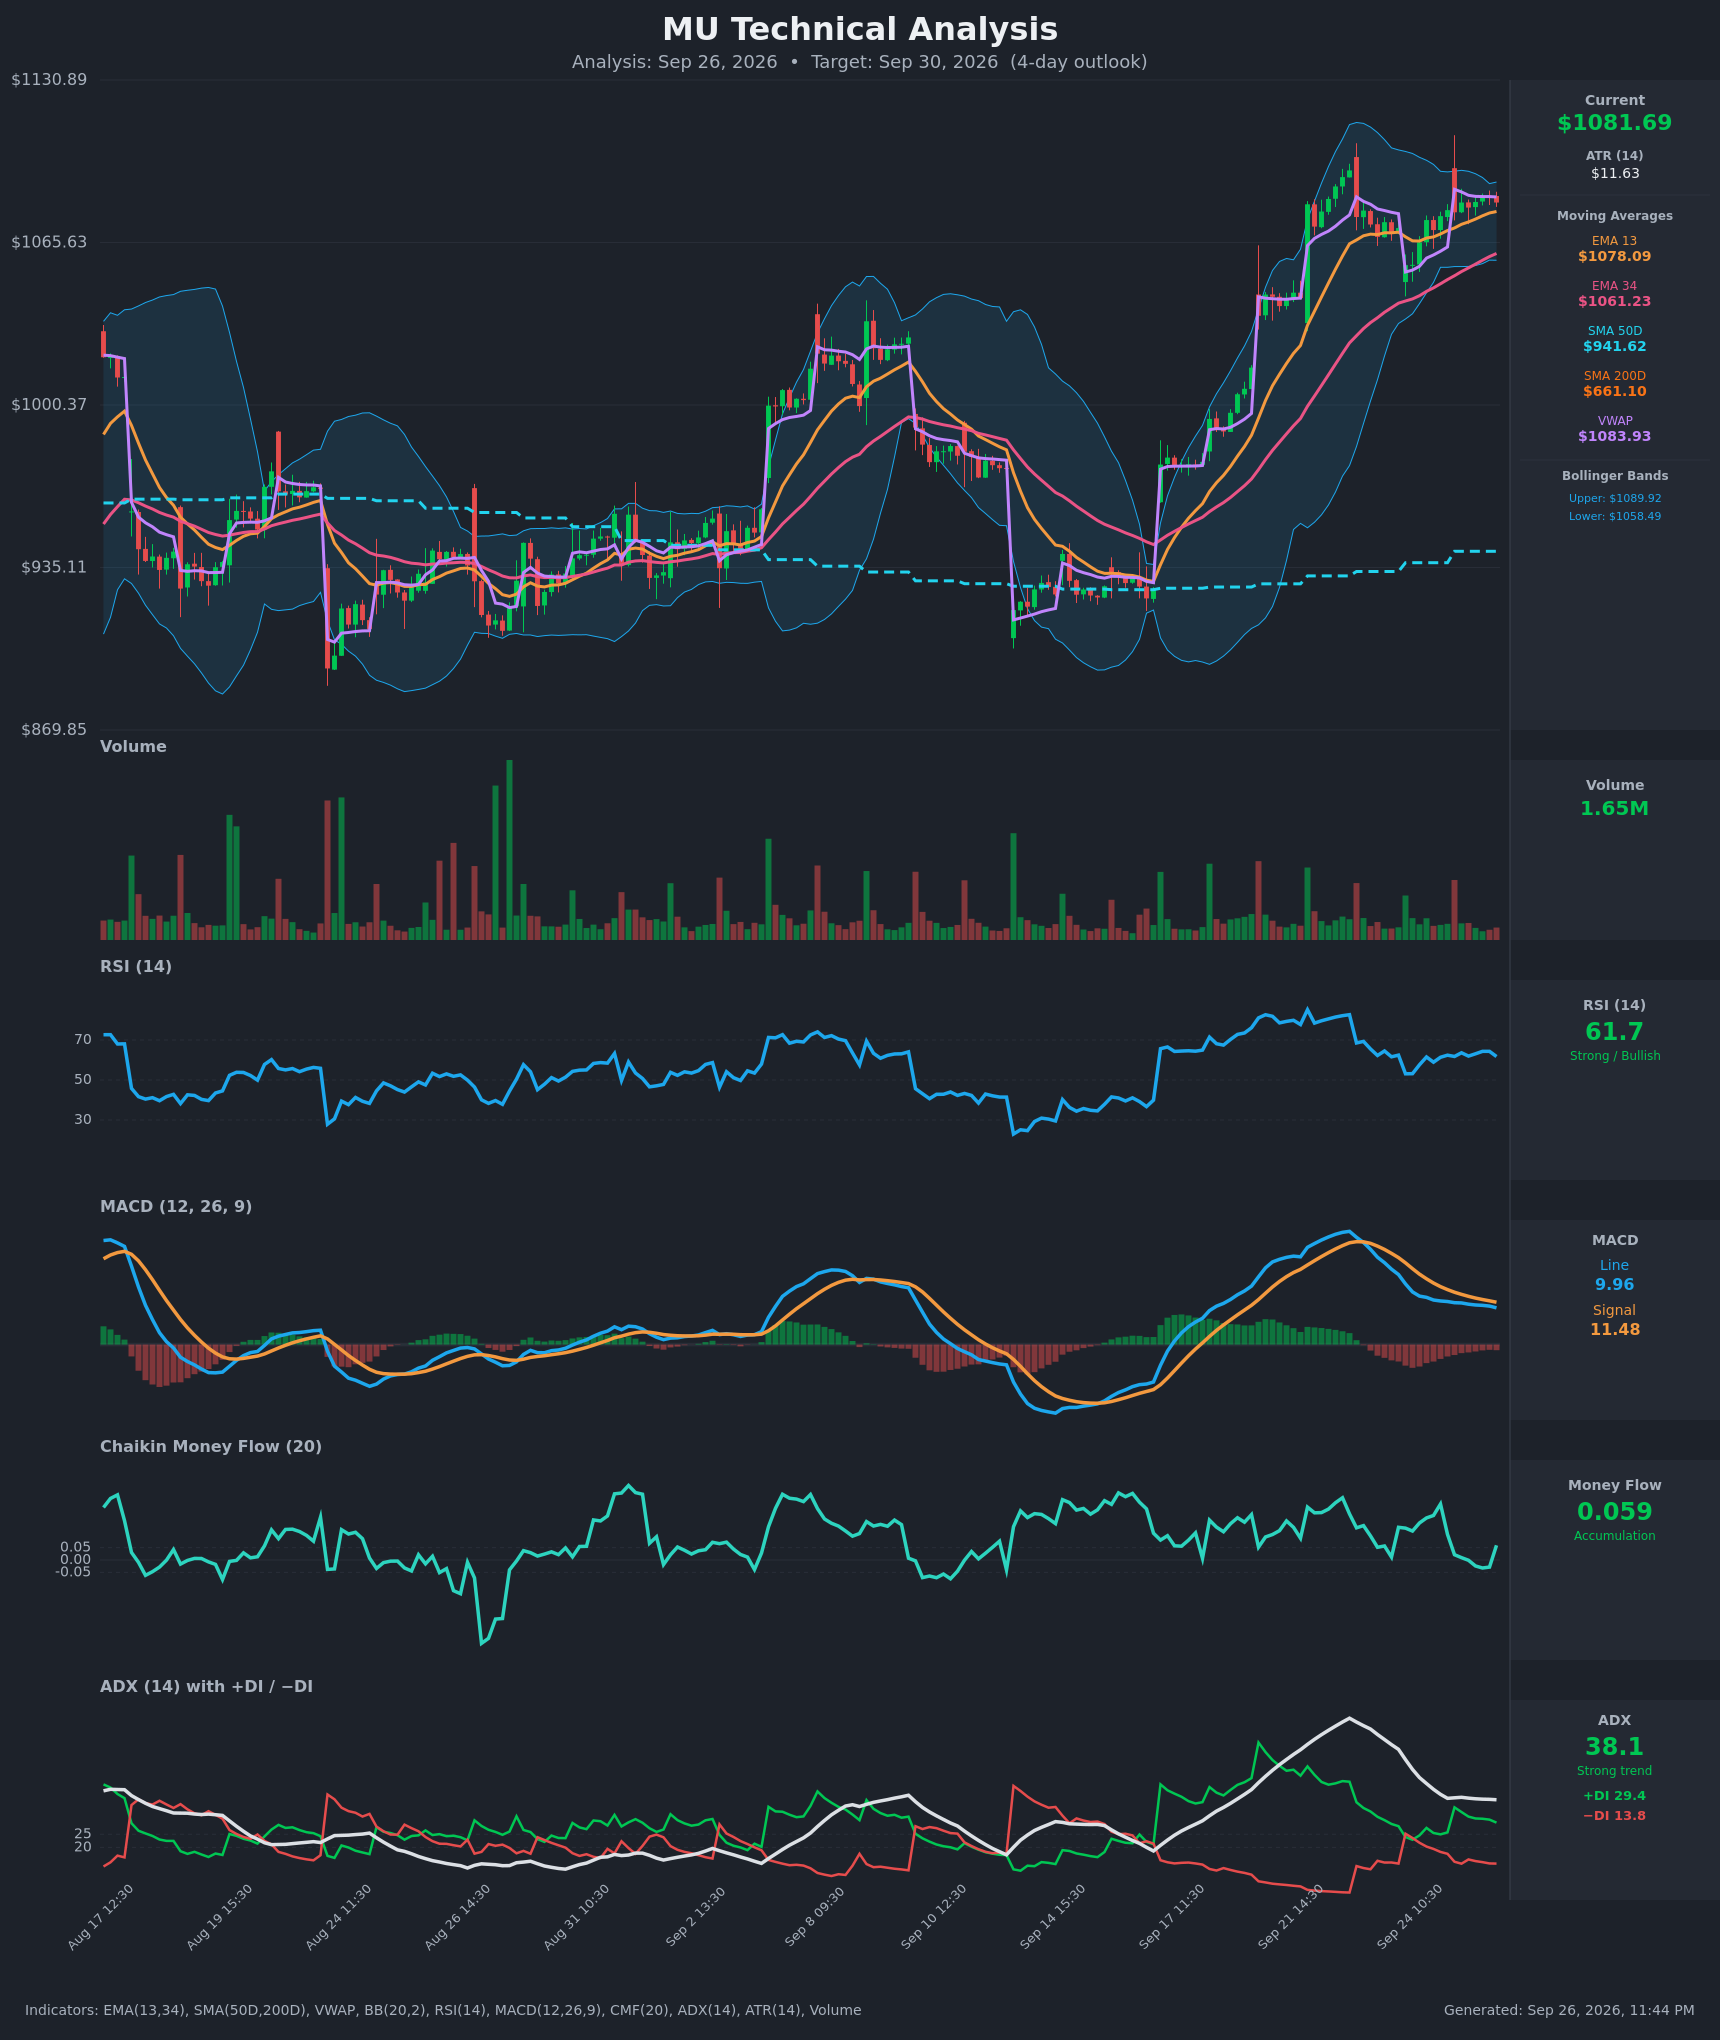
Full technical write-ups: Near-term (3-day) report → · 6-day report →
4 · Three ways the next six days can go
If MU pushes above the call wall ($1,100): The heaviest call open interest for October 2 sits at $1,100, and big call piles tend to slow rallies as hedging flows lean against them. A clean break, most plausibly on the report, leaves thinner positioning overhead until the heavy $1,200 call strike, with the implied range top at $1,199.38 nearby.
If MU drifts between the walls: This is the pin case. Positive dealer gamma and the $1,070–$1,100 corridor tend to keep price contained on normal days, and expiring open interest can pull price toward $1,050 max pain into October 2. After a report that the market is pricing at ±$117, the corridor is fragile. It is the base case only if the reaction underwhelms the pricing.
If MU breaks below the put wall ($1,070): Losing the nearest put support would invalidate the bullish read and open max pain at $1,050 and swing support at $1,038.01. Below that, the gamma flip estimate near $1,010 matters. Under that level, one rough estimate suggests market-maker hedging amplifies selling rather than cushioning it, and the whole-chain put pile at $1,000 sits just beneath.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of Friday, September 25, 2026. All structures are hypothetical unless flagged as an entered position. Verify live prices before trading — these will be stale by the open.
Every October 2 structure below spans the September 28 report. Premium in this expiration is inflated for that reason, and any position can gap through its strikes overnight. Size accordingly.
If you lean bullish: bull call spread
- Trade: Buy the October 2 $1,080 call, sell the October 2 $1,100 call
- Debit: $9.33 ($932.50 per spread) · Max profit: $1,067.50 · Max loss: $932.50 · Break-even: $1,089.33
- Why it fits: The bullish positioning read, confirmed by both chart models, targets the zone between the strikes. Selling the $1,100 call monetizes the call wall that tends to cap rallies. The spread also offsets much of the inflated event premium you'd pay for a lone call.
- Makes sense only if: You expect MU to hold above about $1,090 into October 2 and accept a binary report inside the trade.
- Invalidated if: MU closes below $1,070.
- Earnings exposure: Spans the September 28 report. Premium is inflated for that reason, and the position can gap through either strike overnight.
- Managing it: Take profits at roughly 60–70% of max profit if the report delivers early. Close on a close below $1,070 rather than hoping. Don't carry it into the final hours of October 2 if it sits near $1,100.
- Liquidity note: The $1,100 calls traded 50¢ wide and the $1,080 calls $1.85 wide on Friday, both under 4% of mid, so fills should be workable.
- Analyze this position →
If you expect the range to hold: iron condor
- Trade: Sell the October 2 $1,050/$1,035 put spread and sell the October 2 $1,110/$1,125 call spread
- Credit: $10.70 ($1,070 per condor) · Max profit: $1,070 · Max loss: $430 · Break-evens: $1,039.30 and $1,120.70
- Why it fits: The short put sits at max pain ($1,050). The short call sits just above the $1,100 call wall. Positive dealer gamma tends to contain price between them on ordinary days. This is a direct bet that the report underwhelms the ±$117 the market is pricing.
- Makes sense only if: You believe the chain is overpricing the report's reaction. The rich premium over delivered movement is the case for it; the fact that that richness is earnings-driven is the case against.
- Invalidated if: MU closes below $1,050 or above $1,110.
- Earnings exposure: Spans the September 28 report. You are selling the event premium itself, and a move anywhere near the implied size puts the position at max loss.
- Managing it: Close at 50% of the credit, which is plausible the morning after a muted report. If either short strike is breached after the report, close rather than defend.
- Liquidity note: The $1,050 and $1,035 puts traded 75¢ and 60¢ wide and the $1,125 calls $1.05 wide. The $1,110 calls were $1.70 wide (about 4.9% of mid), right at our slippage threshold, so work the order.
- Analyze this position →
If you lean bearish: bear put spread
- Trade: Buy the October 2 $1,075 put, sell the October 2 $1,035 put
- Debit: $17.30 ($1,730 per spread) · Max profit: $2,270 · Max loss: $1,730 · Break-even: $1,057.70
- Why it fits: This is the counter-thesis trade. It pays if a disappointing report takes out the $1,070 put wall and pulls price through $1,050 max pain toward the $1,038.01 swing support. The spread caps what you pay for inflated event volatility.
- Makes sense only if: You're willing to fight call-heavy flow and an aligned uptrend, or you want a defined-risk hedge on long stock through the report.
- Invalidated if: MU closes above $1,100.
- Earnings exposure: Spans the September 28 report. Premium is inflated for that reason, and a gap in either direction resolves most of the trade overnight.
- Managing it: Take profits near $1,040 rather than waiting for the full width. Exit on a close above $1,100.
- Liquidity note: The $1,075 puts traded $1.90 wide (about 4.5% of mid) and the $1,035 puts 60¢ wide. Workable, but use limit orders.
- Analyze this position →
If none of these: no trade
Standing aside is a legitimate choice this week. Every structure anchored to October 2 carries the September 28 report. The premium that looks rich — about 10 vol points over delivered movement, in the 89th percentile of MU's own recent readings — is mostly the market charging for that gap risk, not a free edge. At the same time, IV rank of 23.58 says MU's options are cheap by their own one-year standard, so neither side has a clean volatility advantage. If you want the bullish positioning without the report, the September 28 expiration settles before the after-close release, though with only one session left it's a very different trade. Otherwise, waiting until after the report and reassessing the $1,070/$1,100 corridor is a perfectly defensible plan.
6 · Quick FAQ
What is MU's expected move this week? About ±$117.10 (±10.82%) into the October 2 expiration, based on straddle pricing as of the September 25 close. That implies a $965.18–$1,199.38 range.
Is MU expected to go up or down over the next week? Options positioning as of September 25 leans bullish, with call-heavy flow, fresh call open interest, and positive sentiment across expirations. That is a read of what traders have done, not a forecast. The actionable map is the $965.18–$1,199.38 range and the $1,070 support and $1,100 resistance levels.
Are MU options expensive right now? IV rank of 23.58/100 says option prices are lower than about 76% of the past year's readings. On top of that, they're running about 10 vol points above the movement MU has actually delivered, richer than 89% of this stock's own recent readings. Most of that extra is the September 28 earnings report being priced in.
When is MU's next earnings report? September 28, after the close. That is after the September 28 expiration settles but before October 2, which is why October 2 options carry roughly triple the implied move.
Where is MU's biggest options support and resistance? For the October 2 expiration, the put wall is $1,070 and the call wall is $1,100. Max pain is $1,050.
What invalidates this week's read? A close below $1,070.
Methodology & disclosures. Data: end-of-day options-chain snapshot for MU, 2026-09-25, generated 2026-09-26T23:44:22.435Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. Earnings dates and reported results are from the data provider's earnings feed as of 2026-09-26T23:44:22.435Z; report dates can change. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.