NFLX Options Are Pricing a $3.24 Move Into Friday — The Chart Model Sees $78.60
The options market implies a $74.16–$80.64 range for Netflix into the September 18 expiration, with max pain at $77 and the heaviest call open interest stacked at $80. Here's what the positioning actually says, and three defined-risk ways to trade a four-day window.

The options market implies a $74.16–$80.64 range into the September 18 expiration; here's what's driving it, where the walls sit, and three defined-risk ways to trade the next four days.
Published Monday, September 14, 2026 · Data as of Friday, September 11, 2026 close
Explore the live NFLX options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into September 18) | $74.16 – $80.64 (±4.19%, or ±$3.24 around a $77.40 close) |
| Major support | $65.00 — the September 18 expiration's put wall |
| Major resistance | $80.00 — the September 18 expiration's call wall |
| Max pain (September 18) | $77.00 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $83 (estimate) |
| Volatility condition | Low and steady — IV rank 17/100 · premium thin: options priced about 1.4 vol points below delivered movement |
| Next earnings | October 20, 2026 (after close) — well after the September 18 expiration |
| Technical check | Mixed (bullish, 2-day and 4-day chart models) |
| Best-fitting strategy | September 18 $77/$80 call debit spread, if you side with the chart model's bullish lean |
| Analysis invalidated if | NFLX closes below $75.00 |
1 · What matters today
Netflix closed Friday, September 11 at $77.40 after a rough five sessions — down 6.4% — and the options market is pricing a further $3.24 move up or down through the September 18 expiration. That's the move the options market expects, derived from what straddles cost, and it puts the band at $74.16 to $80.64.
Our read of the flow lands squarely neutral. Positioning has a mild bullish pulse — Friday was heavily call-tilted, and the biggest single build in open contracts was in the September 18 $77 calls — but price momentum is firmly negative after the slide, and the two cancel out. Max pain, the price at which the most option value would expire worthless, sits at $77.00, almost exactly where the stock closed.
The level that changes the picture is $75.00: the chain's heaviest put strike and the floor of the current shelf. Two short-dated chart models both lean bullish, but their targets fit comfortably inside what options already price.
2 · What the options market is pricing
What changed this week
The move was in the stock, not the vol. NFLX fell 6.4% over five trading days while at-the-money implied volatility — the market's estimate of how much NFLX will move, baked into option prices — rose only 6.0% over the same stretch, to 32.3%. That's still 8.5% below where it sat a month ago and a hair under its own 30-day average of 32.5%. Nobody panicked.
Underneath, hedging built quietly. The put/call ratio in open contracts — how many puts are held open for every call — climbed from 0.80 to 0.88 over five sessions, against a 14-day average of 0.83. Then Friday cut against it hard: put volume ran at just 0.29 per call, versus a 7-day average of 0.40 and a 14-day average of 0.42. That is an unusually call-heavy session for this name by its own recent standards. The single biggest change in open contracts was the September 18 $77 calls, which added 4,502 contracts to 12,130 — traders positioning right at the money for this week, not hedging for a crash.
Zoom out and the horizons disagree in an instructive way: the past week's 6.4% drop sits against a stock that is down only 0.8% over the last 20 sessions and up 4.3% over the last 50. The short-term read is decisively negative while the one- and two-month reads are flat. That mix argues for short-dated structures and early profit-taking rather than anything you intend to hold for weeks.
Expected move
Into the September 18 expiration, options price a ±4.19% move — about $3.24 either side of Friday's $77.40 close, or a $74.16–$80.64 band.
| Expiration | Implied move | Range around $77.40 |
|---|---|---|
| September 18 | ±4.19% | $74.16 – $80.64 |
| September 25 | ±6.04% | $72.73 – $82.08 |
| October 2 | ±7.44% | $71.64 – $83.16 |
| October 16 | ±10.71% | $69.11 – $85.69 |
The rungs step up smoothly — roughly in line with the square root of time — which tells you the chain sees no single dislocating event inside the next month. The kink lives one rung past this table, and the earnings note below explains it.
Volatility
At-the-money implied volatility across the chain is 32.3%, with an IV rank of 17/100 — meaning today's IV is cheaper than roughly 83% of the past year's readings. The September 18 rung itself prices slightly lower, at 30.2%. IV is down 1.0% on the day, up 6.0% over five sessions, and down 8.5% over 30, sitting just under its 30-day average of 32.5% and well under its 90-day average of 36.0%. The front-month read is unavailable today (the chain's nearest expiration settled on the as-of date), so there's no clean term-structure comparison across dates this session.
Realized movement is the more interesting half. Twenty-day realized volatility is 33.7%, and the five-day-over-twenty-day ratio is 1.28 — movement over the last week is running about 28% hotter than the stock's own monthly baseline, above its own norm.
Premium rich or cheap? The volatility risk premium — the gap between how much movement options are priced for and how much NFLX has actually delivered — is currently negative, about 1.4 vol points. Option sellers have been collecting less than realized movement cost them. That gap sits at the 38th percentile of this stock's own recent readings, meaning it has been richer than today on about 62% of recent days. The path matters too: a week ago the gap was near 5.6 vol points negative, and on September 4 it was 7.1 points negative, so premium has been getting less cheap as IV firmed and the post-slide realized vol begins to roll forward. Bottom line: an IV rank of 17 paired with a below-norm premium over delivered movement favors owning premium over collecting it this week. With the next report more than a month out, none of that richness reading is earnings-distorted.
Earnings on the calendar
Netflix reports next on October 20, after the close — 36 days out, and comfortably beyond every structure in this article. You can see the chain bracing for it exactly one rung past the ladder above: the implied move jumps from ±10.71% at the October 16 expiration to ±14.06% at October 23, the first expiration that contains the report. That step-up is the earnings premium, not a view on direction. For context on the last two quarters in dollars: the July 16 report came in at $0.80 per share against a $0.79 estimate, while the April 16 report landed at $1.23 against $1.32.
Skew and sentiment
Skew — the fact that puts and calls the same distance from the stock price don't cost the same — is running the unusual way for a single name. Twenty-five-delta calls are marked at 33.1% implied volatility versus 31.9% for equidistant puts, so calls carry about 1.2 vol points more than puts. Traders are not paying up for crash protection here; if anything they're paying up for upside. That reading is almost exactly on this stock's own 60-day norm of −1.3 vol points, though it is notably more call-rich than the past three days' average of −0.4.
Flow-wise, the near-dated end leans mildly positive: sentiment in options expiring within a week scores +15 and in the 7–30 day bucket +11, while the 60–120 day bucket sits at −16. The overall regime reads calm — every bucket inside ±20. Friday's put/call volume ratio of 0.29 was well below this name's own norm, i.e. an unusually heavy call-buying pace, while the price-momentum input was unusually weak versus its own history. Two honest observations pointing opposite ways, which is precisely why the bias lands neutral.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 200-day moving average | $86.24 | Price sits 10.25% below it — the longer-term trend is still down |
| Swing resistance | $83.03 | Heuristic swing-pivot cluster from recent price structure |
| Dealer gamma flip (estimate) | $83.00 | One rough estimate of the level below which hedging stops cushioning moves |
| Swing resistance | $81.16 | Early-September consolidation shelf |
| Top of implied range | $80.64 | Upper rail of what options price through September 18 |
| Call wall (September 18) | $80.00 | 27,672 contracts of call open interest — the heaviest call strike for this expiration, and also the whole chain's heaviest call strike at 91,986; big piles like this often slow rallies |
| 100-day moving average | $80.06 | 3.32% overhead |
| 20-day moving average | $79.44 | 2.57% overhead — first trend hurdle |
| Swing resistance | $78.44 | Nearest structural cap |
| Friday's close | $77.40 | Reference price for everything above and below |
| Max pain (September 18) | $77.00 | Where the most option value would expire worthless — expirations sometimes gravitate toward it |
| 50-day moving average | $75.70 | 2.24% below price — the nearest trend support |
| Whole chain's heaviest put strike | $75.00 | 64,910 puts open across all expirations — the practical downside shelf, and the invalidation line |
| Bottom of implied range | $74.16 | Lower rail of what options price through September 18 |
| Swing support | $73.76 | Heuristic swing-pivot cluster |
| Swing support | $70.86 | Deeper structural shelf |
| Put wall (September 18) | $65.00 | 20,055 puts open — far out of the money; this expiration's put protection is parked well below the market |
| 52-week low | $65.08 | The stock sits 18.9% above it and 38.3% below the 52-week high of $125.35 |
One disagreement worth naming: the September 18 expiration's own put wall sits at $65.00, but the whole chain's heaviest put strike is $75.00. That's a real difference, not a rounding artifact — for this week specifically, there is no dense put shelf between $74 and the low $70s. If price loses $75, there is comparatively little open interest to act as a magnet until much lower.
Positioning and unusual flow
One rough estimate puts net dealer gamma positive for the September 18 expiration — the regime in which market-maker hedging tends to dampen moves rather than amplify them. The same estimate places its flip level at $83, above the current price, which is an awkward pairing; treat both figures as estimates, not observed dealer inventory. The practical read is simpler: the open-interest piles at $80 above and $75 below are doing more to shape this week than the sign of any gamma estimate.
Three non-expired flows stood out on Friday:
- September 18 $77 calls — 11,869 contracts traded against 12,130 open, with open interest up 4,502 on the day and about $1.82 million of premium changing hands. That is the day's single biggest money print, and it's a right-at-the-money bet on this week.
- September 18 $80 calls — 10,083 traded against 27,672 open, adding 1,608 contracts. Money continues to stack directly on the call wall, which is what makes $80 a genuine speed bump rather than just a big number.
- December 18 $78 puts — 2,351 traded against 2,545 open, roughly $1.39 million of premium. A far-dated, near-the-money put buy of that size reads like portfolio insurance for the quarter, not a bet on this week.
3 · Technical check (the 20%)
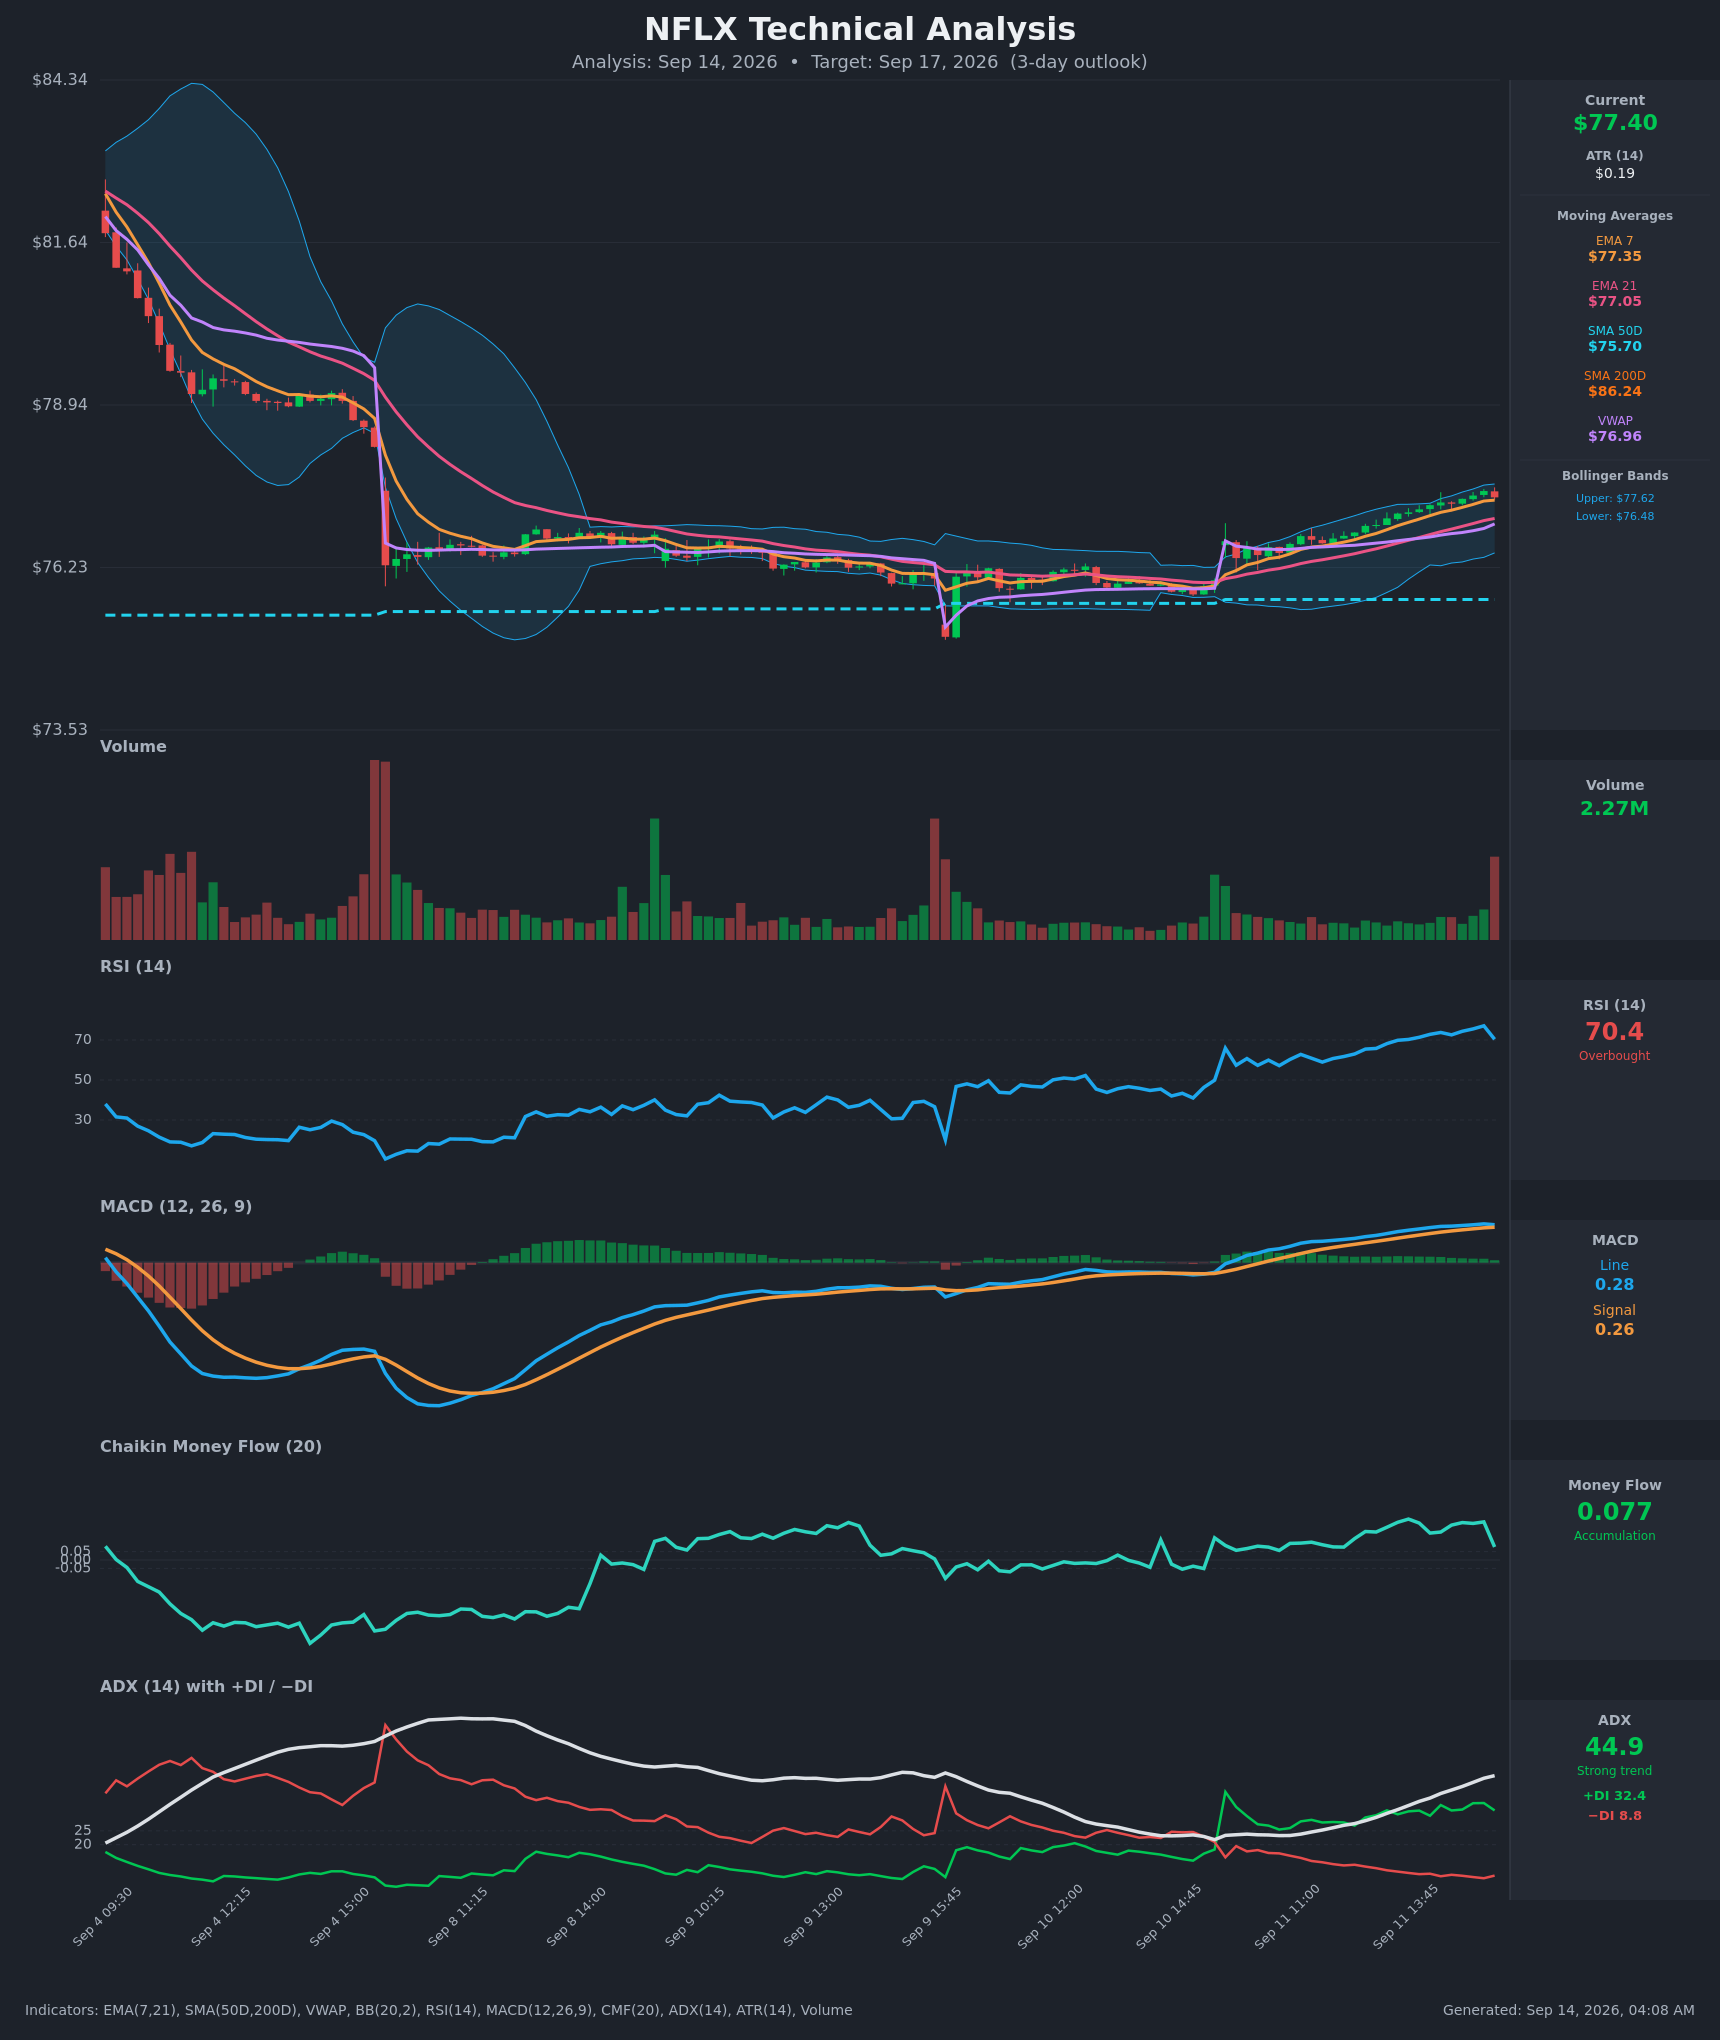
Both chart models lean bullish, and both fit inside what options already price. The 2-day model (target date September 16) sets a target of $78.10 with a projected range of $76.40–$78.75, resting on an ADX of 44.9 with +DI well above −DI — a strong, established short-term uptrend — though it flags RSI above 70 as stretched. The 4-day model (target date September 18) targets $78.60 with a projected range of $75.90–$79.60, citing a fresh MACD bullish crossover and Chaikin Money Flow at +0.150, a solid accumulation reading after the early-September flush.
Classified against the options read, both are Mixed: the direction cuts against our neutral options bias, but every one of their numbers lives inside the $74.16–$80.64 band the options market is already pricing. In other words, the chart models are calling for a smaller, tidier path than the options market is willing to rule out — which is not a contradiction so much as a narrower version of the same picture.
Both models put their own invalidation right beneath the market: the 2-day report kills its dominant bullish scenario on a close back below $77.05, the 4-day report on a close below $76.80. That matters for strike selection below — it is why the bullish structure is built from $77 rather than from $75, and why the bearish structure's short strike sits at $74 rather than deeper.
Model vs. Market: The options market implies $74.16–$80.64 into September 18; the 4-day technical model targets $78.60 within a $75.90–$79.60 range. The chart says grind higher inside the band; the options chain says it isn't willing to bet on which half of the band gets used.
Full technical write-ups: 2-day report → · 4-day report →
4 · Three ways the next four days can go
If NFLX pushes above the call wall ($80.00): That strike carries 27,672 open call contracts for this expiration alone and is the heaviest call strike in the entire chain. Positioning that dense overhead tends to slow rallies as expiration approaches, and $80.00 also sits just under the 100-day average at $80.06. A clean close through it would leave the upper rail of the implied range at $80.64 and then thinner positioning until the $81.16 swing shelf.
If NFLX drifts between the walls: This is the base case the data supports most cleanly. Max pain for September 18 sits at $77.00, forty cents from Friday's close, and the dealer-gamma estimate for this expiration is positive — the regime in which hedging flows tend to compress rather than extend moves. A stock that ends the week between roughly $75 and $80 does the most damage to the most option buyers, and this chain is holding a lot of them.
If NFLX breaks below $75.00: This is the branch with the least cushion. The chain's heaviest put strike is $75.00, the 50-day average is right there at $75.70, and beneath that the September 18 expiration has no meaningful put pile until $65.00. Spot is also sitting about 7% below the $83 gamma-flip estimate, and below that level one rough estimate suggests market-maker hedging amplifies selling rather than cushioning it. A loss of $75 puts the $74.16 implied-range floor and the $73.76 swing shelf in play quickly.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of Friday, September 11. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bullish: September 18 $77/$80 call debit spread
- Trade: Buy the September 18 $77 call at $1.53, sell the September 18 $80 call at $0.43
- Debit: $1.10 ($110 per spread) · Max profit: $190 · Max loss: $110 · Break-even: $78.10
- Why it fits: A debit spread means you pay up front and need the stock to rise; that's the right side of the trade when premium is cheap. IV rank is 17/100 and options are priced about 1.4 vol points below what NFLX has actually delivered, so you're buying rather than selling a thin premium. The short strike sits exactly on the call wall at $80.00, where 27,672 open call contracts make further upside hard work — so you're capping where the market caps you anyway. The break-even at $78.10 is the 2-day chart model's own target.
- Makes sense only if: you side with the chart models' bullish structure and want the bias's neutrality expressed as a small, capped cost rather than a directional bet with open risk.
- Invalidated if: NFLX closes below $75.00.
- Earnings exposure: Expires more than a month before the October 20 report — no earnings-gap risk.
- Managing it: Four days is not much runway. Take profit at roughly 60–70% of max value if the stock tags $79.50 early; with the short-term trend fighting a flat two-month picture, don't hold for the last few cents. Exit by the September 17 close regardless of outcome rather than carrying pin risk into expiration.
- Liquidity note: The $77 calls traded $0.04 wide (2.6% of mid) and the $80 calls $0.02 wide (4.7%) on Friday, on 11,869 and 10,083 contracts respectively. Fills should be easy.
- Analyze this position →
If you expect the range to hold: September 18 $72/$74/$80/$82 iron condor
- Trade: Sell the $74 put at $0.235 / buy the $72 put at $0.085; sell the $80 call at $0.43 / buy the $82 call at $0.165 — all September 18
- Credit: $0.42 ($41.50 per condor) · Max profit: $41.50 · Max loss: $158.50 · Break-evens: $73.59 and $80.42
- Why it fits: With a credit structure you collect premium up front and win if the stock stays between the short strikes. The short strikes bracket the expected-move rails: $74 sits just under the $74.16 floor, and $80 is the call wall. Max pain at $77.00 is dead center. This is the structure that matches the neutral bias most directly.
- Health warning: you're selling premium that hasn't been rich lately. The volatility risk premium is negative — options are priced about 1.4 vol points below delivered movement, and that gap has been richer than today on about 62% of this stock's recent days. Collecting $41.50 to risk $158.50 is a thin ratio, and the data says this is the wrong week to be a seller.
- Makes sense only if: you have a strong independent conviction that the $75–$80 shelf holds through Friday and you accept being paid below-average rates for it.
- Invalidated if: NFLX closes below $75.00 or above $80.00 — close the threatened side rather than defending it in a four-day structure.
- Earnings exposure: Expires more than a month before the October 20 report — no earnings-gap risk.
- Managing it: Close at roughly 50% of max credit, which on this ratio can happen in a single quiet session. Exit both sides by the September 17 close.
- Liquidity note: The $80 calls were $0.02 wide and the $74 puts $0.01 wide — tight in dollar terms. The $72 put wing is also $0.01 wide, but on an $0.085 mid that's roughly 12% in percentage terms; expect to give up a little on that leg, or trade the condor as a package rather than legging in.
- Analyze this position →
If you lean bearish: September 18 $77/$74 put debit spread
- Trade: Buy the September 18 $77 put at $1.07, sell the September 18 $74 put at $0.235
- Debit: $0.84 ($83.50 per spread) · Max profit: $216.50 · Max loss: $83.50 · Break-even: $76.17
- Why it fits: The short-horizon trend read is decisively negative — price momentum is unusually weak versus this stock's own norm after a 6.4% five-day slide — and cheap premium is a reason to own the move rather than sell it. The long strike sits at max pain ($77.00), the short strike just under the implied-range floor ($74.16), so you're paying for exactly the span between the pin and the rail.
- Makes sense only if: you think the bounce the chart models are reading is a retracement inside a two-month downtrend — price is still 10.25% below its 200-day average — rather than a new leg up.
- Invalidated if: NFLX closes above $79.44 (the 20-day average), which would put the call wall and the top of the implied range back in play.
- Earnings exposure: Expires more than a month before the October 20 report — no earnings-gap risk.
- Managing it: The $75.00 shelf is the decision point. Take profit into any test of $75; if the stock holds that level for two consecutive closes, the thesis is stale and the remaining time value will bleed fast. Exit by the September 17 close.
- Liquidity note: The $77 puts traded $0.04 wide (about 3.7% of mid) on 1,929 contracts and the $74 puts $0.01 wide (about 4.3%) on 5,010 contracts. Both fine.
- Analyze this position →
If none of these: no trade
Standing aside is entirely defensible here, and for a specific reason. The directional read is genuinely neutral — the positioning inputs point in opposite directions and the composite sits at effectively zero, which is the arithmetic telling you it has nothing to say about direction. Meanwhile, the one structure that doesn't need a direction, the iron condor, is the one the volatility data argues against: you'd be selling premium that has been cheaper than usual relative to what the stock actually delivers, for $41.50 against $158.50 of risk, in a four-day window with no catalyst. Cheap options are a reason to buy, but only if you have a view worth expressing. If you don't, waiting for either a clean reclaim of $79.44 or a failure through $75.00 costs you nothing but patience.
6 · Quick FAQ
What is NFLX's expected move this week? ±$3.24, or ±4.19%, into the September 18 expiration — a $74.16 to $80.64 band around Friday's $77.40 close, per the options market's straddle pricing as of September 11.
Is NFLX expected to go up or down over the next four days? Options positioning as of September 11 is genuinely neutral — an unusually call-heavy session and building call open interest at $77 pulling one way, sharply negative price momentum pulling the other — but that's a read of what traders have done, not a forecast. The actionable map is the $74.16–$80.64 range with $80.00 overhead and $75.00 beneath.
Are NFLX options expensive right now? No. IV rank of 17/100 says option prices are lower than about 83% of the past year's readings, and on top of that they're running about 1.4 vol points below the movement NFLX has actually delivered over the last 20 sessions — a gap that has been richer than today on roughly 62% of this stock's own recent days. That combination favors buying premium over selling it, and no part of it is inflated by earnings, which are 36 days away.
When is NFLX's next earnings report? October 20, 2026, after the close — after the October 16 expiration but before October 23, which is why the implied move jumps from ±10.71% to ±14.06% between those two rungs.
Where is NFLX's biggest options support and resistance? For the September 18 expiration, the call wall is $80.00 (27,672 contracts) and the put wall is $65.00 (20,055 contracts). Across the whole chain, the heaviest put strike is much closer at $75.00 — which is the level that actually matters this week.
What invalidates this read? A close below $75.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for NFLX, 2026-09-11, generated 2026-09-14T04:08:07Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. Earnings dates and reported results are from the data provider's earnings feed as of 2026-09-14T04:08:07Z; report dates can change. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.