NIO Options Outlook: Will the $2.50 Put Wall Hold Through November 20?
NIO fell 14% in five sessions to a fresh 52-week low at $2.90, and put volume hit an extreme for this name. Options imply a $2.51–$3.29 range into November 27. Our read of the positioning is neutral, with $2.50 as the floor and $3.50 as the cap.
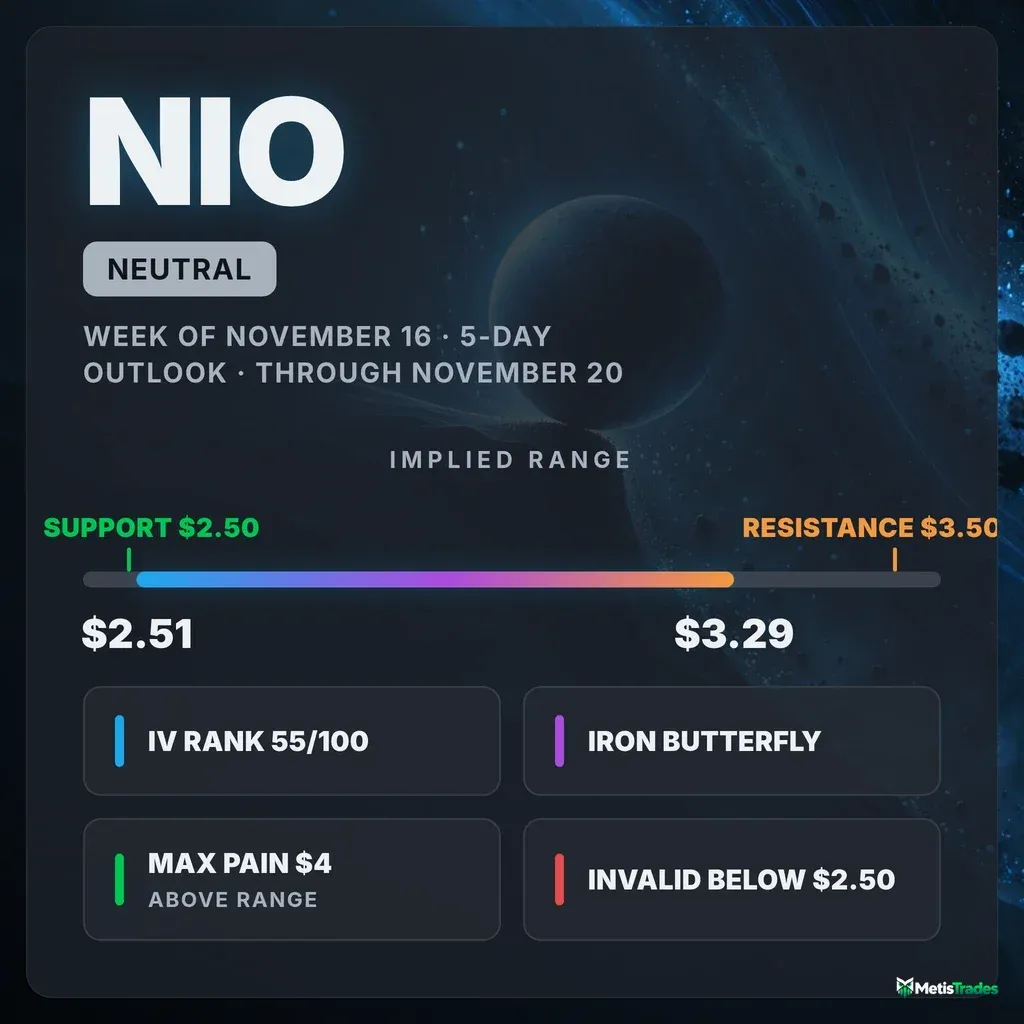
The options market implies a $2.51–$3.29 range into November 27, and NIO sits at a 52-week low between a $2.50 put wall and a $3.50 call wall. Here's what's driving the setup and three defined-risk ways to trade the next five sessions.
Published Sunday, November 15, 2026 · Data as of Friday, November 13, 2026 close
Explore the live NIO options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into Nov 27; the Nov 20 rung couldn't be priced) | $2.51 – $3.29 (±$0.39, ±13.38%) |
| Major support | $2.50 (put wall, Nov 20 expiration) |
| Major resistance | $3.50 (call wall, Nov 20 expiration) |
| Max pain (Nov 20) | $4.00 |
| Dealer gamma regime (estimate) | Negative: hedging tends to amplify moves. Flip level ≈ $1.50 |
| Volatility condition | Rising. IV rank 55/100 · premium fair-to-rich: options priced ~19 vol pts above delivered movement |
| Technical check | Diverges (bearish, 3-day target $2.83 and 5-day target $2.80) |
| Best-fitting strategy | Nov 20 $3 iron butterfly, only if NIO stabilizes near $3 |
| Analysis invalidated if | NIO closes below $2.50 |
1 · What matters today
NIO closed Friday at $2.90, down about 14% in five sessions and sitting on its 52-week low. Our read of the options data is neutral. Friday's put-buying was extreme, but traders also closed puts and added calls, and short-dated positioning leans bullish. That positioning is pushing back against a price trend that is plainly down. The options market is pricing a move of about $0.39 either way through November 27, which works out to roughly $2.51 to $3.29. "Pricing" here means the move implied by what straddles cost.
The level that changes the picture is $2.50. That's the strike with the biggest pile of open put contracts near the price, and a close below it breaks the range view. The chart-based technical models disagree with this read: both lean bearish and target $2.80–$2.83.
2 · What the options market is pricing
What changed this week
The week was a liquidation. NIO dropped 14.5% over five trading days and 15.5% over twenty. Option volume ran 3.3 times its 20-day average, and share volume was about 1.8 times normal.
The headline number is the put/call volume ratio, which measures put activity relative to calls (above 1 means puts dominate). It hit 2.29 on Friday, against a 7-day average of 0.50 and a 14-day average of 0.38. That means 2.3 puts traded for every call, a pace unusually heavy even for this name compared with its own recent history.
Open interest tells a calmer story. Open interest means contracts currently held open. The put/call open-interest ratio slipped to 0.66 from a 7-day average of 0.68. Calls added roughly 6,800 contracts on the day while puts shed about 5,900. The single biggest change was 4,320 contracts closed in the deep-in-the-money November 20 $4 puts, which looks like profit-taking on old hedges, not fresh bets.
Implied volatility rose 10.6% over five days. The short, medium, and longer-term trend reads all agree on a bearish direction. A brief bullish turn in momentum on November 6 was quickly overrun.
Expected move
The November 20 expiration, the one this article is anchored to, had call and put quotes at the $3 strike that disagreed too much to blend into a reliable implied volatility. The quote quality was too poor to price that rung. The nearest clean read is November 27: ±13.38%, or about $0.39 up or down from $2.90. The five-day window to November 20 sits inside that two-week envelope.
| Expiration | Implied move | Range around $2.90 |
|---|---|---|
| Nov 20 | n/a (quote quality too poor) | n/a |
| Nov 27 | ±13.38% | $2.51 – $3.29 |
| Dec 4 | ±16.04% | $2.43 – $3.37 |
| Dec 18 | ±21.1% | $2.29 – $3.51 |
The ladder widens steadily with time and shows no sudden step-up. Nothing on the calendar is being singled out. The market is simply pricing a volatile stock to stay volatile.
Volatility
At-the-money implied volatility is 62.29%. Implied volatility is the market's estimate of how much NIO will move, baked into option prices. It jumped 11.5% on Friday alone and is up 38.7% over 30 sessions. It now sits well above its 30-day average (51.8%) and its 90-day average (53.0%).
IV rank is 55/100. That means today's IV sits a bit past the middle of its one-year range, and it's higher than about 69% of the past year's daily readings. The front-versus-back comparison of option prices across expirations (the term structure) isn't available today, because Friday was an expiration day and the front-month read drops out. Two-month implied volatility is 65.7%. The stock itself has been moving hard: realized volatility over the past 20 days is running well above NIO's own recent norm, and the last ten sessions clocked 58.7% annualized.
Premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much NIO has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them. Options are priced about 19 vol points above the 43.5% that NIO has delivered over 20 days.
That gap sits at the 62nd percentile, meaning it's richer than 62% of this stock's own recent readings. That's middling, not extreme. It has bounced between roughly 14 and 27 points all week without changing sign. IV rank 55 combined with a 62nd-percentile premium is a neutral backdrop. Selling premium isn't a giveaway, and buying it isn't a bargain. The structure has to earn its keep from the levels.
Skew and sentiment
Skew is the observation that puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. NIO's quoted skew points the unusual way. On paper, 25-delta calls carry implied volatility about 71 vol points above comparable puts, against a 60-day norm where puts ran about 2 points over calls.
Treat the size of that number loosely. On a sub-$3 stock quoted in pennies, wing implied volatilities get distorted. The direction, though, matches the past week: the 7-day average skew also leaned call-rich. Despite the price collapse, traders are not bidding up out-of-the-money puts. The heavy put volume clustered at and near the money instead.
Sentiment in short-dated options leans bullish. The 0–7 day read is +47 and the 7–30 day read is +46, both above their 7-day averages of +39 and +28, and every expiration bucket leans the same way. Weigh that against the record: short-dated bullish readings on NIO have struggled to translate into higher prices. Read this as call buyers and put closers fading a falling stock, not as a confirmed turn.
Our early-warning positioning read has flagged a "bullish setup." Price is falling while positioning improves, a pattern that has historically preceded turns, but it is unconfirmed by construction. That signal is why we stop at neutral instead of leaning bearish.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 200-day moving average | $4.83 | Long-term trend line, about 40% overhead |
| 100-day moving average | $4.05 | Intermediate trend, far above spot |
| Max pain (Nov 20) | $4.00 | Inflated by old $4 open interest; not a realistic five-day magnet |
| Swing resistance | $3.55 | Top of the recent price shelf |
| Call wall (Nov 20 and whole chain) | $3.50 | Heaviest call open interest near the price: 7,180 contracts on Nov 20, 76,318 chain-wide |
| 50-day moving average | $3.45 | Medium-term trend overhead |
| Swing resistance | $3.44 / $3.36 | The early-November consolidation zone |
| Implied range top (Nov 27) | $3.29 | Upper edge of the priced-in move |
| 20-day moving average | $3.27 | Short-term trend, 11% above spot |
| Nov 12 down-gap | $3.16 – $3.24 | Unfilled gap from the breakdown |
| Swing resistance | $3.10 | First structural ceiling above spot |
| Largest-gamma strike | $3.00 | Heaviest gamma concentration in the chain; the pin candidate |
| Close / 52-week low | $2.90 / $2.89 | Price is sitting on its yearly low |
| Technical support (chart model) | $2.80 | Lower Bollinger Band and the TA downside target |
| Implied range bottom (Nov 27) | $2.51 | Lower edge of the priced-in move |
| Put wall (Nov 20 and whole chain) | $2.50 | Heaviest put open interest near the price; thin on Nov 20 (71 contracts), deep chain-wide (77,888) |
| Largest put open interest (context) | $2.00 | Biggest put strike anywhere: 190,225 contracts, mostly far-dated hedges |
| Gamma flip (estimate) | $1.50 | Rough estimate only; far below the action |
Positioning and unusual flow
Market makers hedge the options they've sold. In a negative-gamma regime, their hedging tends to amplify moves rather than dampen them. One rough estimate, built on an assumed dealer sign convention, puts both the whole chain and the November 20 expiration in negative territory. Its crude gamma-flip estimate lands far below at $1.50, so treat the regime label as soft. The practical takeaway is that a break of a level could run further than usual.
Three items stand out:
- January 15 $3 puts: 19,115 contracts traded, about $621,000 in premium. Open interest rose only 802, so most of that was turnover and rolling, not a new wave of protection.
- December 18 $3 calls: open interest jumped by 1,249 contracts on 2,762 traded (about $59,000). This is fresh at-the-money call buying into the selloff.
- February 19 $2 puts: open interest rose from 53 to 2,050 on 6,057 contracts. This is new crash insurance roughly 30% below spot, the clearest genuine hedge in the tape.
3 · Technical check
Both chart models lean bearish, which diverges from our neutral options read. Both targets still sit inside the options-implied range.
- 3-day report: targets $2.83 by November 18, with a $2.76–$2.95 range.
- 5-day report: targets $2.80 by November 20, with a $2.70–$2.93 range.
The most decisive readings are a strong, accelerating downtrend (ADX 41.6, with sellers' directional reading near 40 against buyers' under 8) and heavy distribution, with money flow deeply negative. Both models also flag a deeply oversold RSI near 20 as genuine bounce risk. Their dominant bearish scenario is invalidated by a close back above $2.99.
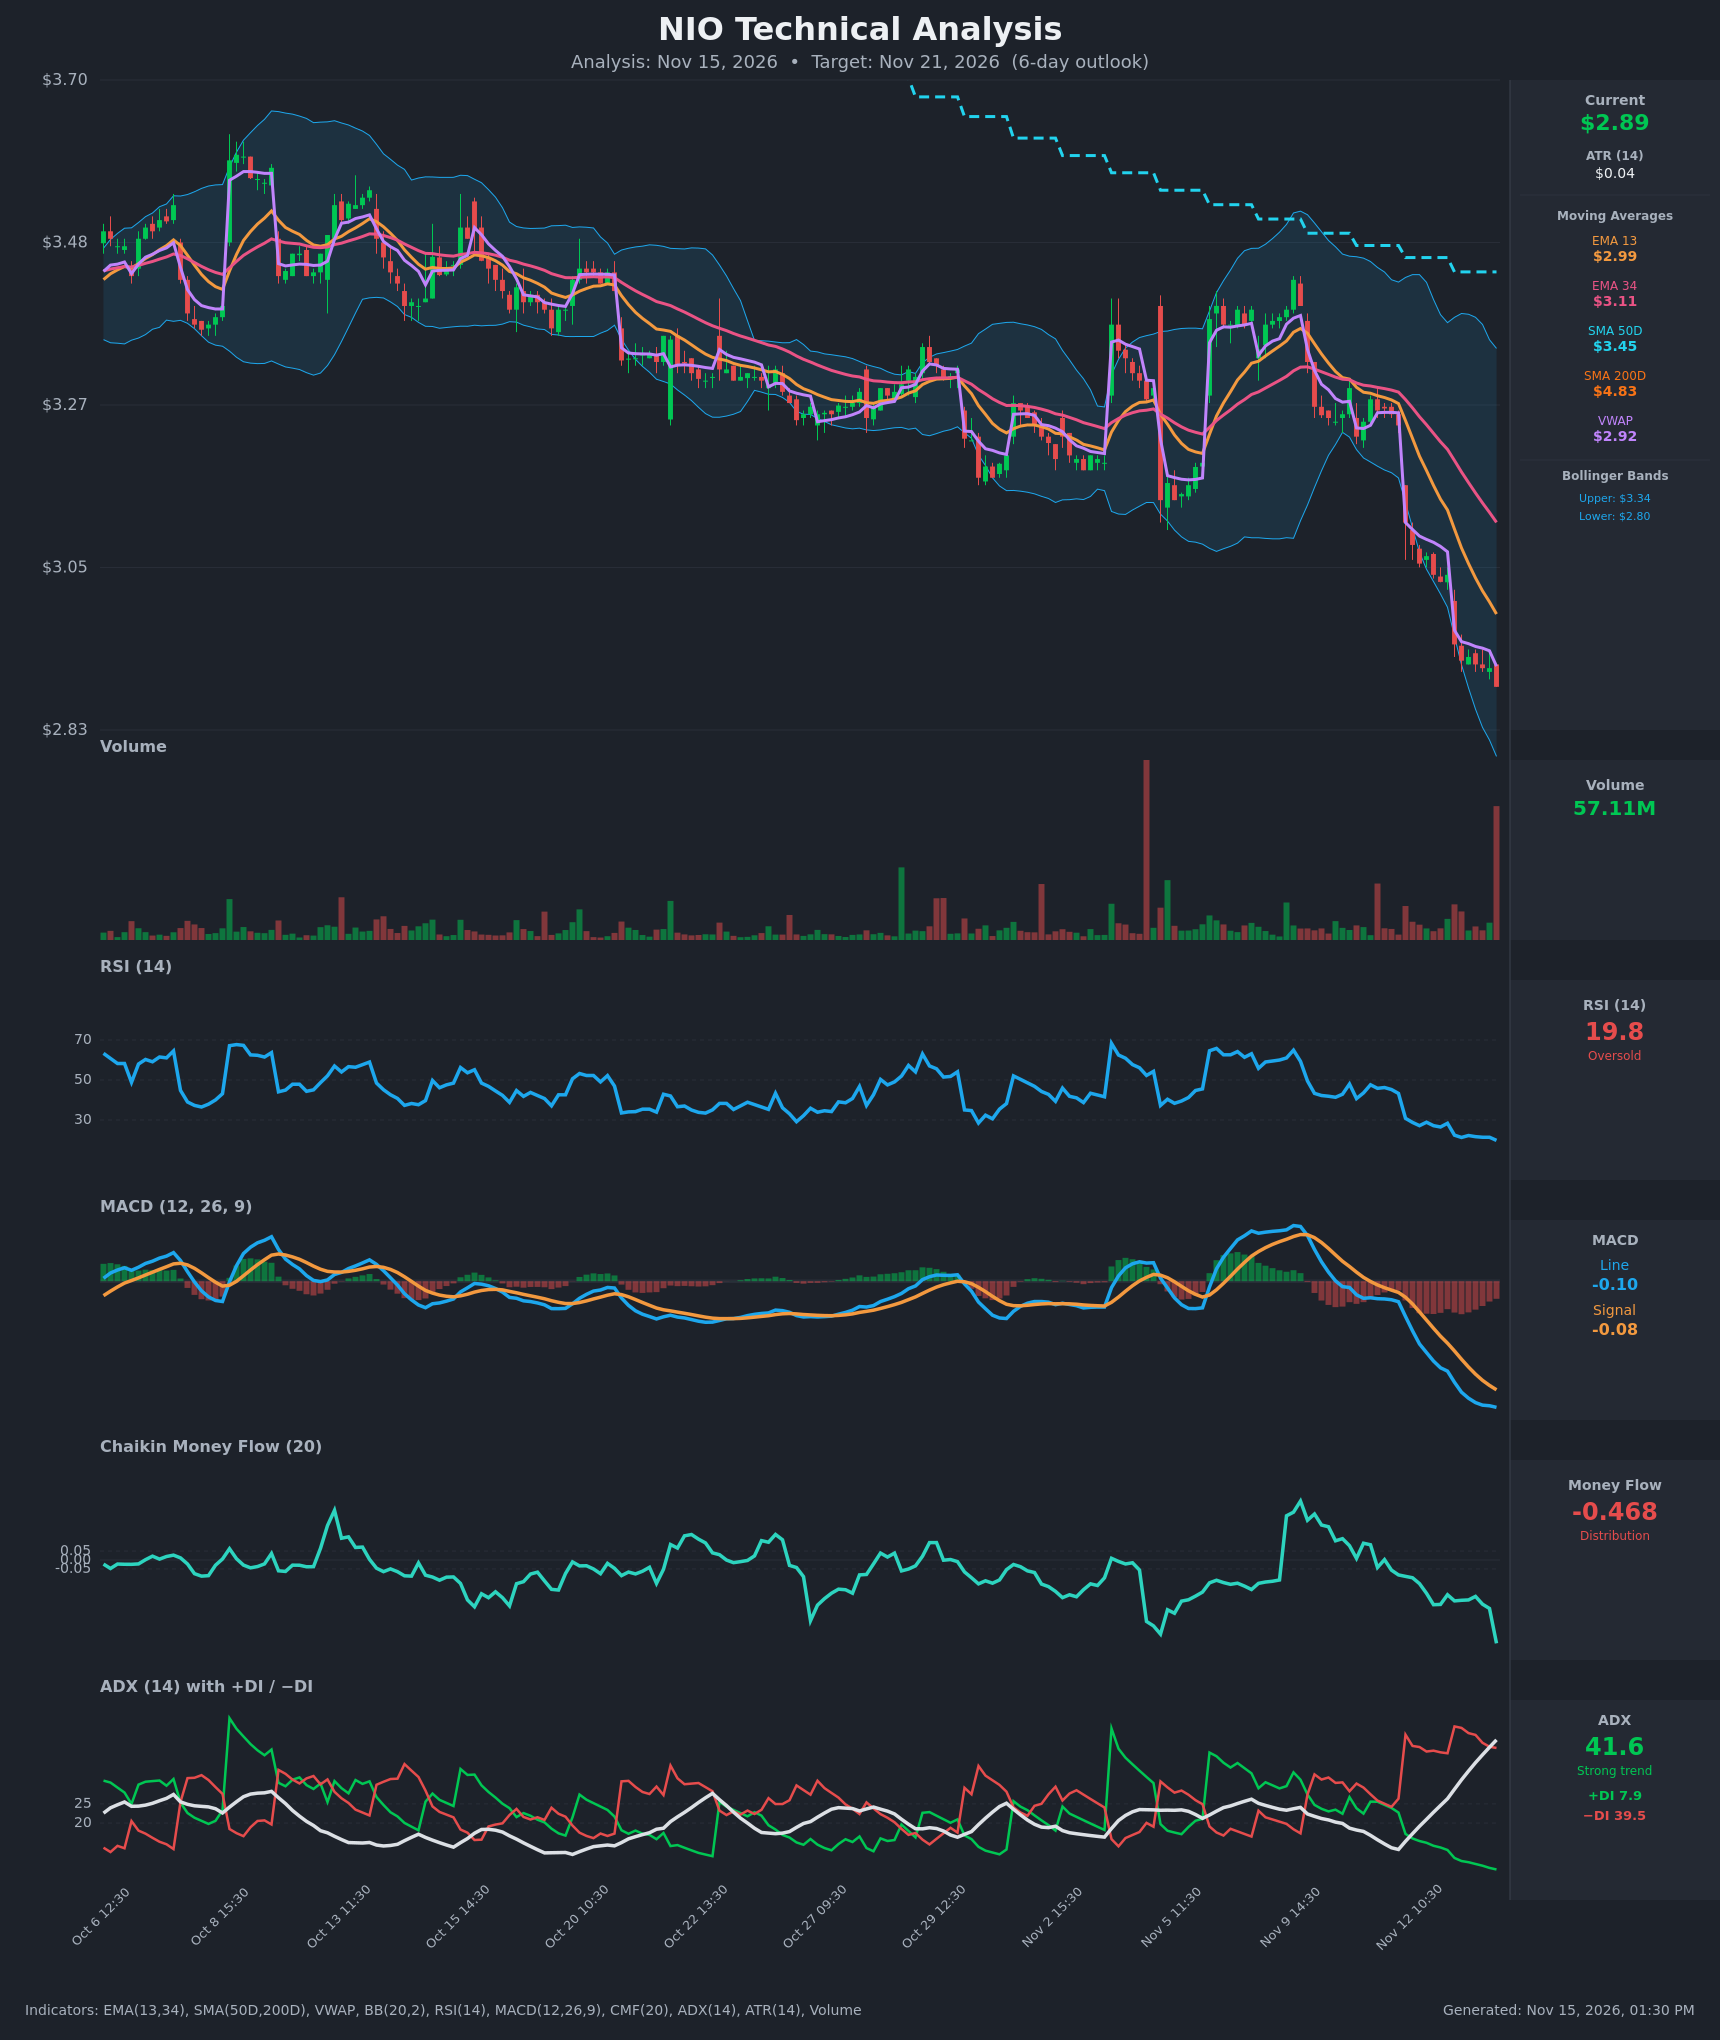
Model vs. Market: The options market implies $2.51–$3.29 through November 27. The 5-day technical model targets $2.80. The chart sees a drift to the low end of a range the options market thinks could just as easily break upward. A hold above $2.80 into midweek favors the options read; a close below it favors the chart.
The technical targets did shape the structures below. Because $2.80 sits just under the iron butterfly's lower break-even, we pair that trade with an explicit exit and keep a bearish put spread on the menu. Strikes themselves weren't shaded: NIO only lists $0.50 increments near the money.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the week can go
If NIO pushes above the call wall ($3.50): The heaviest call open interest near the price sits at $3.50, and stacked swing resistance runs from $3.10 to $3.55. A rally from $2.90 has to clear several layers before it gets there, and heavy overhead call positioning tends to slow advances as it's approached. A clean break would also reclaim the 50-day average at $3.45, leaving thinner positioning above until the $4.00 strike.
If NIO drifts between the walls: This is the base case. The $3.00 strike carries the most gamma in the chain, and expirations sometimes gravitate toward such strikes as hedges get adjusted into Friday. November 20's max pain is $4.00. Max pain is the price where the most option value would expire worthless, and it is usually treated as a magnet. Here, though, it reflects large leftover $4 positions from when NIO traded higher, so we wouldn't count on it pulling price $1.10 higher in five sessions. A $2.80–$3.10 drift is what the positioning describes.
If NIO breaks below the put wall ($2.50): On November 20 the put wall is thin, only 71 contracts. Its real weight comes from far-dated expirations, so near-term support is weaker than the headline strike suggests. With the gamma estimate leaning negative, a break could accelerate as hedging adds to selling. The next big put concentration is $2.00. The crude flip estimate at $1.50 sits well below that, and spot's distance from it is about typical for this name.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 13, 2026. All structures are hypothetical unless flagged as an entered position. Verify live prices before trading, because these will be stale by the open.
One warning applies to every structure below. On a $2.90 stock, a one-cent spread is a large share of a five-cent option. Expect fills worse than mid, and size accordingly.
If you expect the range to hold: Nov 20 $3 iron butterfly
- Trade: Sell the Nov 20 $3 call and $3 put, buy the $3.50 call and $2.50 put. You collect premium and profit if NIO settles near $3.
- Credit: $0.165 ($16.50 per contract) · Max profit: $16.50 at exactly $3.00 · Max loss: $33.50 · Break-evens: $2.835 and $3.165
- Why it fits: $3 is the chain's heaviest-gamma strike, the wings sit exactly on the $2.50 put wall and $3.50 call wall, and premium is moderately rich (19 vol points over delivered movement).
- Makes sense only if: NIO stops falling and trades back toward $3. At $2.90 you start just inside the lower break-even, so the technical $2.80 target would put this trade underwater.
- Invalidated if: NIO closes below $2.80 or above $3.20.
- Managing it: Take profits at roughly 40–50% of the credit. Close by November 18 if NIO isn't between $2.85 and $3.15, rather than holding gamma risk into the final day.
- Liquidity note: The $3 calls trade a penny wide ($0.06/$0.07), as do the $3.50 calls and $2.50 puts ($0.01/$0.02). The $3 puts are 6¢ wide ($0.10/$0.16), and their bid sits at intrinsic value, so the realistic credit is likely closer to $0.14.
- Analyze this position →
If you lean bullish: Nov 20 $3/$3.50 bull call spread
- Trade: Buy the Nov 20 $3 call, sell the Nov 20 $3.50 call. You pay a small debit and profit if NIO rises above $3.05 by expiration.
- Debit: $0.05 ($5 per spread) · Max profit: $45 at or above $3.50 · Max loss: $5 · Break-even: $3.05
- Why it fits: Fresh call open interest, bullish short-dated sentiment, and an oversold relief-bounce scenario all point the same way. The spread caps at the $3.50 call wall, and risk is tiny in dollar terms.
- Makes sense only if: You treat it as a low-probability bounce ticket. NIO needs a roughly 5% rally against an intact downtrend.
- Invalidated if: NIO closes below $2.80.
- Managing it: The short-term bounce would be fighting a trend that's down nearly 25% over about two months, so take profits early. Close if the spread doubles, or cut by November 18 if NIO hasn't reclaimed $3.
- Liquidity note: The $3 calls traded $0.06/$0.07 on 5,897 contracts, and the $3.50 calls $0.01/$0.02. Fills are easy, but each penny is 20% of the debit.
- Analyze this position →
If you lean bearish: Nov 20 $3/$2.50 bear put spread
- Trade: Buy the Nov 20 $3 put, sell the Nov 20 $2.50 put. You pay a debit and profit as NIO falls toward $2.50.
- Debit: $0.115 ($11.50 per spread) · Max profit: $38.50 at or below $2.50 · Max loss: $11.50 · Break-even: $2.885
- Why it fits: It sides with the aligned bearish trend and both technical models, whose $2.80 target sits comfortably in the profit zone. Max profit lands right at the $2.50 put wall.
- Makes sense only if: Friday's selling continues instead of turning into a capitulation bounce.
- Invalidated if: NIO closes above $3.10.
- Managing it: Take profits near $2.70 (roughly 70% of max). Exit by November 18 if NIO is back above $2.99, the technical models' own invalidation.
- Liquidity note: The $3 puts are 6¢ wide ($0.10/$0.16), so expect to pay closer to $0.13–$0.14 net. The $2.50 puts trade $0.01/$0.02.
- Analyze this position →
If none of these: no trade
Standing aside is a real option here, for four reasons:
- The premium backdrop is middling, not rich enough to pay you for selling.
- The November 20 at-the-money quotes are unreliable; the put and call sides disagree.
- Percentage spreads on sub-dime options eat a meaningful share of any edge.
- The setup is a genuine tug-of-war, with an oversold, heavily-hedged stock on one side and a strong downtrend on the other.
If you don't have a view on whether Friday was capitulation or continuation, waiting for a close back above $2.99 or below $2.80 costs you nothing.
6 · Quick FAQ
What is NIO's expected move this week? The November 20 rung couldn't be priced cleanly. The nearest reliable read, November 27, implies ±$0.39 (±13.38%), a $2.51–$3.29 range based on straddle pricing as of November 13.
Is NIO expected to go up or down over the next week? Options positioning as of November 13 is neutral. Extreme put volume and a bearish trend are offset by call building and bullish short-dated sentiment, and that's a read of what traders have done, not a forecast. The actionable map is the $2.51–$3.29 range and the $2.50/$3.50 levels.
Are NIO options expensive right now? IV rank 55/100 puts implied volatility above about 69% of the past year's readings. On top of that, options are running about 19 vol points above the movement NIO has actually delivered, richer than 62% of this stock's recent readings. That's fair-to-rich, not extreme.
Where is NIO's biggest options support and resistance? For November 20, the put wall is $2.50 and the call wall is $3.50. The whole chain shows the same strikes.
What invalidates this week's read? A close below $2.50.
Methodology & disclosures. Data: end-of-day options-chain snapshot for NIO, 2026-11-13, generated 2026-11-15T13:30:24.366Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.