QUBT Options Are Pricing a $0.76 Move Into September 25 — and the Skew Disagrees With the Chart
QUBT's options market implies a $7.94–$9.46 range into the September 25 expiration, with the heaviest call open interest capping at $9.00 and max pain sitting down at $8.00. Put protection has gone from cheap to expensive in a week, even as both chart models call for more upside.
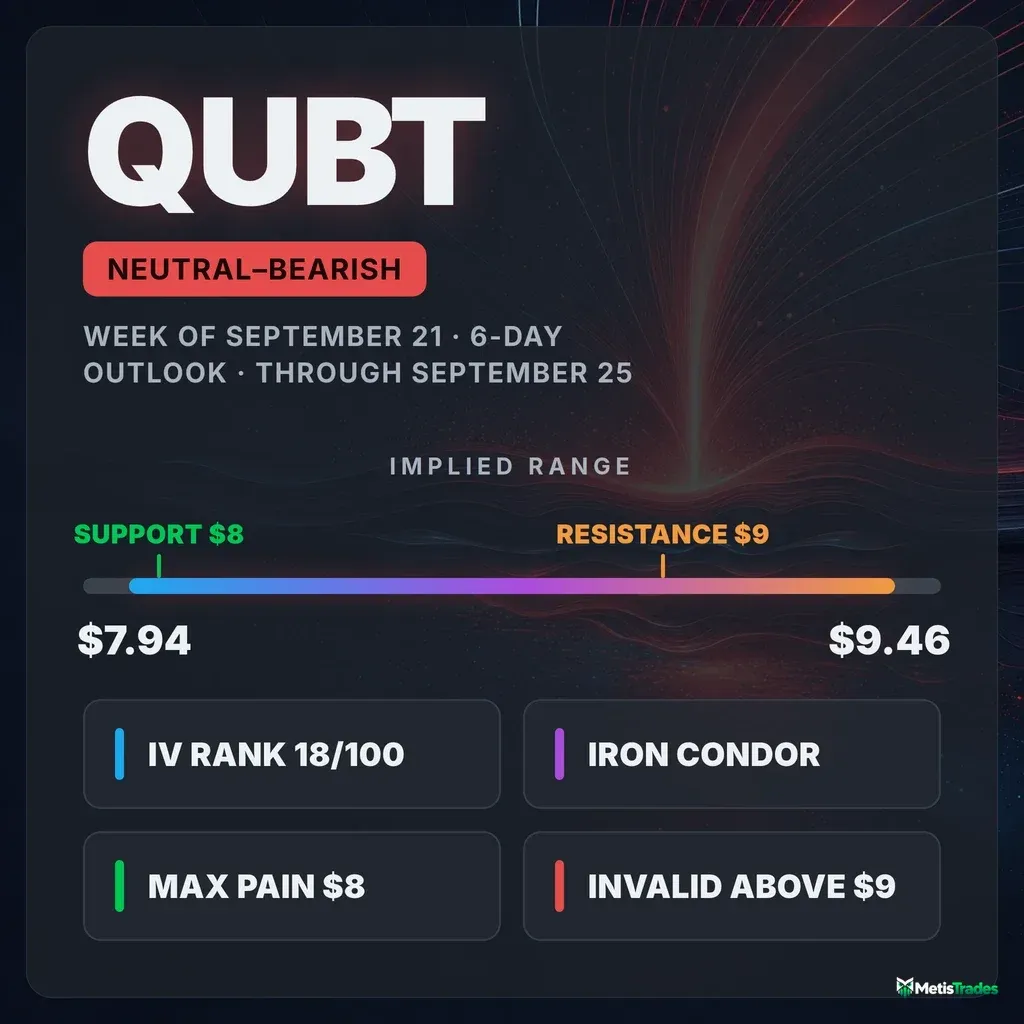
The options market implies a $7.94–$9.46 range into the September 25 expiration; here's what's driving it, where the walls sit, and three defined-risk ways to trade it.
Published Saturday, September 19, 2026 · Data as of Friday, September 18 close
Explore the live QUBT options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bearish tilt |
| Spot (Friday, September 18 close) | $8.70 |
| Options-implied range (into September 25) | $7.94 – $9.46 (±8.75%, or about ±$0.76) |
| Major support | $8.00 (put wall, September 25 expiration) |
| Major resistance | $9.00 (call wall, September 25 expiration) |
| Max pain (September 25) | $8.00 |
| Dealer gamma regime (estimate) | Positive — one rough estimate suggests hedging tends to dampen moves into this expiration; the flip level estimate sits near $2, far below spot, so it offers no nearby pivot |
| Volatility condition | Rising — IV rank 18/100 · premium rich: options priced about 10 vol points above delivered movement |
| Technical check | Diverges (bullish, 3-day and 6-day chart models) |
| Best-fitting strategy | Iron condor around the $8.00/$9.00 walls |
| Analysis invalidated if | QUBT closes above $9.00 |
1 · What matters today
QUBT closed Friday, September 18 at $8.70 after an 8.9% five-day run. The options market is pricing a move of roughly ±$0.76 — about ±8.75% — through the September 25 expiration, which frames a $7.94 to $9.46 range. That's the map.
Our read of the options data lands neutral with a slight bearish tilt, and the reason is one number: the price gap between puts and calls. Puts the same distance from the stock as calls now cost 21.7 volatility points more, against a recent norm where they actually cost about 6.9 points less. Traders paid up hard for downside protection into a rally. Spot is also sitting just under the strike with the heaviest call open interest for this expiration, $9.00, while the level where the most option value would expire worthless — max pain — sits back at $8.00.
Both chart models point higher, which is the interesting tension. A close above $9.00 kills this read.
2 · What the options market is pricing
What changed this week
The underlying did the heavy lifting: up 8.89% over the trailing five sessions and 6.88% over twenty. Implied volatility — the market's estimate of how much QUBT will move, baked into option prices — followed it up rather than collapsing, rising 8.6% in a single session and 15.9% over five days to 72.2%. That's now fractionally above its own 30-day average of 71.7%, though still far under the 90-day average of 90.6%.
Underneath the rally, positioning got more two-sided, not less. The ratio of put open interest to call open interest — contracts currently held open — drifted from 0.59 to 0.64 over five sessions, against a 14-day average of 0.59. For every call contract held open there are now 0.64 puts, and that number has been climbing while price climbed. Friday's volume, by contrast, was aggressively call-tilted: a put/call volume ratio of 0.34 against a 7-day average of 0.80 and a 14-day average of 0.62, on total option volume 3.0× its 20-day norm. Fast money bought calls; the standing book added puts.
The single biggest change in contracts held open was at the October 16 $10 call, which added 10,096 contracts to reach 12,972 — but the October 16 $10 put added 9,809 to reach 13,104 in the same session. Both sides of one strike built at once, which reads more like a combination or a roll than a directional bet.
The short- and long-term trend reads currently agree rather than fight: the one-week and roughly one-month reads are both bullish, with the two-month read flat. Momentum crossed from bearish to bullish on September 10 and has held that side since.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the September 25 expiration it is ±8.75% of spot — about ±$0.76 — which brackets $7.94 to $9.46 around the $8.70 close.
| Expiration | Implied move | Range around $8.70 |
|---|---|---|
| September 25 (7 days) | ±8.75% | $7.94 – $9.46 |
| October 2 (14 days) | ±12.18% | $7.64 – $9.76 |
| October 16 (28 days) | ±19.42% | $7.01 – $10.39 |
The ladder steps up close to the square root of time, which is what you'd expect with no scheduled event distorting a particular rung — the October 16 expiration prices roughly 2.2× the September 25 move for 4× the calendar.
Volatility
Chain-wide at-the-money implied volatility is 72.2%. The September 25 expiration's own at-the-money read is lower at 63.2%, and that 63.2% is what produces the ±8.75% figure above — the front of the curve is cheaper than the chain average. IV rank is 18/100, meaning today's implied volatility is cheaper than about 82% of the past year's readings; the percentile reading is even more extreme at 7.9. Over 30 sessions IV is down 25.7%. The front-month read is unavailable today — Friday was an expiration day, and front-month at-the-money volatility can't be interpolated from a contract expiring the same session.
Two observations versus this stock's own recent history are worth noting. Twenty-day realized volatility — how much QUBT has actually been moving — is 62.1%, which is unusually low for this name. And the five-day-over-twenty-day realized volatility ratio is 0.70, below its norm: actual day-to-day movement has been decelerating even as the price trended up. Meanwhile, the price-momentum reading is running well above its own norm. Trending quietly, in other words.
Premium rich or cheap. The volatility risk premium is the gap between how much movement options are priced for and how much QUBT has actually delivered — when it's positive, option sellers have been collecting more than realized movement cost them. Right now it's about 10 vol points positive (72.2% implied against 62.1% delivered), and that gap sits at the 78th percentile of this stock's own recent readings — richer than roughly 78% of them. The path matters too: the gap was near 3.9 points on Thursday and near zero or negative several times in the past two weeks, so it richened sharply in one session as IV jumped while realized movement kept fading. That combination — IV rank of 18 but a 78th-percentile premium over delivered movement — favors collecting premium rather than owning it this week, with the honest caveat that the absolute level of premium is thin because the whole volatility surface is depressed versus the past year.
Skew and sentiment
Skew describes the fact that puts and calls the same distance from the stock price don't cost the same. Here, the 25-delta put is marked at 105.5% implied volatility against 83.8% for the 25-delta call — 21.7 volatility points of put premium. The 60-day median for this name is negative 6.9 points, meaning calls have normally been the pricier side. That is a 28.6-point swing versus the norm, and the 25-delta skew reading is stretched well beyond its own recent history. Translation: traders are paying up hard for crash protection at exactly the moment the stock is breaking out.
Flow tells the other half. Put/call volume at 0.34 is 22% below its 60-day median, symbol-wide volume ran 3.0× its 20-day average and skewed 50% to calls, and two call contracts cleared the peer-relative unusual bar against zero puts. Net new open interest was call-heavy: +27,938 calls versus +12,094 puts in one session, an unusually strong call-side build for this name.
Sentiment across expiration terms is mixed. The 0–7 day bucket is essentially flat at +2; the 7–30 day bucket is firmly positive at +47, driven by calls pricing unusually rich relative to puts out there; the 60–120 day bucket is mildly negative at −7. No single regime dominates, which is exactly what the split between call-buying flow and put-rich pricing would predict.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Swing resistance | $11.30 | Upper heuristic pivot cluster; distant |
| Whole-chain heaviest call and put strike | $10.00 | 52,834 calls and 33,206 puts open across all expirations — the chain's center of gravity, but not the September 25 wall |
| 200-day moving average | $9.37 | Price sits 7.1% below it; the long-term trend is still down |
| 100-day moving average | $9.24 | Price 5.8% below |
| Swing resistance | $9.20 | Heuristic pivot; also the top of the 6-day chart model's range |
| Swing resistance | $9.01 | Heuristic pivot, effectively coincident with the call wall |
| Call wall (September 25) | $9.00 | 4,144 calls open — the heaviest call strike for this expiration; caps upside |
| Swing resistance | $8.80 | Nearest overhead pivot |
| Spot | $8.70 | Friday, September 18 close |
| Swing support | $8.54 | Nearest pivot below; also the breakout base the chart models cite |
| 50-day moving average | $8.29 | Price 5.0% above |
| Swing support | $8.26 | Heuristic pivot cluster |
| 20-day moving average | $8.19 | Price 6.3% above |
| Swing support | $8.03 | Heuristic pivot, effectively coincident with the put wall |
| Put wall and max pain (September 25) | $8.00 | 1,871 puts open — the heaviest put strike for this expiration, and the price where the most option value expires worthless |
| Swing support | $7.80 | Next pivot down |
| Gamma flip level (estimate) | ≈ $2.00 | A rough estimate only; it sits so far below spot that it offers no usable near-term pivot |
| 52-week low | $6.18 | Price sits 12.8% up the 52-week range; the high is $25.84 |
Note the disagreement worth flagging: the whole chain's heaviest call and put strikes both sit at $10.00, but that aggregates every expiration out to January. For the six days this article covers, the September 25 expiration's own walls are $9.00 above and $8.00 below. Use those.
Positioning and unusual flow
Market makers hedge the options they've sold, and in a positive-gamma regime that hedging tends to dampen moves rather than amplify them. The estimate for the September 25 expiration is positive — treat it as an estimate, not observed dealer inventory — which is consistent with price grinding inside the $8.00–$9.00 corridor rather than trending violently through it.
Three non-expired flow items stood out Friday:
- October 30 $11.50 calls: 17,581 contracts traded against just 34 open — a turnover of 517× and roughly $422,000 of premium. A single large upside bet or spread leg, far out of the money, in an expiration well beyond this article's window.
- October 16 $10 puts: 4,714 contracts traded, open interest up from 3,295 to 13,104, roughly $759,000 of premium — the largest live dollar print in the chain. Real downside positioning was established a month out.
- October 16 $10 calls: 6,204 traded, open interest up from 2,876 to 12,972, about $171,000 of premium. Paired with the put build at the same strike, this looks like structure rather than conviction in one direction.
Into Friday's own expiration, the settled $8.50 calls turned over 2,035 contracts against 3,129 open — heavy last-day churn right at the money, now history.
3 · Technical check
Both chart reports are bullish, and both were generated fresh against a reference price of $8.695 — effectively identical to the options snapshot's $8.70, so there's no data-date mismatch to discount.
The 3-day model targets $8.88 with a projected range of $8.42 to $9.02 into September 22. The 6-day model, which lines up exactly with our expiration, targets $9.05 with a projected range of $8.35 to $9.20. Its case rests on a fresh bullish MACD crossover with an expanding histogram, ADX rising toward 25 with the directional indicators decisively bullish (+37.5 versus −14.4), and money-flow readings in accumulation territory on the heaviest volume bar of the recent series. Its own caveats are honest ones: RSI at 72.4 is overbought, and price remains well below the 200-day average at $9.37, so this is a counter-trend rally inside a longer downtrend.
Classification: Diverges. The direction contradicts our neutral-with-a-bearish-tilt options read, even though the $9.05 target sits comfortably inside the options-implied range. The single number that would resolve the argument is $9.00 — the call wall. The chart model wants to walk through it; the option book has the heaviest open interest of the expiration sitting on it.
Model vs. Market: The options market implies $7.94–$9.46 into September 25; the 6-day technical model targets $9.05. The chart's target sits inside the implied range, so this isn't a fight about magnitude — it's a fight about whether the $9.00 call wall holds. A close above it says the options positioning read was the wrong lens this week.
How the TA changed the structures below: it didn't move the bias, but it did stop us from shading the short call strike any lower than $9.00. With two bullish chart reads and a rising trend, selling calls under the wall would be picking a fight with both the price structure and the flow.
Full technical write-ups: 3-day report → · 6-day report →
4 · Three ways the next six days can go
If QUBT pushes above the call wall ($9.00): The heaviest call open interest of this expiration sits right there, and strikes with that much open interest tend to slow rallies as hedging flows lean against the move. But the September 25 book thins out fast above it — only 873 calls open at $9.50 and 2,863 at $10.00. A clean break and hold above $9.00 leaves relatively little positioning overhead until the 200-day average at $9.37, and it invalidates this article's read.
If QUBT drifts between the walls: This is the base case the positioning supports. Max pain for September 25 is $8.00, the put wall is also $8.00, and the estimated gamma regime for this expiration is positive — the setup where hedging flows tend to pull price toward the heaviest open interest rather than push it away. A grind between $8.00 and $9.00 with the $8.54 swing support as the first shelf is what the option book is built for.
If QUBT breaks below the put wall ($8.00): That's a 8.0% drawdown from Friday's close and would take price below the 20-day average at $8.19 and the 50-day at $8.29 on the way. The gamma flip estimate — below which market-maker hedging tends to accelerate selling rather than cushion it — is calculated at roughly $2.00, which is so far below spot that it offers no meaningful warning line here; spot currently sits about 77% above it. In other words, the rough dealer-positioning estimate does not flag a nearby fragility point; a break below $8.00 would be a price-structure event, not a hedging cascade.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of Friday, September 18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
Because the premium over delivered movement sits at the 78th percentile of this stock's own readings, premium-selling structures lead here. All three below collect a credit. Remember the mechanics: with a credit spread you take money in up front and keep it if price stays on the right side of your short strike at expiration; your loss is capped by the long strike you bought as protection.
If you expect the range to hold: September 25 iron condor
- Trade: Sell the September 25 $9.00 call / buy the $9.50 call, and sell the $8.00 put / buy the $7.50 put
- Credit: $0.145 ($14.50 per condor) · Max profit: $14.50 · Max loss: $35.50 · Break-evens: $7.855 and $9.145
- Why it fits: The short strikes are the September 25 expiration's own walls — $9.00 is where the heaviest call open interest sits, $8.00 is both the put wall and max pain. The estimated positive gamma regime for this expiration argues for dampened rather than amplified moves, and the 78th-percentile volatility premium means you're selling something that has recently been generous relative to what the stock actually delivers.
- Makes sense only if: you accept that a 1σ move in either direction (±$0.76) lands outside the break-evens. This trade needs the stock to deliver less than the priced move, which is exactly what the rich premium reading says has been happening.
- Invalidated if: QUBT closes above $9.00 or below $8.00 — at that point close the tested side rather than defending it.
- Managing it: With only six days and a 14.5¢ credit, there's little room for a 50%-of-max exit — realistically this is held toward expiration. Close the tested side on a daily close through either short strike; the short-term trend fighting the still-negative two-month price trend argues for taking money early rather than pressing.
- Liquidity note: the $9.00 calls and $8.00 puts each quoted 1¢ wide — fills are easy. The $7.50 put is the weak leg: bid $0.01 against ask $0.05 on a 3¢ mid, so expect to give up a cent or two on the protective wing, or widen it only if you can get filled.
- Analyze this position →
If you lean bearish: September 25 $9.00/$9.50 call credit spread
- Trade: Sell the September 25 $9.00 call, buy the September 25 $9.50 call
- Credit: $0.11 ($11.00) · Max profit: $11.00 · Max loss: $39.00 · Break-even: $9.11
- Why it fits: This is the bias expressed in its purest form — short the strike with the most call open interest of the expiration, with max pain sitting a full dollar below spot. The extreme put-side skew says the market is not positioned for an upside melt-up; it's positioned for a drop.
- Makes sense only if: you're willing to risk $39 to make $11. That ratio is what a 7-day chain pays when IV rank is 18 — the premium is rich relative to delivered movement but thin in absolute dollars, and this structure needs to be right often to pay.
- Invalidated if: QUBT closes above $9.00.
- Managing it: Close at roughly 60% of the credit collected or on any daily close above $9.00, whichever comes first. Both chart models are pointing the other way, which is a reason to take profits early rather than hold for the last few cents.
- Liquidity note: the $9.00 calls quoted 1¢ wide (about 5% of the mid) on 1,053 contracts of volume; the $9.50 calls also quoted 1¢ wide on 473 contracts. Both are tradeable.
- Analyze this position →
If you lean bullish: September 25 $8.50/$8.00 put credit spread
- Trade: Sell the September 25 $8.50 put, buy the September 25 $8.00 put
- Credit: $0.15 ($15.00) · Max profit: $15.00 · Max loss: $35.00 · Break-even: $8.35
- Why it fits: This is the trade that monetizes the skew rather than fighting it. Puts are running 21.7 vol points over calls against a norm where they ran 6.9 points under — you are selling the expensive side of the surface. The long $8.00 wing sits exactly on the put wall and max pain, so your maximum loss is capped right where the book's heaviest downside support sits, and the break-even at $8.35 is above the 50-day average at $8.29.
- Makes sense only if: you side with the two chart models over the options positioning read. Note the short strike is $0.20 below spot — this is not a low-delta trade, and a routine pullback puts it in the money.
- Invalidated if: QUBT closes below $8.26.
- Managing it: Take profits at roughly 50–60% of the credit; exit regardless by Wednesday, September 23, since the last two sessions of a 7-day spread are almost pure gamma risk on a stock that moves 8.75% a week.
- Liquidity note: the $8.50 puts quoted 1¢ wide (about 5% of the mid) on 315 contracts; the $8.00 puts quoted 1¢ wide on 1,628 contracts, the most active put in the expiration. Both fill cleanly.
- Analyze this position →
If none of these: no trade
There's a real case for standing aside even with the premium reading at the 78th percentile. That percentile is measured against QUBT's own recent readings, not against the market — and IV rank of 18/100 says the absolute level of premium is near the cheap end of the past year. Selling something that is rich relative to a depressed baseline still means collecting 11 to 15 cents while risking 35 to 39, on a stock whose options are pricing an 8.75% move in six days. If you need the trade to work seven times out of ten just to break even, the honest question is whether you have any edge at all on which side of $9.00 this resolves — and with the chart models and the option book pointing in opposite directions, the defensible answer this week is "not much." Waiting for a decisive close through $9.00 or $8.00 and trading the resolution is a legitimate fourth option.
6 · Quick FAQ
What is QUBT's expected move this week? About ±$0.76, or ±8.75%, into the September 25 expiration — a $7.94 to $9.46 range around the $8.70 close, per the options market's straddle pricing as of Friday, September 18.
Is QUBT expected to go up or down over the next six days? Options positioning as of September 18 leans neutral with a slight bearish tilt — puts are priced 21.7 vol points over calls against a norm where calls were the pricier side, and spot is pinned just under the expiration's heaviest call strike — but that's a read of what traders have already done, not a forecast. The actionable map is the $7.94–$9.46 range and the $8.00/$9.00 levels.
Are QUBT options expensive right now? Two lenses. IV rank of 18/100 says option prices are lower than about 82% of the past year's readings. But they're running roughly 10 vol points above the movement QUBT has actually delivered over the last 20 sessions — richer than about 78% of this stock's own recent readings. Net: cheap in absolute terms, rich relative to what the stock has been doing, which modestly favors collecting premium over owning it.
Where is QUBT's biggest options support and resistance? For the September 25 expiration, the put wall is $8.00 (1,871 contracts open) and the call wall is $9.00 (4,144 contracts open). Across the whole chain, both the heaviest call and heaviest put strikes sit at $10.00 — but that aggregates expirations out to January and isn't the level that matters this week.
What invalidates this week's read? A close above $9.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for QUBT, 2026-09-18, generated 2026-09-19T18:57:17Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.