RGTI Options Are Pricing a $1.24 Move Into November 20, and Positioning Leans Toward the Lower Half
The options market implies an $8.38–$10.86 range for RGTI into the November 20 expiration. Bullish-looking call flow sits against an unbroken downtrend, so our read is slightly bearish, and cheap premium favors debit structures over selling.
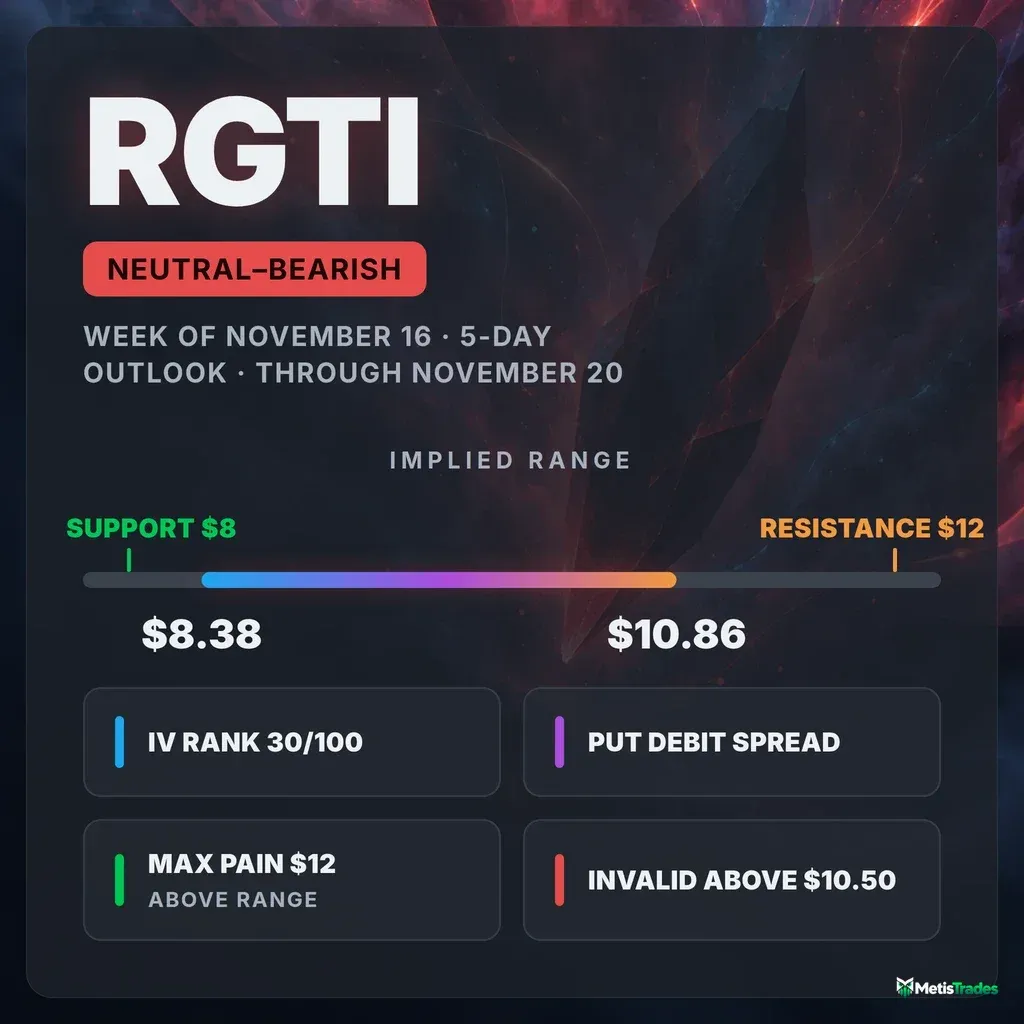
The options market implies a $8.38–$10.86 range into the November 20 expiration. Here's what's driving it, why the bullish-looking flow doesn't change our read, and three defined-risk ways to trade the next five days.
Published Sunday, November 15, 2026 · Data as of Friday, November 13, 2026 close
Explore the live RGTI options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bearish |
| Options-implied range (into Nov 20) | $8.38 – $10.86 (±12.94%, or ±$1.24) |
| Major support | $8.00 (Nov 20 put wall) |
| Major resistance | $12.00 (Nov 20 call wall) |
| Max pain (Nov 20) | $12.00 |
| Dealer gamma regime (estimate) | Nov 20 expiration: positive, so hedging tends to dampen moves. The whole chain is estimated negative. Flip level: n/a (not computable today) |
| Volatility condition | Neutral. IV rank 30/100 (29.88). Premium is thin: options are priced ~34 vol pts below delivered movement |
| Technical check | Confirms (bearish, 3-day target $9.45 and 5-day target $9.35) |
| Best-fitting strategy | Nov 20 $9.50/$8.50 put debit spread (if RGTI stays below $10.50) |
| Analysis invalidated if | RGTI closes above $10.50 |
1 · What matters today
RGTI closed Friday at $9.62 after falling 18% in five sessions. Our read of the options market for the next five days is slightly bearish. Short-dated traders have been piling into calls, but that kind of call-chasing has repeatedly failed to stop this stock's slide, and price is still below every major moving average.
The options market is pricing a move of about $1.24 either way by November 20, which gives a range of roughly $8.38 to $10.86. The big floor in the options chain is the $8 strike, where put contracts are piled up. The level that would change our mind is $10.50: a close above it means buyers have taken control of the week.
Both chart-based technical models also lean lower, targeting roughly $9.35–$9.45.
2 · What the options market is pricing
What changed this week
The week was a round trip that ended badly. RGTI rallied toward $13 on November 9, then gave it all back and finished the five sessions down 18.1%. It is also down 18.5% over 20 sessions and 36.6% over roughly two and a half months. The short-, medium- and long-term trend reads all point the same way, down. A bullish turn in our flow-momentum gauge on November 9 was quickly overrun by that slide.
Implied volatility (IV) is the market's estimate of how much RGTI will move, baked into option prices. It eased 8% over five sessions even as the stock fell.
Two ratios moved in opposite directions:
- Put/call open interest fell. Open interest means contracts currently held open. For every call held open there are now 0.89 puts, below the 7-day average of 0.97. Puts were closed and calls added: Friday alone saw roughly +5,500 call contracts and −8,200 put contracts of open interest.
- Put/call volume jumped. This ratio measures how much put trading there is relative to calls, and above 1 means puts dominate. It came in at 0.82, against a 7-day average of 0.62 and a 14-day average of 0.53. That is an unusually heavy put-trading pace for this name.
The biggest non-expired open-interest change was in the November 20 $15 puts, which shed 1,536 contracts. These are deep in-the-money positions being closed out after the decline.
In the settled retrospective, the November 13 $12.50 puts lost 2,308 contracts of open interest going into Friday's expiration. That expiration's max pain was $11.50, and the stock settled nearly $2 below it.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. Into November 20 it is ±$1.24 (±12.94%) around $9.62, which works out to $8.38 – $10.86. The at-the-money options on that expiration carry about 93% IV, richer than the chain's blended 80.3%.
| Expiration | Implied move | Range around $9.62 |
|---|---|---|
| Nov 20 | ±12.94% | $8.38 – $10.86 |
| Nov 27 | ±14.98% | $8.18 – $11.06 |
| Dec 11 | ±21.47% | $7.55 – $11.69 |
| Dec 18 | ±26.41% | $7.08 – $12.16 |
The step from the first rung to the second is small, because the November 27 options carry lower IV than the front week. The market is paying extra for movement over the next five sessions specifically.
Volatility
At-the-money IV is 80.28%. Two measures put that in context:
- IV rank is 29.88/100. IV rank shows where today's IV sits versus the past year, and 30/100 means it is cheaper than about 70% of the past year's range.
- IV percentile is about 20. IV was lower than today on only about 20% of the past year's days.
IV rose 1.3% on Friday and is up 19.9% over 30 sessions. It sits just above its 30-day average of 78.2% and just below its 90-day average of 81.6%. The ~60-day IV reads 83.9%.
The front-month term-structure read is unavailable today because it was an expiry day. Term structure means comparing option prices across different expiration dates.
The bigger story is the stock itself. Its 20-day realized volatility is about 115%, and its 10-day reading is near 152%. Both are well above this stock's own recent norm. "Unusually high" here means unusual for RGTI, not versus the broader market.
Premium is thin, not rich. The volatility risk premium is the gap between how much movement options are priced for and how much RGTI has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them.
- Right now the gap is about 34 vol points negative: options are priced well below the movement the stock has just shown.
- The percentile is 3/100. That percentile shows where today's gap sits versus this stock's own recent readings, and 3/100 means richer than only 3% of them. It is about as thin as this premium gets for RGTI.
- The gap was positive at roughly 12–15 points through November 5. It flipped negative on November 6, as the violent ±10–19% daily swings entered the 20-day window, and it bottomed near −43 points on November 11.
That combination, IV rank 30 and a 3rd-percentile premium over delivered movement, favors owning premium through defined-risk debit structures this week rather than selling it.
Skew and sentiment
Skew means that puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection. RGTI has it backwards right now. Calls 25 delta out the money carry about 85.5% IV versus 74.5% for comparable puts, so calls are roughly 11 vol points richer than puts. The norm for this name over the past 60 days is about 5 points, which makes this flatter skew stretched versus its own history.
Sentiment in short-dated options reads bullish:
- The 0–7 day expirations score +68 and the 7–30 day expirations score +55. Both are well above their 7-day averages of +32 and +33.
- The longer buckets are split, so the overall regime reads "Mixed."
In context, we read this flow as bounce speculation into a stock that is still breaking down, not as conviction. Upside chasing in weekly calls has repeatedly coincided with further declines in this name. The same session also saw put volume running more than double its 60-day norm. Traders are buying lottery-ticket calls and protective puts at the same time.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 200-day moving average | $16.56 | Long-term trend line, far overhead |
| 50-day moving average | $13.56 | The November 9 rally failed just below it |
| Swing resistance cluster | $12.59 – $13.41 | Prior pivot highs (heuristic estimate) |
| Call wall + max pain (Nov 20) | $12.00 | Heaviest call open interest (5,823 contracts) and the max-pain strike. Also the whole chain's call wall and largest-gamma strike |
| 20-day moving average | $11.44 | Short-term trend, about 16% above spot |
| Unfilled gap / swing resistance | $10.67 – $11.12 | November 12 gap-down zone |
| Upper implied range | $10.86 | Top of the 1σ expected move into Nov 20 |
| Invalidation level | $10.50 | A close above it breaks the bearish tilt |
| Gamma strike | $10.00 | Second-largest gamma concentration, where Friday's heaviest call volume traded |
| Spot | $9.62 | Friday's close |
| 52-week low / swing support | $9.19 | The only structural support left below |
| Lower implied range | $8.38 | Bottom of the 1σ expected move |
| Put wall (Nov 20) | $8.00 | Heaviest put open interest (4,077 contracts). Also the whole chain's put wall |
The November 20 expiration's own walls match the whole chain's at $12 and $8. Max pain at $12.00 sits far above the expected range. It is a reference point here, not a magnet anyone should lean on with the stock 25% below it.
Max pain is the price where the most option value would expire worthless, and expirations sometimes gravitate toward it. A call wall or put wall is the strike with the biggest pile of open call or put contracts, and these often act like magnets or barriers.
Positioning and unusual flow
Dealer gamma (estimates). Market makers hedge the options they've sold. For the November 20 expiration on its own, one rough estimate suggests a positive regime, where their hedging tends to dampen moves. The whole chain is estimated negative, a regime where hedging tends to amplify moves, so the dampening mostly applies inside this week's strikes. A gamma-flip level could not be computed today.
Three trades stood out in Friday's flow:
- December 18 $9 puts. 10,127 contracts traded against just 623 open, about $704,000 in premium near the $0.695 midpoint. That is by far the biggest money flow in the chain: someone was buying or selling month-out downside exposure just below spot in size.
- November 20 $10 calls. 3,304 contracts traded, about $104,000 in premium, more than the 2,955 contracts already open. This is the short-dated bounce bet in a single line.
- November 20 $7.50 puts. 504 contracts traded on a strike with no prior open interest. This is cheap crash insurance that sits below the $8 wall.
3 · Technical check
3-day report (target November 18). The chart model is bearish, with a $9.45 target and a projected range of $9.15–$9.75. That target sits inside the options-implied range, so it Confirms the tilt.
5-day report (target November 20). Also bearish, targeting $9.35 with a model range of $9.05–$10.15. That also Confirms. The 5-day model flags $9.02 support and $10.07 resistance. Its dominant scenario, a bear-flag breakdown, is invalidated on a close above $10.07.
The decisive readings are:
- Trend strength. ADX is at 26.3 and rising, with sellers' directional pressure (34.0) far outpacing buyers' (18.8). That marks a strong, established downtrend.
- Money flow. Chaikin money flow is −0.263, still distribution but improving. That leaves the door open to a relief bounce.
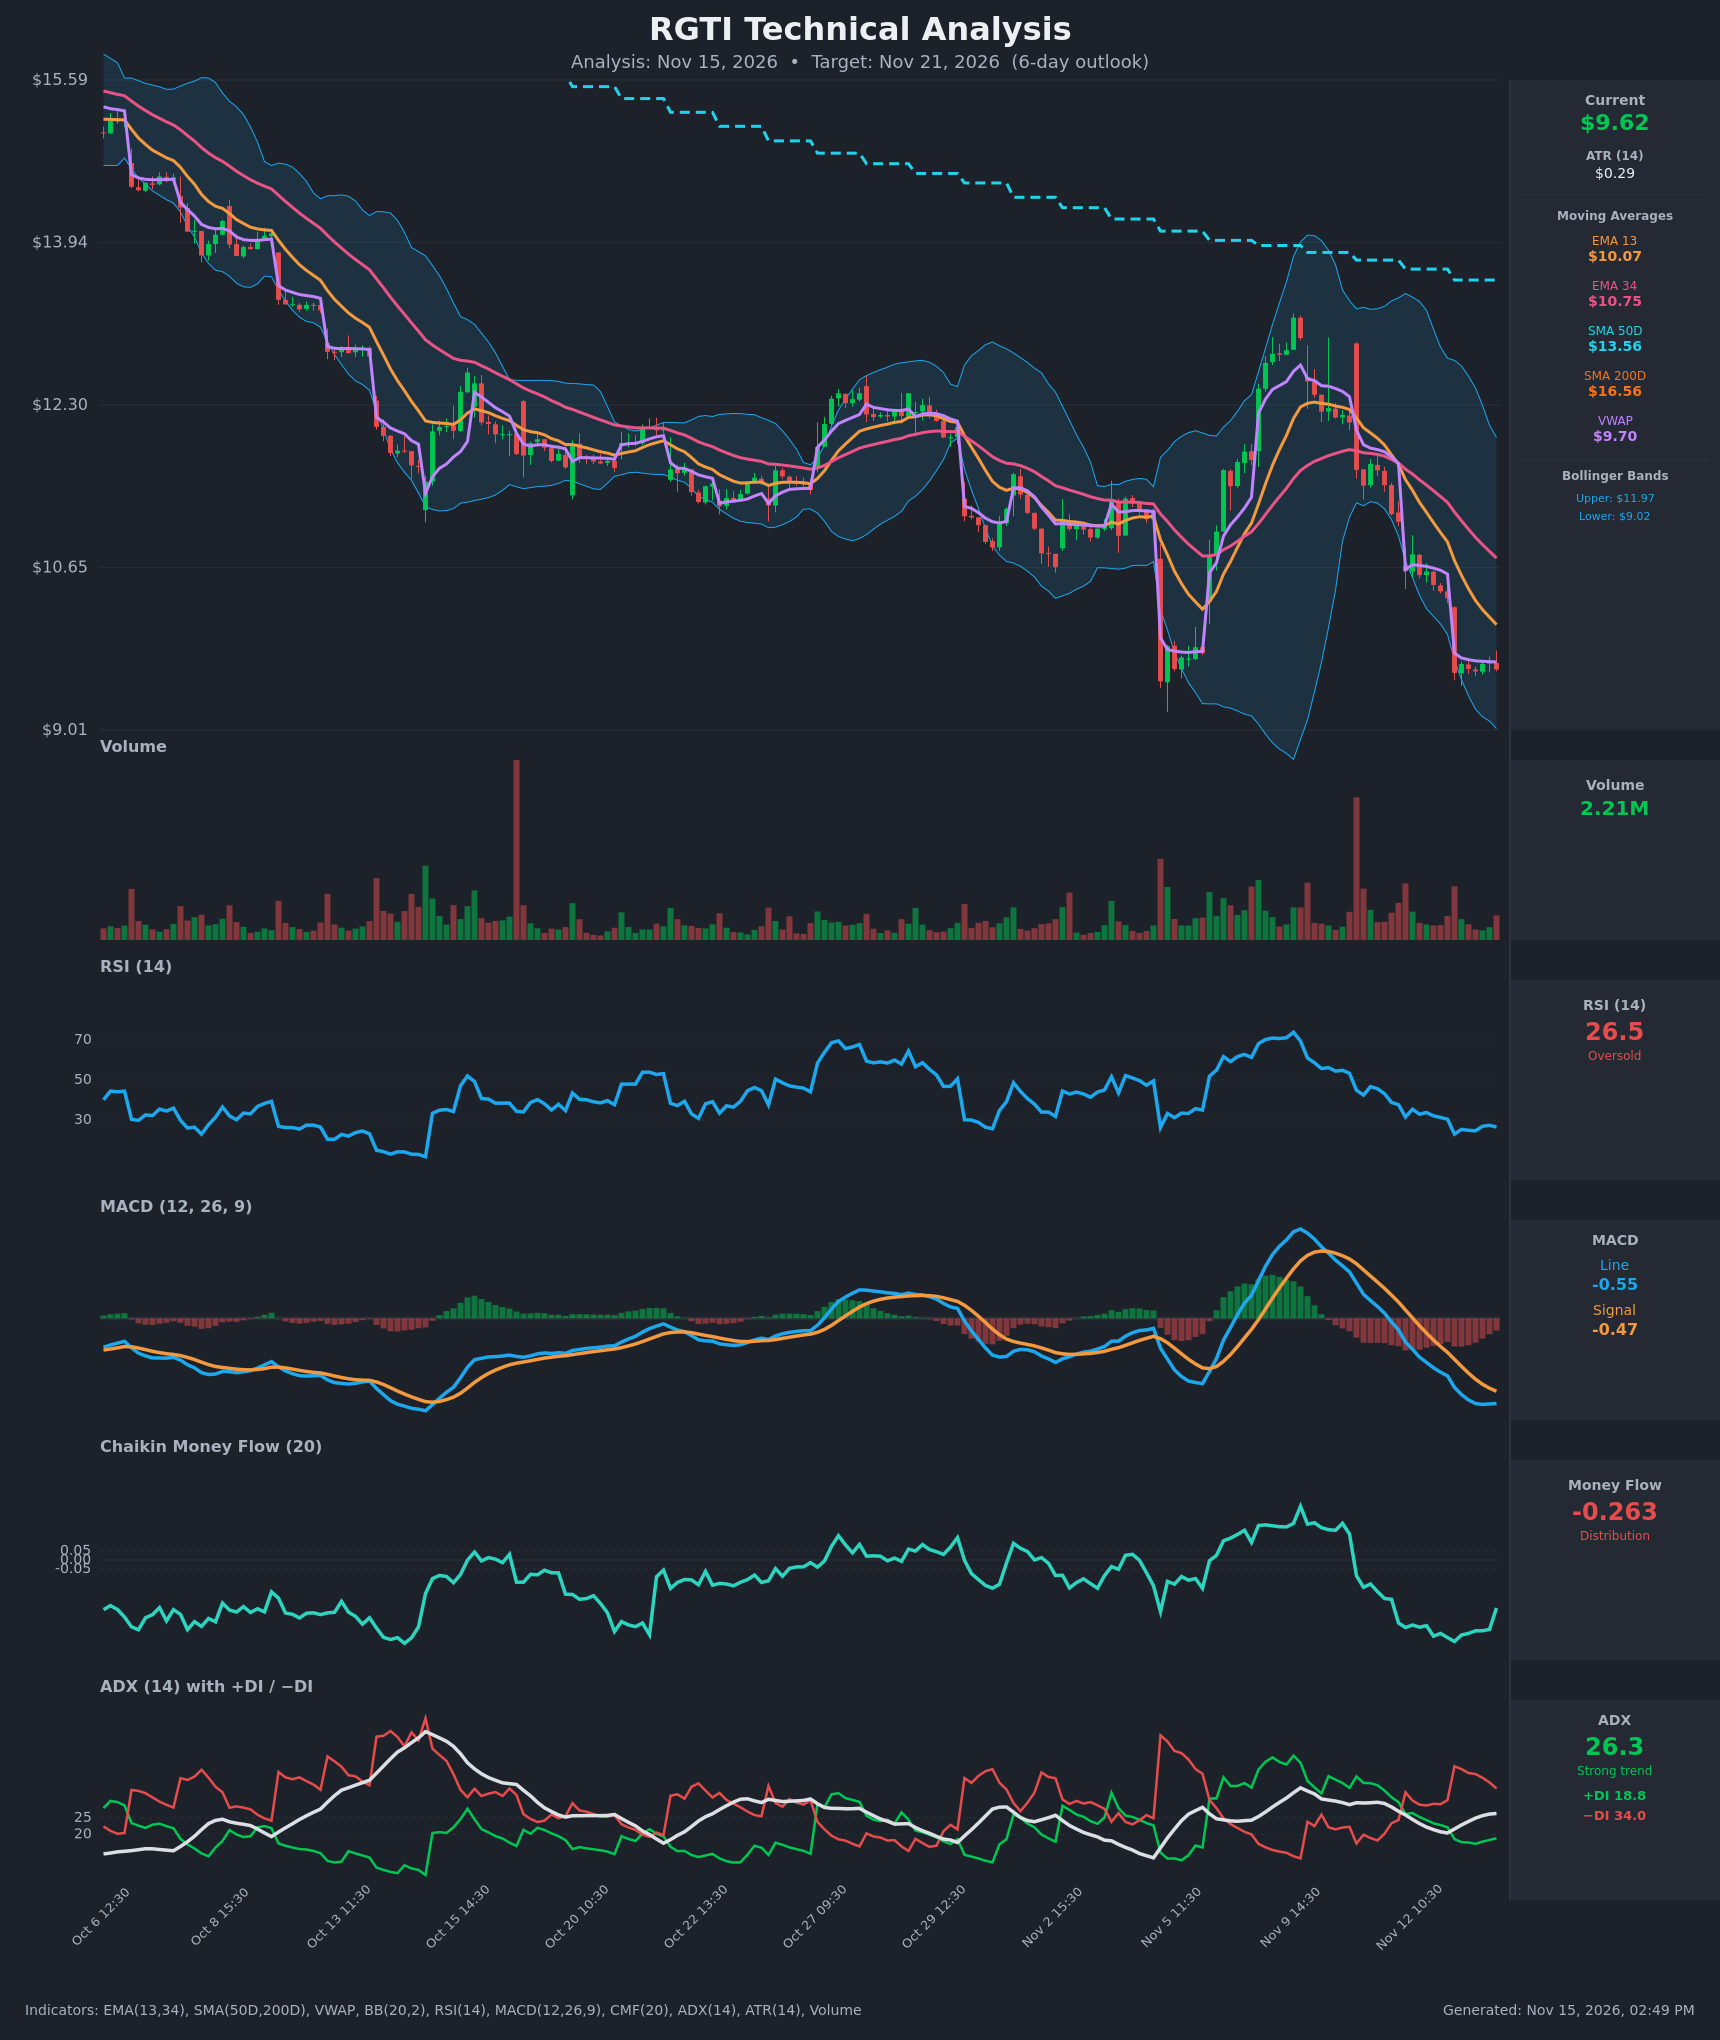
Model vs. Market: The options market implies $8.38–$10.86 into November 20, while the 5-day technical model targets $9.35. The chart model expects a modest drift into the lower half of a range the options market prices as roughly symmetric. A close back above $10.07–$10.50 would settle the question in the bulls' favor.
The TA shaded our strike selection: the bearish spread's break-even ($9.16) sits right at the 3-day model's $9.15–$9.20 support zone, and the range structure is centered on $9.50.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If RGTI pushes above the call wall ($12.00): Getting there means a 25% rally through the $10.67–$11.12 gap zone and the 20-day average. The heaviest call open interest sits at $12, and that kind of concentration tends to slow rallies as hedging flows build. A clean break would leave thinner positioning above until the $12.59–$13.41 swing cluster.
If RGTI drifts between the walls: This is the most likely path given the expected move: chop between roughly $8.38 and $10.86. On the November 20 expiration alone, the positive gamma estimate suggests hedging flows tend to cushion moves. The $10 strike, with its large gamma concentration, can act as a short-term ceiling. Max pain at $12.00 is too far away to exert much pull this week.
If RGTI breaks below the put wall ($8.00): That requires losing the $9.19 52-week low first. Below that level there is no structural support until the $8 put pile. Across the whole chain, one rough estimate puts dealers in a negative-gamma posture, where hedging tends to amplify selling rather than cushion it. A break of $9.19 could therefore travel faster than the expected move implies.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 13, 2026. All structures are hypothetical. Verify live prices before trading, because these will be stale by the open.
Because premium is unusually thin versus delivered movement, the debit structures lead this week. A debit spread costs you a fixed amount up front, and that amount is your maximum loss.
If you lean bearish: November 20 $9.50/$8.50 put debit spread
- Trade: Buy the Nov 20 $9.50 put ($0.395) and sell the Nov 20 $8.50 put ($0.055)
- Debit: $0.34 ($34 per spread) · Max profit: $66 at or below $8.50 · Max loss: $34 · Break-even: $9.16
- Why it fits: It matches the slightly bearish read, and both TA models target $9.35–$9.45. You're buying options while premium sits in the 3rd percentile versus delivered movement, and the short strike stays above the $8 put wall.
- Makes sense only if: RGTI stays capped below $10.00–$10.07 early in the week
- Invalidated if: RGTI closes above $10.50
- Managing it: Take profits at about 50–60% of max value, or roughly $0.70 spread value. Exit by November 19 regardless, rather than holding into expiration-day noise. The trend is down across every horizon, which argues for staying short-dated and banking gains early.
- Liquidity note: The $9.50 puts traded 5¢ wide ($0.37/$0.42, about 13% of the mid) and the $8.50 puts 9¢ wide. Expect slippage and work limit orders near the mid.
- Analyze this position →
If you expect the range to hold: November 20 $9/$9.50/$10 put butterfly
- Trade: Buy the Nov 20 $10 put ($0.685), sell two Nov 20 $9.50 puts ($0.395 each), and buy the Nov 20 $9 put ($0.20)
- Debit: $0.095 ($9.50 per butterfly) · Max profit: $40.50 at $9.50 · Max loss: $9.50 · Break-evens: $9.095 and $9.905
- Why it fits: It pays most if RGTI drifts slightly lower and settles near $9.50, close to both TA targets. On the November 20 expiration, the positive gamma estimate favors some pinning. An iron condor is the usual range trade, but here it would mean selling premium that hasn't been rich lately, and the credits on offer are tiny. The butterfly expresses the same view for a small debit.
- Makes sense only if: Realized volatility cools from its recent extreme pace
- Invalidated if: RGTI closes above $10.50 (or below $9.00 heading into the final two sessions)
- Managing it: Butterflies gain value late. Take profits if the spread reaches $0.25–$0.30, and close by November 19 if price sits outside the break-evens.
- Liquidity note: The $10 puts traded 9¢ wide ($0.64/$0.73) and the $9.50 puts 5¢ wide. A four-leg fill can easily lose a few cents of a $0.095 debit, so enter as a single order at a limit price.
- Analyze this position →
If you lean bullish: November 20 $10/$11 call debit spread
- Trade: Buy the Nov 20 $10 call ($0.315) and sell the Nov 20 $11 call ($0.10)
- Debit: $0.215 ($21.50 per spread) · Max profit: $78.50 at or above $11 · Max loss: $21.50 · Break-even: $10.215
- Why it fits: It is a defined-risk way to join the short-dated call chase if the oversold bounce the TA flags actually materializes. Cheap premium keeps the cost low, and the short strike sits below the $11.12 swing resistance.
- Makes sense only if: RGTI reclaims $9.70–$9.85 early in the week
- Invalidated if: RGTI closes below $9.19
- Managing it: This trade fights the trend on every horizon, so treat it as a quick trade. Take 50% of max value if offered, and exit by November 18 if it hasn't moved.
- Liquidity note: The $10 calls traded 5¢ wide ($0.29/$0.34, about 16% of the mid) and the $11 calls 2¢ wide. Volume was heavy at both strikes, but spreads are large relative to the prices.
- Analyze this position →
If none of these: no trade
Standing aside is a legitimate choice this week, for three reasons:
- Daily swings are extreme. RGTI's recent moves have run 10–19% a day, about 150% annualized realized volatility. That can blow through any five-day structure overnight.
- Bid-ask spreads are costly. Spreads of 12–20% of each option's price eat a meaningful share of any edge.
- Premium is too thin to sell, and the directional lean is only a tilt. If you can't watch the position daily or tolerate a full max loss, waiting for realized volatility to cool will give you a cleaner setup.
6 · Quick FAQ
What is RGTI's expected move this week? About ±$1.24 (±12.94%) into November 20, or roughly $8.38–$10.86, based on the options market's straddle pricing as of November 13, 2026.
Is RGTI expected to go up or down over the next week? Options positioning as of November 13 leans slightly bearish: call-chasing persists inside a downtrend that hasn't broken. That's a read of what traders have done, not a forecast. The actionable map is the $8.38–$10.86 range, the $8.00 put wall and the $12.00 call wall.
Are RGTI options expensive right now? No. IV rank of 30/100 says option prices are higher than only about 30% of the past year's range. On top of that, options are priced about 34 vol points below the movement RGTI has actually delivered, richer than only 3% of this stock's own recent readings. That favors buying defined-risk structures over selling premium.
Where is RGTI's biggest options support and resistance? The put wall is at $8.00 and the call wall at $12.00 for the November 20 expiration. The $9.19 52-week low is the nearest structural support.
What invalidates this week's read? A close above $10.50.
Methodology & disclosures. Data: end-of-day options-chain snapshot for RGTI, 2026-11-13, generated 2026-11-15T14:49:23.466Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.