SMH Options Price a ±$40.87 Move Into November 13, With Positioning Leaning Toward the $445 Put Wall
After an 11% five-day slide, SMH options imply a $423.09–$504.83 range into the November 13 expiration. Steep put skew, a 37,000-contract put build at $445, and negative dealer gamma tilt the read slightly bearish, and premium is cheap relative to how violently the ETF has actually been moving.
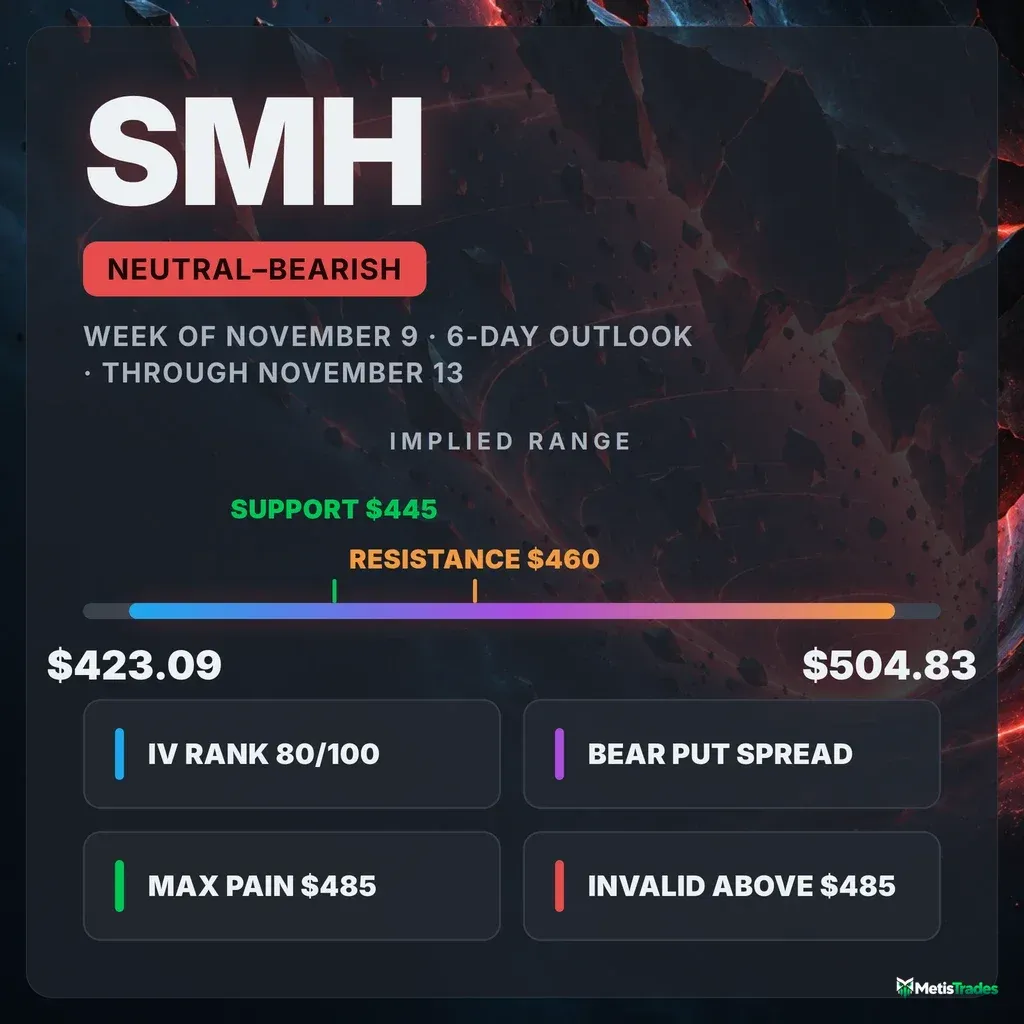
The options market implies a $423.09–$504.83 range into the Friday, November 13 expiration. This article covers what is driving that range and three defined-risk ways to trade it.
Published Saturday, November 7, 2026 · Data as of Friday, November 6, 2026 close
Explore the live SMH options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bearish |
| Options-implied range (into November 13) | $423.09 – $504.83 (±8.81%, ±$40.87) |
| Major support | $445 (put wall, November 13 expiration) |
| Major resistance | $460 (call wall, November 13 expiration, now just below spot and acting as a pivot). Next overhead levels are $475–$485. |
| Max pain (November 13) | $485 |
| Dealer gamma regime (estimate) | Negative, so hedging tends to amplify moves. No flip level is available today (estimate unavailable). |
| Volatility condition | Rising. IV rank 80/100, ATM IV 53.05%. Premium is thin: options are priced about 9 vol pts below the movement SMH has actually delivered. |
| Technical check | Confirms (bearish on both the 3-day and 6-day reports). 3-day model target $458 (range $447–$468); 6-day model target $455 (range $434–$478). |
| Best-fitting strategy | Bear put debit spread (Nov 13 $465/$445), conditional on SMH staying below $475 |
| Analysis invalidated if | SMH closes above $485 |
1 · What matters today
SMH closed Friday at $463.96 after falling 11.2% in five sessions. Options positioning leans slightly bearish into the November 13 expiration. The main reason is that traders are paying far more than usual for downside protection, and they parked a fresh pile of roughly 37,000 put contracts at the $445 strike for that expiration.
The options market is pricing a move of about $40.87 either way, which gives a $423.09–$504.83 range. That figure is the expected move: the size of move the options market is pricing in, derived from what straddles cost.
The level that changes the picture is $485. A close above it would mean the bearish tilt has failed. Below $445, positioning suggests moves could speed up rather than slow down.
Option prices look high on a calendar basis, but they are actually cheap compared with how violently SMH has been moving. That favors buying defined-risk spreads over selling premium. Both chart-based technical reports also lean bearish.
2 · What the options market is pricing
What changed this week
This was a violent week:
- Price: SMH dropped 11.2% over five sessions and is down 23.1% over the past month. Thursday's session gapped down from $504.27 and closed at $447.73. Friday gapped back up 5.74% to open at $473.41, then faded to $463.96.
- Implied volatility (IV): IV is the market's estimate of how much SMH will move, baked into option prices. It jumped 24.9% over five days. It cooled 9.7% on Friday, and IV rank still rose to 80 against a 7-day average of about 60.
- Open interest (OI): OI means contracts currently held open. The put/call OI ratio climbed to 1.77, against a 7-day average of 1.56. In plain terms, there are now 1.77 puts held open for every call, and that number keeps creeping up.
- Biggest single change: OI in the November 13 $445 puts jumped by 37,266 contracts in one day, from 418 to 37,684.
- Daily volume: Put/call volume cooled to 1.15 from a 7-day average of 2.14. The panic-hedging pace of Thursday (4.15) eased on Friday's bounce.
The short-, medium- and long-term trend reads all point the same way, down, so Friday's pop is a bounce inside an aligned downtrend rather than a split signal.
Expected move
Into the November 13 expiration, the options market is pricing about ±8.81%, or ±$40.87, around the $463.96 chain price. That puts the range at $423.09–$504.83. It is a one-standard-deviation band, meaning it is roughly the range the market treats as "normal" for the period, not a hard boundary.
| Expiration | Implied move | Range around $463.96 |
|---|---|---|
| Monday, November 9 (near the 3-day checkpoint) | ±4.40% | $443.55 – $484.37 |
| Friday, November 13 (target) | ±8.81% | $423.09 – $504.83 |
| Friday, November 20 | ±11.81% | $409.17 – $518.75 |
| Friday, December 4 | ±14.78% | $395.39 – $532.53 |
The steps between rungs are steep for a broad sector ETF. The jump from ±4.40% to ±8.81% in just four days shows how much movement is being priced into the target week specifically.
Volatility
Level: At-the-money IV sits at 53.05%.
IV rank: IV rank shows where today's IV sits versus the past year. At 80/100, today's IV is higher than 80% of the past year's range. The IV percentile of 87 means it is higher than about 87% of the past year's daily readings.
Direction: IV is up 61% over the past month and well above both its 30-day average (37.5%) and 90-day average (41.9%). Friday's 9.7% dip trimmed only a small part of that surge.
Across expirations: Comparing option prices across expiration dates is called term structure. The standard front-month reading is unavailable today because Friday was an expiry day. The per-expiration numbers still tell the story:
- The November 13 options carry an at-the-money IV near 63.6%.
- Options roughly two months out carry about 49.0%.
So near-dated options are clearly richer, which is the shape you see when traders want protection now.
Versus this stock's own norm: These comparisons are against SMH's own recent history. "Unusual" here means unusual for SMH, not versus the broader market.
- 20-day realized volatility of 62.1% is running far above its typical level.
- The past week's movement is running about 1.5 times faster than the month's pace, so price swings are still accelerating.
Premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much SMH has actually delivered. When it's positive, option sellers have been collecting more than realized movement cost them. Right now it is negative: options are priced about 9 vol points below the 20-day realized movement.
That reading sits in the bottom tenth of SMH's own recent readings, at a percentile of 9/100. In other words, today's premium is thinner than 91% of the stock's recent gaps.
The gap has slid steadily. It was about 11 points positive in late October, crossed below zero at the end of the month, and widened sharply after Thursday's crash. There is no earnings event behind it, because SMH is an ETF. It is simply realized movement outrunning what option prices were charging.
The verdict: IV rank 80 says options are expensive versus the past year. The 9th-percentile premium says they are cheap versus what the ETF is actually doing. Together they favor owning premium through defined-risk debit spreads over collecting it this week.
Skew and sentiment
Skew: Skew means that puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection.
- Puts 25 delta out are running 13.5 vol points over the matching calls, at 60.1% versus 46.5%.
- SMH's 60-day norm is only 3.8 points, and even the 7-day average is 10.2.
- That is one of the most stretched readings this ETF has shown recently. Traders are paying a heavy premium to protect against another drop.
Put/call ratio: This measures how much put activity there is relative to calls; above 1 means puts dominate. On volume it is 1.15, which is calmer than this week's average but still put-heavy. On open interest it is 1.77 and rising.
Big-trader sweeps: Among the unusually large trades, put-side sweeps outnumbered call-side 17 to 8. That is a lopsided reading by this ETF's own standards.
Short-dated sentiment:
- Options expiring within a week read only mildly bearish (–10), softened by Friday's call buying.
- The 7–30 day window, which includes the target expiration, reads firmly bearish (–59).
- Across the whole curve, every expiration bucket leans bearish, a broadly bearish regime.
The counterweight: Friday's newly opened contracts tilted toward calls. That build was unusually heavy for this name and is the one bullish thread in the data.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Whole chain's heaviest call strike (Nov 20 expiration) | $650 | 61,489 contracts, but far out of reach. This is legacy positioning, not a live ceiling. |
| 50-day moving average | $565.64 | Price sits nearly 18% below it. |
| Swing resistance / 20-day moving average | $538.84 / $536.94 | Where the late-October bounces stalled. |
| 200-day moving average / swing resistance | $521.76 / $520.53 | The long-term trend line, now 11% overhead. |
| Upper rail, Nov 13 expected move | $504.83 | The top of what options are pricing for the week. |
| Swing resistance / Thursday gap origin | $503.63 / $504.27 | Unfilled gap; sellers defended here. |
| Whole chain's put wall and largest gamma strike | $500 | 70,376 put contracts across all expirations. |
| Max pain (Nov 13) | $485 | The price where the most option value would expire worthless. Expirations sometimes gravitate toward it. It sits $21 above spot. |
| Large gamma strikes | $480 / $475 | Heavy put OI; the $475 Nov 13 puts hold 21,171 contracts. |
| Friday's gap-up open | $473.41 | Where Friday's rally began before fading. |
| Spot | $463.96 | Friday's close. |
| Call wall (Nov 13) | $460 | The strike with the biggest pile of open call contracts; these often act like magnets or barriers. This one is thin at 589 contracts and now sits just below spot, so treat it as a pivot. |
| Large gamma strike | $450 | Heavy put OI cluster. |
| Thursday's close | $447.73 | The crash low close that Friday bounced from. |
| Put wall (Nov 13) | $445 | The strike with the biggest pile of open put contracts. At 37,684 contracts it is the week's anchor and the second-largest gamma strike. |
| Lower rail, Nov 13 expected move | $423.09 | The bottom of what options are pricing for the week. |
Note the disagreement between the two sets of walls. The November 13 expiration's own walls are $460 (calls) and $445 (puts). The whole chain's heaviest strikes sit at $650 (calls) and $500 (puts). For this six-day window, the November 13 levels are the ones that matter.
Positioning and unusual flow
Dealer gamma (estimate): Market makers hedge the options they've sold. In a negative-gamma regime, their hedging tends to amplify moves rather than dampen them.
- One rough estimate puts both the whole chain and the November 13 expiration in that negative regime.
- No gamma flip level could be estimated today. A flip level is the price below which market-maker hedging tends to accelerate selling rather than cushion it.
- Practically, this means the ±$40.87 band is not likely to feel sleepy. Both directions can extend.
Notable flow:
- Nov 13 $445 puts: Open interest rose by 37,266 contracts in a single day, with about $1.6 million in premium traded Friday. Whether this was protection bought or puts sold, it turns $445 into the expiration's center of gravity on the downside.
- Nov 13 $467.50 puts: 1,129 contracts traded against just 52 open, about $2.0 million in premium. Someone wanted at-the-money downside protection on Friday's bounce.
- Nov 11 $475 calls: 1,596 contracts traded against 11 open, roughly $1.27 million. This is a short-dated bet on a quick relief rally, and it is the main bullish counterweight.
3 · Technical check
3-day report (target November 10): The model is bearish, with a target of $458 and a projected range of $447–$468.
- That target sits comfortably inside the options market's range, so this read confirms the positioning tilt.
- The report reads the $455–$465 consolidation as a bearish flag under an unfilled gap.
- Its trend-strength gauge sits at 46 with sellers firmly in control, and money-flow readings show heavy, persistent distribution.
- It identifies support at $455 and resistance at $467. Its dominant scenario is invalidated by an hourly close above $469.
6-day report (target November 13): The model is also bearish, with a target of $455 and a range of $434–$478. It also confirms, with a tighter band than options imply. It flags support at $446 and resistance at $472, and its breakdown scenario is invalidated by a close above $472.
Both reports note a short-term momentum upturn: the MACD crossover and RSI recovering from 17. They treat it as a relief bounce rather than a reversal. That is the main risk to the tilt.
Model vs. Market: The options market implies $423.09–$504.83 into November 13. The 6-day technical model targets $455, with a $434–$478 range. The chart model sees a narrower, lower-centered week than the options market is bracing for. A decisive break below $445 or above $478 would show which side underestimated the move.
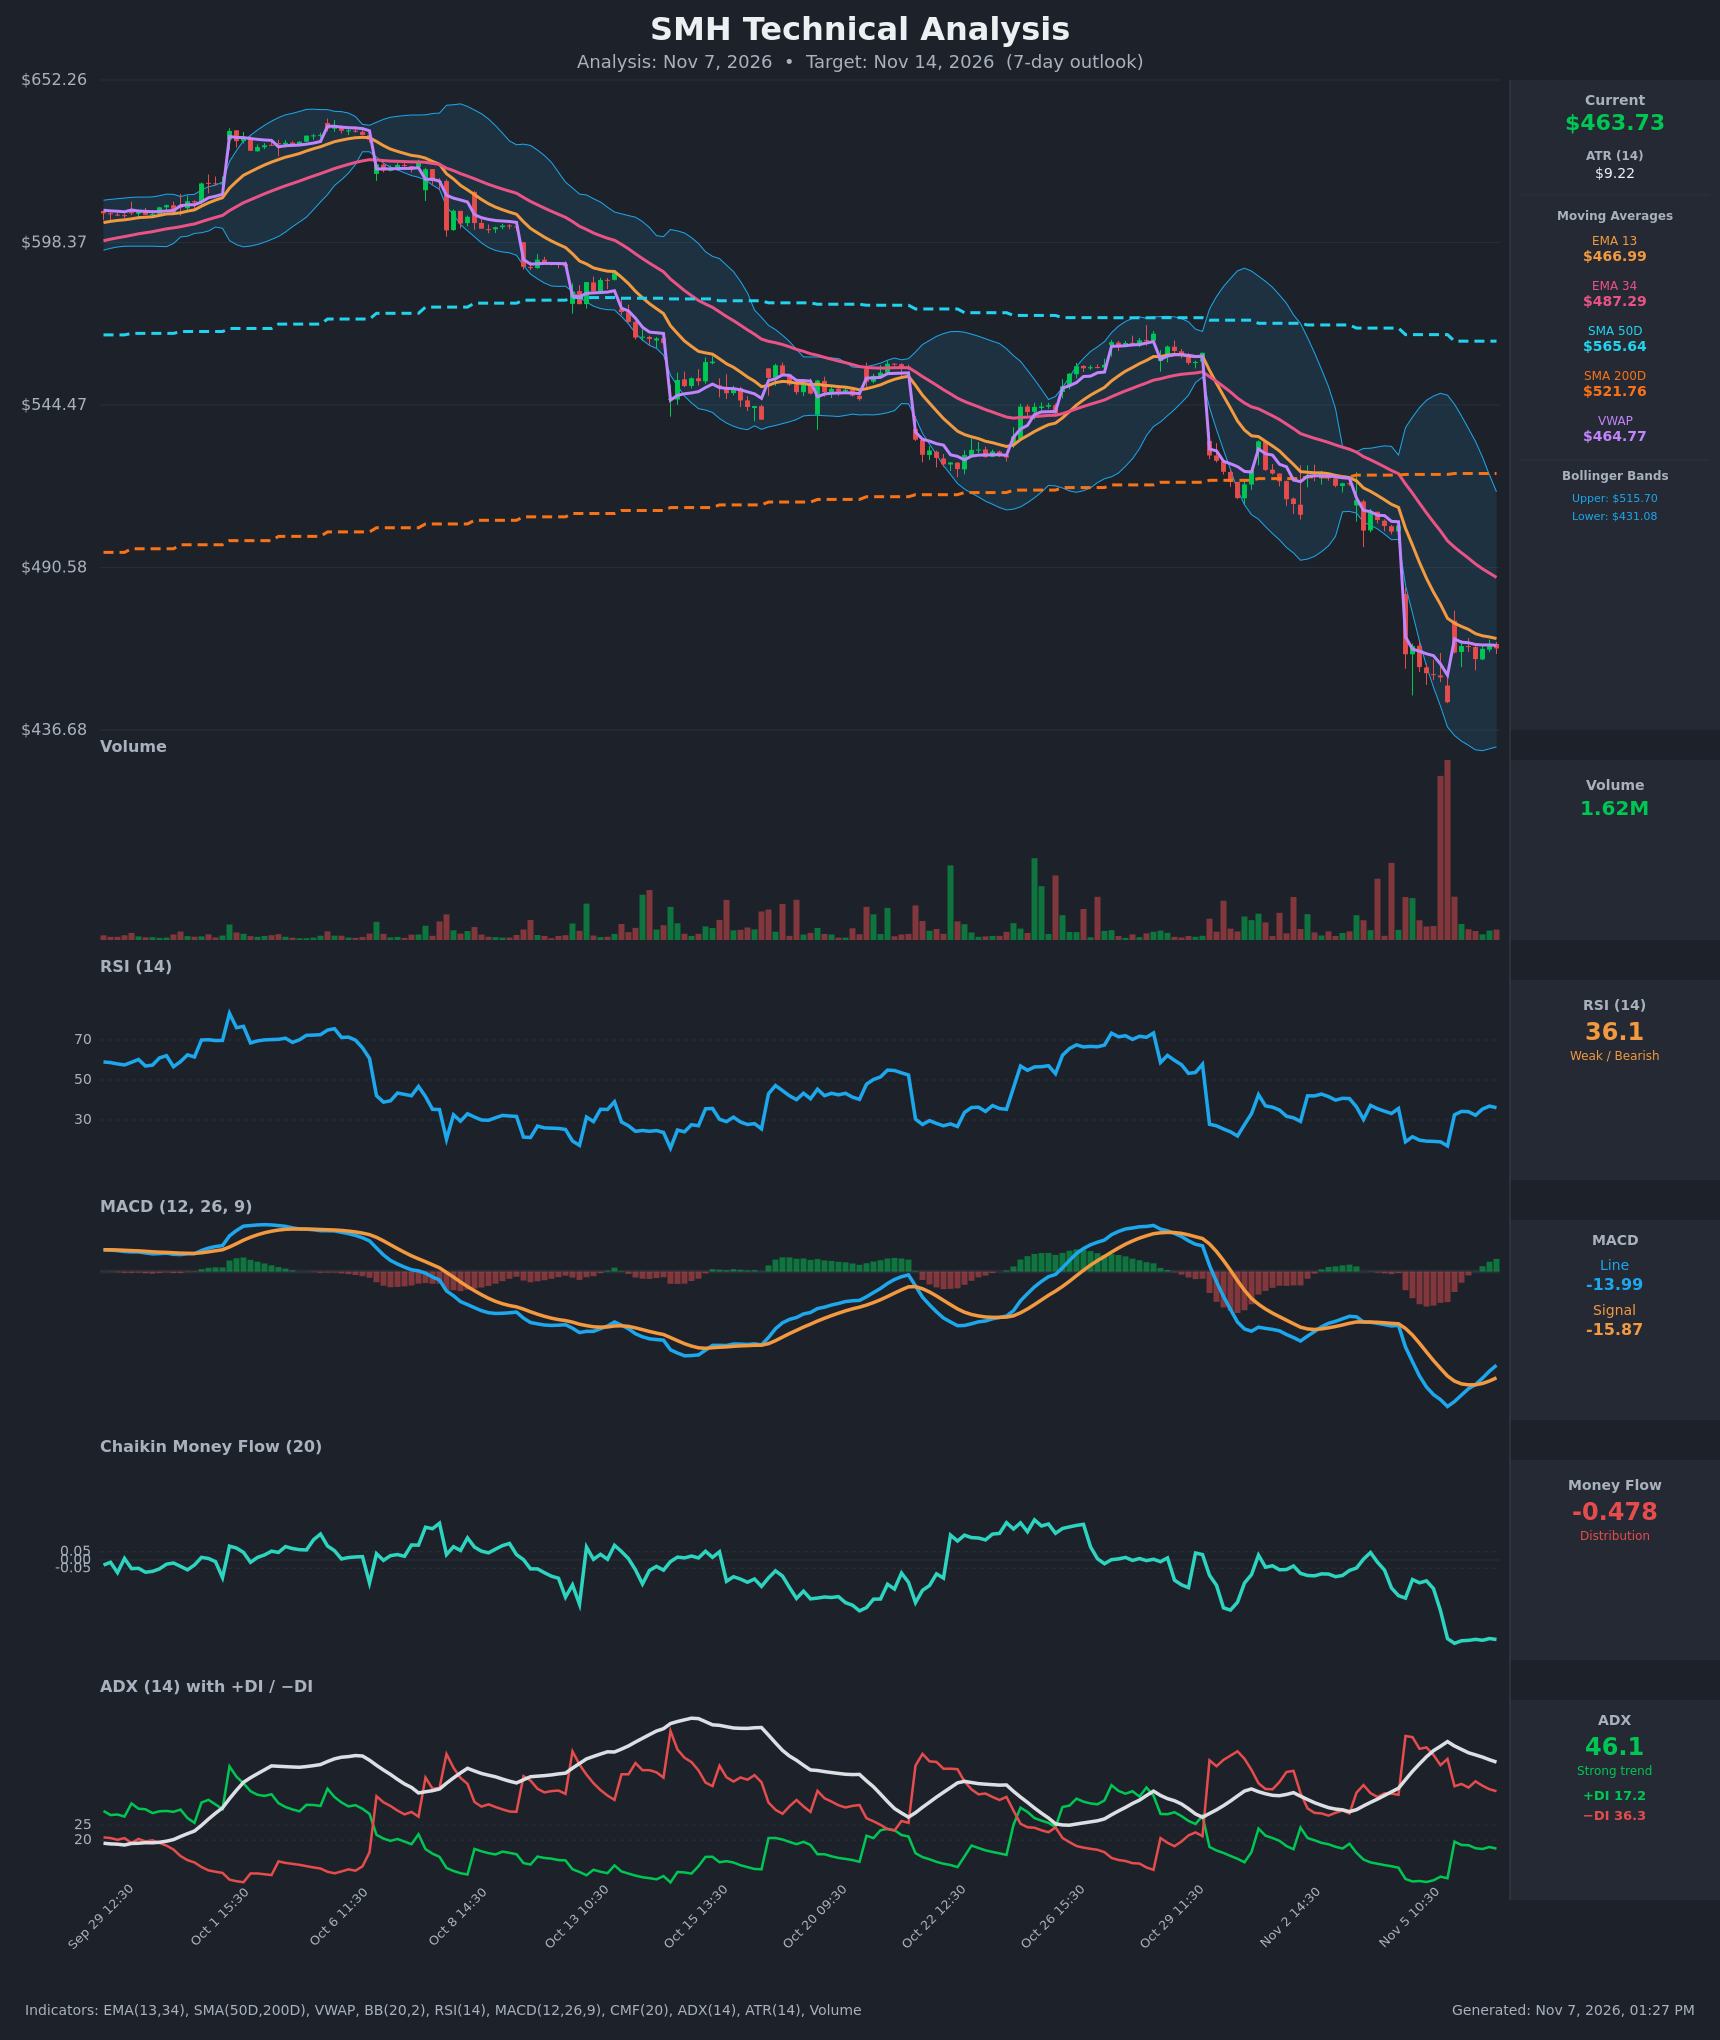
Full technical write-ups: 3-day report → · 6-day report →
The technical confirmation shaped one strike choice below. The bearish spread's short strike is placed at the $445 put wall, just under both reports' $446–$455 targets.
4 · Three ways the next six days can go
If SMH holds above the call wall ($460) and climbs toward max pain ($485): Friday's call buying and the oversold bounce could carry price into the $475–$485 zone, where heavy put open interest at $475 and $480 clusters. With negative gamma, a squeeze could travel quickly. Max pain at $485 is a plausible magnet into the November 13 expiration. A close above $485 kills the bearish tilt.
If SMH chops between $445 and $475: This is the pinning case. The huge $445 put pile below and the dense put strikes at $475–$480 above bracket the week, and expiring open interest tends to pull price back toward the middle. Both technical reports' targets ($455–$458) sit in this lane.
If SMH breaks below the put wall ($445): This is the acceleration case. The 37,684-contract wall gives way, and one rough estimate suggests market-maker hedging in this negative-gamma regime amplifies selling rather than cushioning it. Thinner positioning sits beneath, and the lower expected-move rail at $423.09 becomes the next reference point.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 6, 2026. All structures are hypothetical. Verify live prices before trading; these will be stale by the open.
Because premium is thin relative to delivered movement, the debit structures lead this week. In a debit spread, you pay up front for a defined bet; your maximum loss is what you paid.
If you lean bearish: Bear put debit spread
- Trade: Buy the November 13 $465 put, sell the November 13 $445 put.
- Debit: $7.53 ($752.50 per spread) · Max profit: $12.48 ($1,247.50) · Max loss: $7.53 ($752.50) · Break-even: $457.48
- Why it fits: Several readings line up here:
- The short strike sits at the $445 put wall.
- Steep put skew makes the $445 put you sell relatively rich.
- Thin premium makes buying cheap compared with realized movement.
- Both technical targets ($455 and $458) land inside the profit zone.
- All three trend reads point down.
- Makes sense only if: SMH stays below Friday's $473 gap-up open and the bounce keeps fading.
- Invalidated if: SMH closes above $475.
- Managing it: Take profits at about 50–60% of max profit, especially near $445, where the wall can stall the drop. Exit by November 12 regardless to avoid expiration-day pin risk. Close on a close above $475 rather than hoping.
- Liquidity note: The $465 puts traded $3.40 wide (about 20% of mid) and the $445 puts $1.35 wide (about 15%). These are wide markets, so work limit orders near the mid and expect some slippage.
- Analyze this position →
If you expect the range to hold: Iron condor (outside the expected-move core)
- Trade: This is two credit spreads at once:
- Sell the November 13 $440 put and buy the $435 put.
- Sell the November 13 $490 call and buy the $495 call.
- Credit: $2.55 ($255) · Max profit: $2.55 ($255) · Max loss: $2.45 ($245) · Break-evens: $437.45 / $492.55
- Why it fits: The short put sits below the $445 put wall, and the short call sits above $485 max pain. That brackets the pinning lane where both technical targets land.
- Health warning: You're selling premium that hasn't been rich lately. Options are priced 9 points below delivered movement, and negative dealer gamma can push price through either side quickly.
- Makes sense only if: Friday's volatility cooling continues and SMH settles between $445 and $485.
- Invalidated if: SMH closes below $445 or above $485.
- Managing it: Close at about 50% of max credit. Close the threatened side if either short strike is touched. Exit by November 12.
- Liquidity note: The legs are quoted as follows:
- $440 put: $1.00 wide
- $435 put: $1.35 wide
- $490 call: $1.45 wide
- $495 call: $1.70 wide
- Analyze this position →
If you lean bullish: Bull call debit spread
- Trade: Buy the November 13 $465 call, sell the November 13 $485 call.
- Debit: $8.83 ($882.50) · Max profit: $11.18 ($1,117.50) · Max loss: $8.83 ($882.50) · Break-even: $473.83
- Why it fits: Max pain at $485 sits above spot, Friday's call build was unusually heavy, and calls are cheap relative to puts given the extreme skew. The short strike targets max pain.
- Makes sense only if: SMH reclaims Friday's $473.41 open on improving volume.
- Invalidated if: SMH closes below $445.
- Managing it: This trade fights an aligned downtrend, so keep it short-lived. Take profits quickly near $480–$485 and exit by November 12.
- Liquidity note: The $465 calls traded $2.70 wide and the $485 calls $2.65 wide. Use limit orders.
- Analyze this position →
If none of these: no trade
Standing aside is a real option this week, for three reasons:
- Wide spreads: Every November 13 strike in these structures trades with bid-ask spreads of roughly 12–20% of the option's value, so entry and exit costs are steep.
- Amplified moves: The estimated negative-gamma regime means moves can overshoot in either direction.
- Thin premium: Premium is too thin relative to realized movement to make selling attractive.
If you can't watch a position daily, or the $752–$882 debit is more than you'd risk on a six-day view, waiting for a decisive break of $445 or $485 is a perfectly defensible plan.
6 · Quick FAQ
What is SMH's expected move this week? About ±$40.87 (±8.81%) into the November 13 expiration, a $423.09–$504.83 range, based on straddle pricing as of November 6, 2026.
Is SMH expected to go up or down over the next week? Options positioning as of November 6 leans slightly bearish, driven by steep put skew and a large put build at $445. That is a read of what traders have done, not a forecast. The actionable map is the $423.09–$504.83 range and the $445 support and $485 invalidation levels.
Are SMH options expensive right now? By the calendar, yes. IV rank of 80/100 means option prices are higher than 80% of the past year's range. Against reality, no: options are priced about 9 vol points below the movement SMH has actually delivered, thinner than 91% of its own recent readings. That favors buying defined-risk spreads over selling premium.
Where is SMH's biggest options support and resistance? For the November 13 expiration, the put wall is $445 and the call wall is $460, with the call wall now just below spot. Max pain sits at $485.
What invalidates this week's read? A close above $485.
Methodology & disclosures. Data: end-of-day options-chain snapshot for SMH, 2026-11-06, generated 2026-11-07T13:27:48.896Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.