TSLA Options Are Pricing an $18.54 Move Into September 25 — The Chart Model Sees $359.50
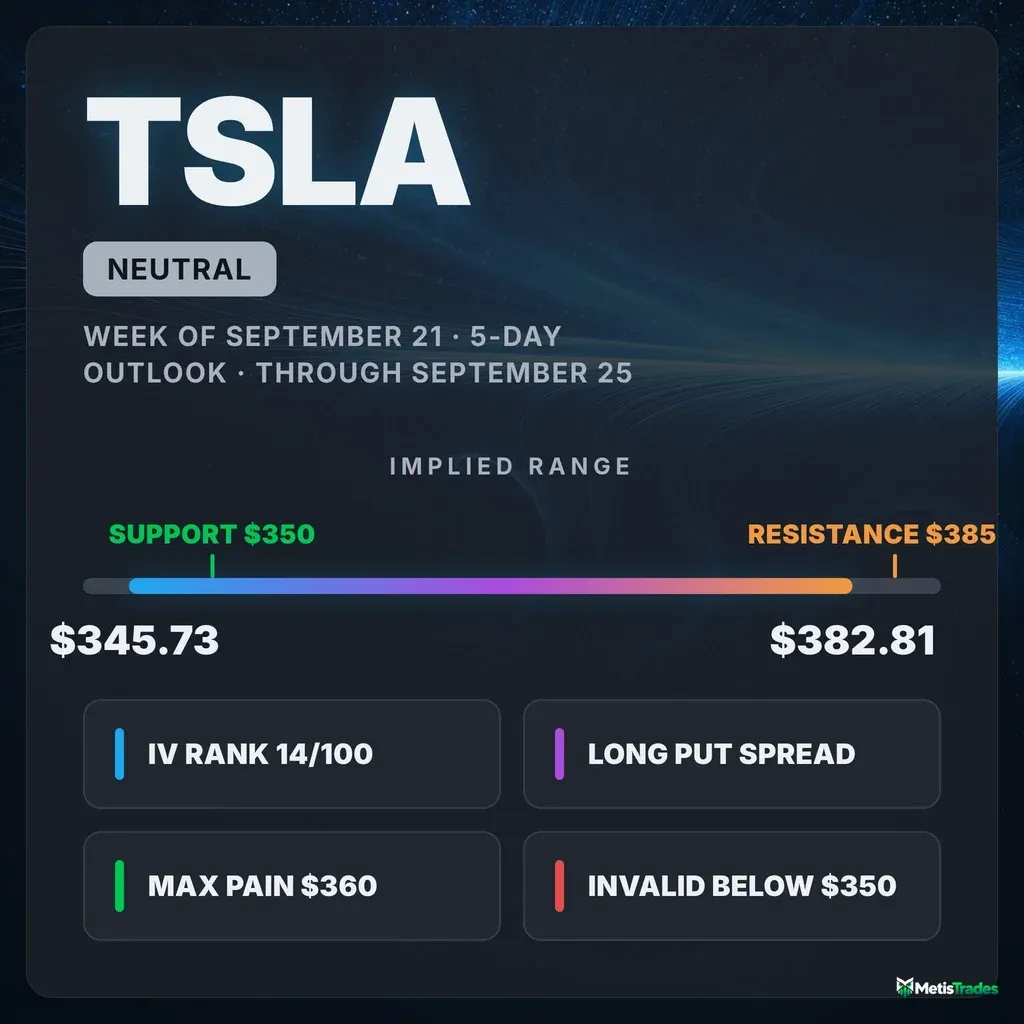
The options market implies a $345.73–$382.81 range for Tesla into the September 25 expiration, with positioning genuinely balanced between a $350 put wall and a $385 call wall. Here's what's driving it, where the chart model disagrees, and three defined-risk ways to trade it.
Listen to this analysis — prefer audio? This TSLA outlook is also available as a podcast episode:
The options market implies a $345.73–$382.81 range into the September 25 expiration; here's what's driving it, where the chart model pushes back, and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18, 2026 close
Explore the live TSLA options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into Sep 25) | $345.73 – $382.81 (±5.09%, or ±$18.54) |
| Major support | $350.00 (put wall, Sep 25 expiration) |
| Major resistance | $385.00 (call wall, Sep 25 expiration) |
| Max pain (Sep 25) | $360.00 |
| Dealer gamma regime (estimate) | Positive for the Sep 25 expiration — hedging tends to dampen moves; whole-chain flip estimate ≈ $380 |
| Volatility condition | Quiet — IV rank 13.7/100, ATM IV 40.9% · premium thin: options priced ~8 vol points below delivered movement |
| Technical check | Mixed (bearish chart model at both the 3-day and 5-day checkpoints, targets inside the implied range) |
| Best-fitting strategy | Long (debit) put spread if you want directional exposure — premium is cheap enough to buy rather than sell |
| Analysis invalidated if | TSLA closes below $350.00 |
1 · What matters today
Tesla closed Friday, September 18 at $364.27, and the options market is pricing a move of roughly $18.54 in either direction — a $345.73 to $382.81 band — through the September 25 expiration. That number comes from what straddles cost, the market's own estimate of how far the stock travels over the next five sessions.
Our read of the options flow is genuinely balanced. Call-side volume is running heavier than this stock's own norm, but short-dated sentiment has cooled, price momentum is flat over five sessions, and the scorecard we build from those inputs lands almost exactly at zero. The map that matters is structural: a pile of open put contracts at $350 underneath, a pile of calls at $385 overhead, and the price where the most option value expires worthless sitting at $360. The chart model disagrees mildly, leaning lower into Wednesday and Friday. A close below $350 is what breaks this read.
2 · What the options market is pricing
What changed this week
Price barely moved: TSLA is down 0.32% over the trailing five sessions and still up 5.55% over the trailing 20. Implied volatility — the market's estimate of how much TSLA will move, baked into option prices — rose 4.7% over five days but slipped 1.3% on Friday alone and is down 3.3% over 30 days. IV rank barely budged: 13.7/100 on Friday against a 7-day average of 13.3 and a 14-day average of 14.7. Nothing about the volatility complex is stressed.
Where money moved is more interesting. Put volume relative to call volume — above 1 means puts dominate — came in at 0.64, against a 7-day average of 0.72 and a 14-day average of 0.71. That is a call-tilted session, and an unusually call-tilted one for this name versus its own recent history. Open interest tells the same story more softly: 0.85 puts per call versus a 0.91 average over the past week. Total option volume ran 1.43× its 20-day average on 51.8 million shares traded, 1.28× the 20-day share-volume norm — busy, not frantic.
The biggest forward-looking build was defensive and far out: the October 16 $320 puts added 4,540 contracts of open interest to 12,723, with the October 16 $370 puts adding 4,118. Into Friday's expiration, the settled September 18 $360 puts added 12,526 contracts on 277,496 contracts of volume — history now, but it tells you where the week's fight was.
The bigger picture is a study in disagreement. Over the past week the stock is flat; over the past month it is up 5.5%; over the past ten weeks it is down 10.4%. The near-term read, the intermediate bounce, and the longer trend all point different ways, and the most recent momentum crossover — on September 10 — turned from bullish to bearish. That argues for shorter-dated directional structures and earlier profit-taking, not for leaning on a trend that does not exist.
Expected move
Into the September 25 expiration, the chain prices ±5.09%, or ±$18.54 around the $364.27 close: a $345.73 to $382.81 band. Here is how that scales across the nearby rungs:
| Expiration | Implied move | Range around $364.27 |
|---|---|---|
| September 21 (3 DTE) | ±2.42% | $355.45 – $373.09 |
| September 23 (5 DTE) | ±4.01% | $349.66 – $378.88 |
| September 25 (7 DTE) | ±5.09% | $345.73 – $382.81 |
| October 2 (14 DTE) | ±7.88% | $335.56 – $392.98 |
The ladder scales smoothly with time — no step-up, no kink, no single date the chain is bracing for. That is what a calendar with nothing scheduled inside the window looks like in option prices.
Volatility
At-the-money implied volatility is 40.9%, with an IV rank of 13.7/100 — option prices are cheaper than roughly 86% of the past year's readings. Current IV sits about 1.4% above its 30-day moving average (40.4%) and well below its 90-day average (44.5%), so the medium-term drift in option pricing is still downward even after this week's small bump. The front-month read is unavailable today: Friday was an expiry day, and front-month at-the-money IV cannot be interpolated from a contract expiring that afternoon.
One "vs its own norm" reading stands out. The ratio of five-day realized movement to 20-day realized movement — how much the stock has actually been moving lately versus over the past month — is unusually depressed for TSLA, sitting at less than half the monthly pace. The last week has been quiet by this stock's standards even as the chain kept pricing normal-sized moves.
Premium rich or cheap. The volatility risk premium — the gap between how much movement options are priced for and how much TSLA has actually delivered — is negative about 8 vol points: 40.9% implied against 49.0% realized over the past 20 sessions. When that gap is positive, option sellers have been collecting more than realized movement cost them; here it has been the reverse. Today's reading sits at the 51st percentile versus this stock's own recent history — right in the middle, meaning a negative gap is not an anomaly for TSLA lately but the normal state of the past three weeks. The path matters too: the gap flipped negative on September 1, widened to about −11 points by September 10 and 11, and has been narrowing steadily since, to −8 on Friday. Combine IV rank 13.7 with a premium that has run below delivered movement, and the honest verdict is that this is a week to own optionality rather than sell it — with one caveat: that 20-day realized number still carries early September's violent swings, while the past five sessions have been unusually calm, so the "cheap" label is softer than it looks.
Skew and sentiment
Puts and calls the same distance from the stock price don't cost the same — when puts are pricier, traders are paying up for crash protection. Here the opposite is mildly true: 25-delta puts price at 41.1% implied volatility against 41.9% for 25-delta calls, a skew of −0.84 vol points versus a 60-day median of −0.82. In plain terms, upside calls carry a slightly richer bid than downside puts, and that has been the norm for this name for two months. No one is paying up for protection.
Short-dated sentiment is the one soft spot. The 0–7 day bucket scores −17 (a week ago the 7-day average was −7), driven by risk reversals that have tilted toward puts and by put open interest edging ahead of call open interest in that tenor. Further out, the 7–30 day bucket reads +5 and the 30–60 day bucket +29, with delta-weighted volume clearly call-side. The overall regime label is Mixed — the buckets disagree, and no single one dominates. Peer-relative flow was a coin flip: 13 call contracts versus 12 put contracts cleared the unusual-volume bar.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 200-day moving average | $397.33 | 8.3% overhead; the long-term trend is still down |
| Swing resistance | $393.63 | Heuristic pivot cluster from recent price structure |
| Call wall (Sep 25) | $385.00 | Heaviest call open interest for this expiration (6,934) — the level that caps upside |
| Top of implied range (Sep 25) | $382.81 | Upper rail of the ±5.09% expected move |
| Swing resistance | $382.10 | Prior pivot high cluster |
| Whole-chain heaviest call strike | $380.00 | 56,214 calls across all expirations — not the Sep 25 wall; also the chain-wide gamma-flip estimate |
| 100-day moving average | $379.40 | 4.0% overhead |
| Chart-model upper rail | $371.50 | Top of the 5-day technical model's projected range |
| Swing resistance | $367.55 | Nearest overhead pivot |
| Friday's close | $364.27 | Reference for every figure above and below |
| Max pain (Sep 25) | $360.00 | Where the most option value expires worthless; also the largest single gamma strike chain-wide |
| 20-day moving average | $359.60 | Price is 1.3% above it |
| Swing support | $354.05 | Nearest structural floor from pivot clustering |
| 50-day moving average | $350.25 | Price is 4.0% above it — sits right on the put wall |
| Put wall (Sep 25) | $350.00 | Heaviest put open interest for this expiration (4,230) and chain-wide (47,716) — the level that supports downside |
| Bottom of implied range (Sep 25) | $345.73 | Lower rail of the ±5.09% expected move |
| Swing support | $342.53 | Next shelf below the wall |
Note the disagreement worth flagging: the September 25 expiration's own call wall is $385, while the whole chain's heaviest call strike is $380. Both matter, but only the $385 level is built from contracts that settle this Friday.
Positioning and unusual flow
One rough estimate of dealer positioning reads the September 25 expiration as a positive gamma regime — market makers hedge the options they've sold, and in this regime their hedging tends to dampen moves rather than amplify them, which fits the max-pain-at-$360 pin story. The same estimate places the whole-chain flip level near $380, above spot, which is internally awkward; these figures are derived from raw gamma and open interest under an assumed sign convention, not from observed dealer inventory. Treat them as directional color, not fact. What is worth knowing: one snapshot reading shows spot sitting further below that flip estimate than is typical for this stock.
Three non-expired flow items stood out on Friday, and all three cluster tightly around the money:
- Sep 25 $367.50 calls — 27,139 contracts traded against 1,417 held open, roughly 19× turnover, and $16.4 million of premium. That is the single heaviest dollar print in any live expiration and it is a bet on the stock reclaiming the $367.55 swing pivot this week.
- Sep 21 $362.50 puts — 27,547 contracts against just 497 open, a 55× turnover ratio. Almost all of it was same-day positioning, not a durable hedge.
- Oct 16 $320 puts — 4,540 contracts of new open interest, to 12,723. Deep, cheap, far-dated downside insurance; not a September story, but a signal that someone is buying tail protection while it is cheap.
3 · Technical check
Both chart-model reads lean bearish, and both land inside the options-implied range — which makes this a Mixed check rather than a clean divergence. The near-term model (target September 23) calls for $361.00 with a projected range of $356.50 to $370.00. The five-day model (target September 25, the same date our options thesis is anchored to) calls for $359.50 with a projected range of $352.50 to $371.50.
The two most decisive inputs behind that lean: a MACD bearish crossover that fired on September 18 and has stayed below its signal line, and a Chaikin Money Flow reading of −0.119 that has drifted steadily more negative over six sessions while price held roughly flat — quiet distribution beneath a sideways tape. Working against it, ADX at 14.2 and falling confirms there is almost no trend strength to lean on; the model's own dominant scenario carries only a 45% weight and invalidates on a reclaim and close back above $364.50.
Model vs. Market: The options market implies $345.73–$382.81 into September 25; the 5-day technical model targets $359.50. The chart's bearish call sits comfortably inside what the chain is pricing — the disagreement is about direction, not magnitude, and it resolves the moment TSLA closes on either side of the $360 max-pain strike.
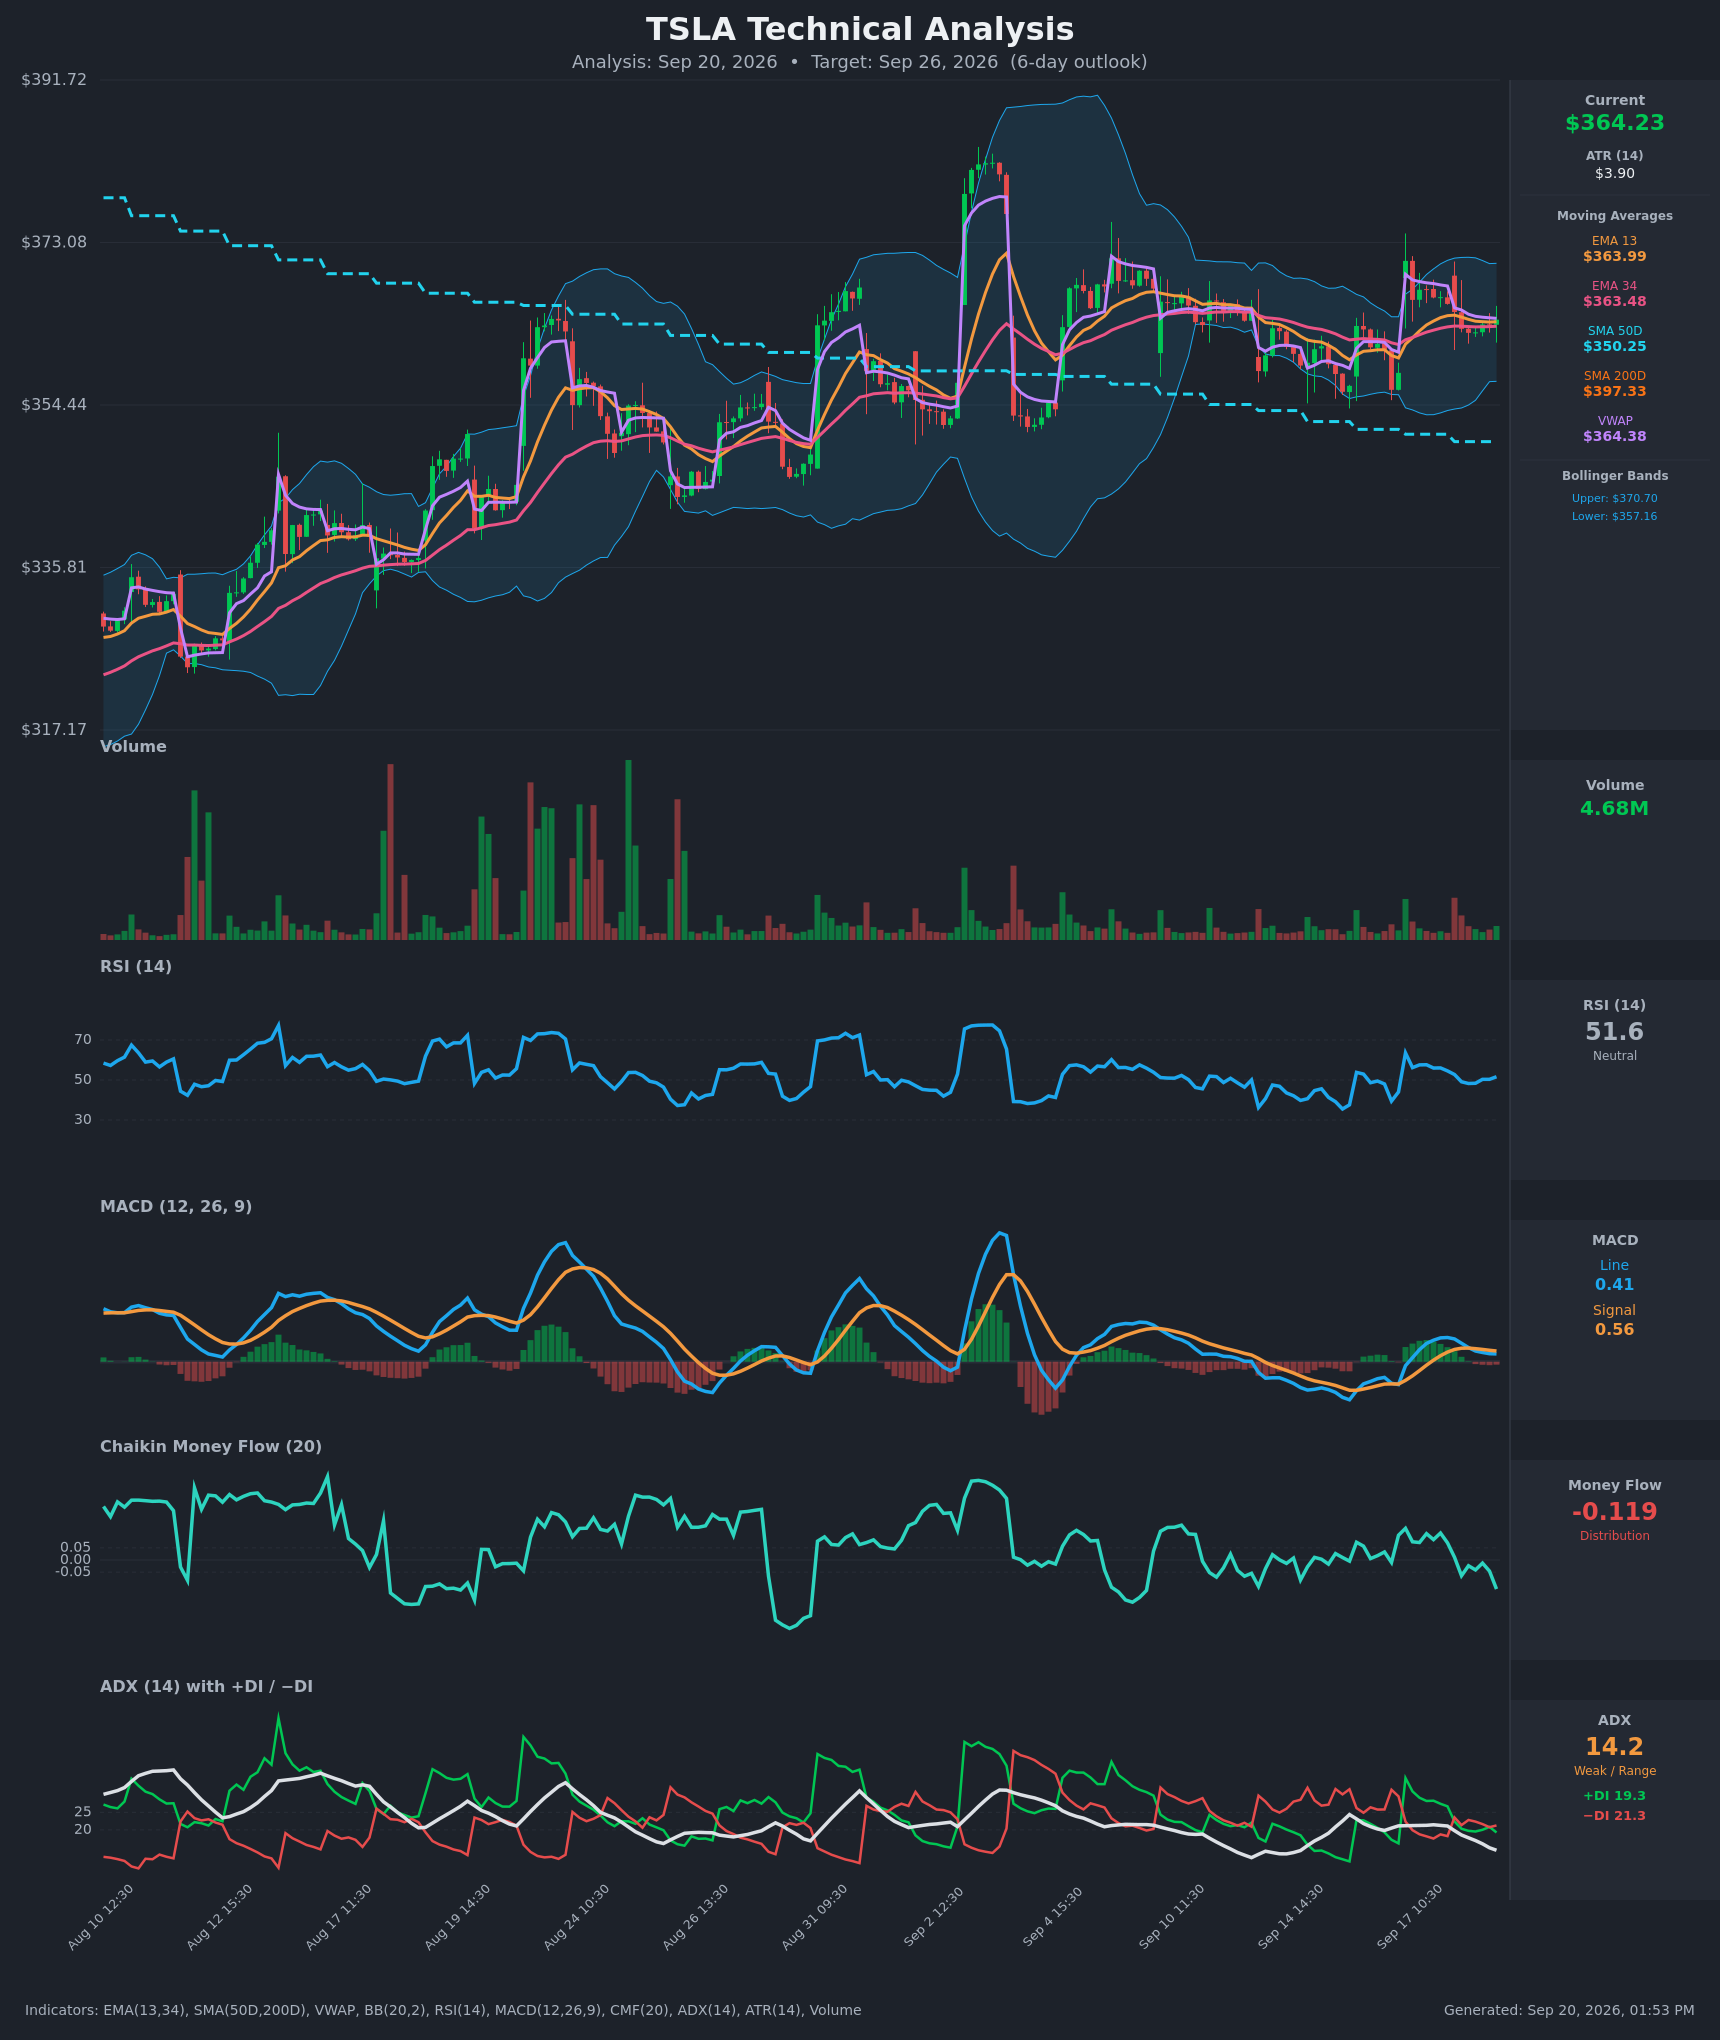
How it shaped the strikes below: the technical lean did not flip the neutral bias — it cannot, on its own — but it did shade the featured directional structure to the downside and pull the iron condor's short call strike up to the $385 wall rather than nearer the money.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If TSLA pushes above the call wall ($385.00): That is the strike with the heaviest call open interest for this expiration, and heavy call open interest overhead tends to slow rallies as hedging flows lean against them. It also sits above the top of the implied range ($382.81), so getting there requires a bigger-than-priced move. A clean break leaves thinner positioning until the $393.63 swing pivot and the 100-day average at $379.40 flips from resistance to reference.
If TSLA drifts between the walls: This is the base case the positioning supports. Max pain for September 25 sits at $360.00, $4.27 below Friday's close and right on top of the 20-day moving average at $359.60 and the largest single gamma strike in the chain. With the dealer-gamma estimate reading positive for this expiration, hedging flows in this zone tend to pull price toward the heavy strikes rather than push it away, and the $354.05–$367.55 pivot band brackets it neatly.
If TSLA breaks below the put wall ($350.00): That level is doing triple duty — the expiration's heaviest put open interest, the chain-wide put wall at 47,716 contracts, and the 50-day moving average at $350.25. Losing it takes out the dampening structure at once, and one snapshot reading already places spot unusually far below the chain-wide gamma-flip estimate for this name, the side on which hedging is estimated to amplify selling rather than cushion it. The implied lower rail at $345.73 and the $342.53 swing shelf are the next markers.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of September 18, 2026. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bearish: Sep 25 $365/$355 long put spread
- Trade: Buy the September 25 $365 put, sell the September 25 $355 put
- Debit: $4.13 ($413) · Max profit: $587 · Max loss: $413 · Break-even: $360.88
- Why it fits: This is the structure the volatility picture actually argues for. Options are priced about 8 vol points below what TSLA has delivered over the past 20 sessions, and IV rank is 13.7/100 — when you are buying the cheaper side of that gap, a debit structure is the honest expression. It also aligns with both chart-model targets ($361.00 and $359.50) and pays fully below $355, just above the put wall. The break-even at $360.88 sits a whisker above the $360 max-pain strike, so the pin case is roughly a scratch rather than a loss.
- Makes sense only if: You think the quiet five-session stretch resolves lower rather than continuing, and you accept that a $364.27 close on Friday leaves you near break-even at best.
- Invalidated if: TSLA closes above $370.00 — the top of the near-term chart model's own projected range.
- Managing it: Take profit at roughly 60–70% of the spread's width if $355 trades; because the short-term direction is fighting a bounce that is still up 5.5% over 20 sessions, take profits earlier than you would in a trending tape. Exit by Thursday, September 24 rather than carrying gamma risk into Friday's settlement.
- Liquidity note: The $365 puts quoted 15¢ wide ($7.55/$7.70) and the $355 puts 10¢ wide ($3.45/$3.55) — both fill easily.
- Analyze this position →
If you expect the range to hold: Sep 25 $345/$350/$385/$390 iron condor
- Trade: Sell the $350 put / buy the $345 put, and sell the $385 call / buy the $390 call, all expiring September 25
- Credit: $1.37 ($137) · Max profit: $137 · Max loss: $363 · Break-evens: $348.63 and $386.37
- Why it fits: The short strikes are the walls themselves — $350 is the expiration's put wall and chain-wide put wall, $385 is its call wall. Both break-evens sit outside the options-implied $345.73–$382.81 range, and max pain at $360 is comfortably inside. With the dealer-gamma estimate reading positive for this expiration, this is the structure that gets paid for the base case.
- Health warning: you're selling premium that hasn't been rich lately — the implied-versus-delivered gap has been negative for three straight weeks, so this trade collects less than TSLA's recent movement has historically cost sellers. Size accordingly.
- Makes sense only if: You genuinely expect a quiet week and are willing to risk $363 to make $137.
- Invalidated if: TSLA closes below $350.00 or above $385.00 — either short strike being breached ends the thesis.
- Managing it: Close at ~50% of max credit; exit regardless by Thursday, September 24. If either short strike trades through, close rather than hope — the risk/reward on a four-legged short-premium trade turns ugly fast in the final two sessions.
- Liquidity note: The $350 puts quoted 7¢ wide, the $345 puts 6¢, and both the $385 and $390 calls 3¢ wide. Execution is not the problem here; the thin credit is.
- Analyze this position →
If you lean bullish: Sep 25 $355/$350 put credit spread
- Trade: Sell the September 25 $355 put, buy the September 25 $350 put
- Credit: $1.25 ($125) · Max profit: $125 · Max loss: $375 · Break-even: $353.75
- Why it fits: A credit spread collects premium up front and keeps it if the stock stays above the short strike. Here the short strike is stacked on structure: $355 sits above the $354.05 swing support, above the 50-day average at $350.25, and above the $350 put wall that would have to give way first. Call-tilted volume — 0.64 puts per call against a 0.72 weekly average — and the flat-to-slightly-call-rich skew both say nobody is paying up for a collapse.
- Health warning: same caveat as the condor — you're selling premium that hasn't been rich lately, and the −8 vol-point gap means recent realized movement has exceeded what the chain charged for it.
- Makes sense only if: You think the $350–$355 shelf holds and you are content with a $125-for-$375 risk profile.
- Invalidated if: TSLA closes below $355.00.
- Managing it: Close at ~50% of max credit; exit regardless by Thursday, September 24. The chart model's bearish lean is a direct argument against this structure — if you take it, take profits early rather than holding for the last few cents.
- Liquidity note: The $355 puts quoted 10¢ wide ($3.45/$3.55), the $350 puts 7¢ wide ($2.22/$2.29).
- Analyze this position →
If none of these: no trade
There is a real case for standing aside. The directional read is a genuine zero — the positioning inputs point in opposite directions and cancel — and the one asymmetry we do have, a premium that has run below delivered movement, cuts against the two credit structures above. Selling a $137 condor in a name whose 20-day realized volatility is 49% is not obviously a good trade even when the walls are wide. Meanwhile the debit spread's edge rests partly on a 20-day realized number still inflated by early September's swings, while the last five sessions have been unusually calm for this stock. If your view is "TSLA chops between $355 and $370 on light volume," the honest answer is that there is no structure that pays you well for being right about that this week. Waiting for the next expiration — or for a close through $350 or $385 that actually resolves something — is a legitimate fourth option.
6 · Quick FAQ
What is TSLA's expected move this week? ±$18.54 (±5.09%) into the September 25 expiration, a $345.73–$382.81 band around Friday's $364.27 close, per the options market's straddle pricing as of September 18, 2026.
Is TSLA expected to go up or down over the next five days? Options positioning as of September 18 is neutral — call-tilted volume offsets soft short-dated sentiment and flat price momentum, and the composite lands at essentially zero — but that is a read of what traders have done, not a forecast. The actionable map is the $345.73–$382.81 range with $350.00 support, $385.00 resistance, and $360.00 max pain in between.
Are TSLA options expensive right now? IV rank 13.7/100 says option prices are lower than about 86% of the past year's readings. On top of that, they're running about 8 vol points below the movement TSLA has actually delivered over 20 sessions — a gap that sits at the 51st percentile of this stock's own recent readings, meaning it is the norm lately, not an outlier. The verdict: this is a week to own premium rather than sell it, tempered by the fact that the last five sessions have been unusually quiet.
Where is TSLA's biggest options support and resistance? Put wall $350.00, call wall $385.00 for the September 25 expiration. Note the whole chain's heaviest call strike is $380.00 — a different level, built from every expiration combined.
What invalidates this week's read? A close below $350.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for TSLA, 2026-09-18, generated 2026-09-20T13:53:25.740Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.