WMT Options Price a $4.45 Move Into November 6: Can the $120 Put Wall Hold?
Walmart options imply a $119.06–$127.96 range into the November 6 expiration. Premium is the richest it has been against realized movement in months, and our calibrated read leans slightly higher. Here is the levels map and three defined-risk ways to trade it.
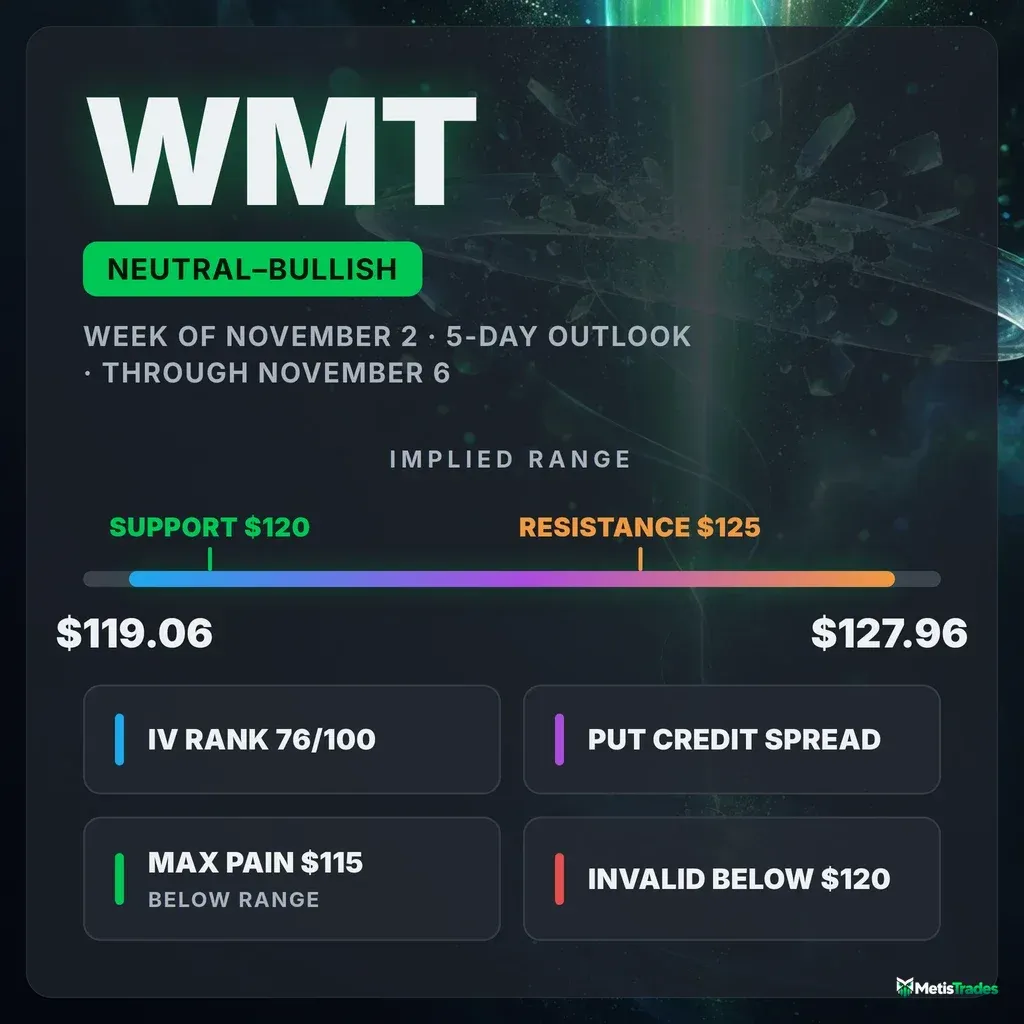
The options market implies a $119.06–$127.96 range into the November 6 expiration. Below: what is driving that range, the levels that matter, and three defined-risk ways to trade it.
Published Sunday, November 1, 2026 · Data as of Friday, October 30, 2026 close
Explore the live WMT options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bullish |
| Options-implied range (into Nov 6) | $119.06 – $127.96 (±3.60%, ±$4.45) |
| Major support | $120.00 (Nov 6 put wall) |
| Major resistance | $125.00 (whole-chain call wall). The Nov 6 call wall at $122.00 already sits below spot. |
| Max pain (Nov 6) | $115.00 |
| Dealer gamma regime (estimate) | Positive: hedging tends to dampen moves. Flip level ≈ $115 |
| Volatility condition | Rising. IV rank 76/100 · premium rich: options priced ~12.5 vol pts above delivered movement |
| Next earnings | December 3 (report time not specified), after the Nov 6 expiration |
| Technical check | Confirms (bullish, 3-day and 5-day chart models; target $124.40) |
| Best-fitting strategy | Nov 6 $121/$119 put credit spread, if $120 holds |
| Analysis invalidated if | WMT closes below $120.00 |
1 · What matters today
Walmart closed Friday, October 30 at $123.51 after a sharp two-day run. The options market is pricing a move of about $4.45 either way by Friday, November 6. That is a range of roughly $119.06 to $127.96.
Our read is slightly bullish. Traders have been buying protection, but that looks like hedging inside an uptrend that is still intact, not a bet on a drop. Most of the new open contracts were calls, and the stock trades above every major options level for this expiration.
The level that changes the picture is $120, the strike with the most open puts for November 6. A close below it would undo the breakout.
Options are expensive right now: priced for far more movement than Walmart has actually delivered. That favors collecting premium over buying it. Both chart-based technical models also lean higher, which confirms the options read.
2 · What the options market is pricing
What changed this week
Walmart gained 3.0% over the past five sessions and 18.5% over the past 20. Most of the latest push came from back-to-back opening gaps on October 29 and October 30.
Option prices rose along with the stock. At-the-money implied volatility climbed 3.0% over five days and is up 45.9% over 30 sessions.
The put/call open-interest ratio is 0.60, meaning about six puts held open for every ten calls. That is essentially unchanged from its 7-day average of 0.61, so traders did not add downside protection on balance this week.
Friday's new money leaned to calls. Open interest grew by about 13,124 call contracts versus just 415 puts. The single biggest build was in the November 6 $122 calls, which added 1,314 contracts to reach 3,362. The November 6 $121 calls added 994.
Into Friday's own (now settled) expiration, the October 30 $122 calls had also added 1,182 contracts. That is history now, not a live level.
The short- and long-term trend reads agree. The past month and the past two-plus months both read bullish, while the past week reads flat. So this is a pause-and-breakout tape, not a market fighting a bigger downtrend.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the November 6 expiration it is ±3.60%, or about ±$4.45 around $123.51, giving $119.06 to $127.96.
| Expiration | Implied move | Range around $123.51 |
|---|---|---|
| Nov 6 (this window) | ±3.60% | $119.06 – $127.96 |
| Nov 13 | ±5.10% | $117.21 – $129.81 |
| Nov 20 (monthly) | ±9.11% | $112.26 – $134.76 |
| Nov 27 | ±9.36% | $111.95 – $135.07 |
The two weekly rungs scale normally with time. The jump comes at the November 20 monthly expiration, where at-the-money IV leaps to about 38% from roughly 26% on the weeklies. Options past mid-November carry a much heavier premium than the next two Fridays.
Volatility
Implied volatility (IV) is the market's estimate of how much WMT will move, baked into option prices. At-the-money IV is 32.98%, well above its 30-day average of 25.6% and its 90-day average of 26.2%.
IV rank shows where today's IV sits versus the past year. At 76/100, options are cheaper than only about 24% of the past year's readings. IV percentile is even higher at 95.6: IV has been lower than today on roughly 96% of the past year's days.
Two more readings put this in context:
- IV is expanding unusually fast for this name compared with its own recent history. "Unusual" here means unusual for WMT, not versus the broader market.
- Actual 20-day realized movement (20.5% annualized) is running somewhat below its own norm.
The front-month term-structure read is unavailable today (expiry day). The roughly 60-day IV sits at 30.3%.
Premium rich or cheap. The volatility risk premium is the gap between how much movement options are priced for and how much WMT has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them. Today it is about 12.5 vol points.
Its percentile shows where today's gap sits versus this stock's own recent readings, and it is at the top of the scale: richer than every recent reading. Three weeks ago the gap was slightly negative, and it has widened almost every session since, from about 8.8 points on October 26 to 12.5 now. No earnings gap sits in the realized-volatility window, so this is not a mechanical artifact.
That combination (IV rank 76 and a top-of-range premium over delivered movement) favors collecting premium over the next five sessions, not buying it.
Earnings on the calendar
Walmart's next report is scheduled for December 3. That lands after the November 27 expiration and before December 4, the first expiration that captures it.
The chain shows little earnings footprint so far. December 4 prices ±9.39%, barely above November 27's ±9.36%. The big step-up in this ladder sits at November 20, well before the report.
For history: the most recent report matched the $0.66 estimate, while the one before it came in at $0.53 against an expected $0.70.
Skew and sentiment
Skew means puts and calls the same distance from the stock price don't cost the same; when puts are pricier, traders are paying up for crash protection. Puts at the 25-delta level are running about 0.9 vol points over calls (34.8% vs 33.9%), against a 60-day norm of about 0.1 points. So puts carry a modest premium.
That premium is fading fast. Skew blew out to 6.5 points on October 28 and has bled off since, which is why its 3-day average still reads about 4.2 points. Traders paid up for protection during the pre-breakout wobble and are now letting it go.
The put/call ratio measures how much put activity there is relative to calls; above 1 means puts dominate. Friday's volume ratio was 0.69, above its 7-day average of 0.59 and well above its 60-day median of 0.45. That put-buying pace is above normal for this name.
The detail matters, though. Much of that put volume hit strikes like $120–$124 that the stock had just rallied through, which reads as fresh hedges placed under a new high.
Sentiment in short-dated options is split:
- The 0–7 day expirations lean bullish (+20), driven by call open interest building.
- The 7–30 day bucket leans bearish (−22), driven by richer-than-usual puts.
The overall regime reads mixed. For the five-session window, the near-dated read is the one that matters most.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $135.16 | Upper bound of the year's range |
| Large gamma strike (whole chain) | $130.00 | Fourth-largest options concentration; 39,442 calls open across expirations |
| Implied range high (Nov 6) | $127.96 | Top of the one-standard-deviation move priced into this window |
| Call wall (whole chain) / largest gamma strike | $125.00 | 87,825 calls open, the biggest pile overhead; tends to slow rallies |
| Spot (Oct 30 close) | $123.51 | Just above Friday's opening gap |
| Call wall (Nov 6) | $122.00 | This expiration's heaviest call strike (3,362 contracts), now in the money |
| Swing support | $121.89 | Recent pivot cluster; near the top of the old $118–$121 range |
| Oct 30 gap base | $121.25 | Prior close before Friday's 1.56% gap up |
| Put wall (Nov 6) / second-largest gamma strike | $120.00 | This expiration's heaviest put strike (996 contracts, up 659 on the day) |
| Implied range low (Nov 6) | $119.06 | Bottom of the priced move |
| 200-day moving average | $118.51 | Long-term trend line; price is 4.2% above it |
| Swing support | $117.20 | Base of the recent consolidation |
| 20-day moving average | $115.95 | Short-term trend line, 6.5% below price |
| Max pain (Nov 6) / gamma flip estimate | $115.00 | Where the most Nov 6 option value expires worthless; also one rough estimate of the flip level |
| 50-day moving average | $110.23 | Intermediate trend, 12% below price |
| Put wall (whole chain) | $100.00 | 42,704 puts open, mostly longer-dated protection |
Note the disagreement between the two sets of walls:
- November 6: call wall $122.00, put wall $120.00. Both sit below spot.
- Whole chain: call wall $125.00, put wall $100.00.
For the next five sessions, $120 is the near support and the $125 strike is the overhead barrier.
Max pain is the price where the most option value would expire worthless; expirations sometimes gravitate toward it. Here it is $115.00, far below spot. That reflects how much in-the-money call value has piled up during the rally. It is not a target.
Positioning and unusual flow
Dealer gamma: market makers hedge the options they've sold. One rough estimate puts both the whole chain and the November 6 expiration in a positive gamma regime, where that hedging tends to dampen moves. The gamma flip level is the price below which market-maker hedging tends to accelerate selling rather than cushion it. That estimate sits near $115, about 7% below spot, which is a bit closer than usual for this name but still a long way off.
Three flows stand out:
- Nov 6 $120 puts: 2,973 contracts traded and open interest jumped from 337 to 996. Traders anchored this week's protection right at the put wall, about $56,000 in premium at the $0.56 mid. That is what makes $120 the level to watch.
- Nov 6 $123 puts: 2,061 contracts traded against only 6 open, about $309,000 in premium. That volume is more than 300 times the existing open interest, which is classic short-term hedging right at the money after a gap.
- Nov 13 $123 puts: 2,667 contracts against 24 open, about $580,000 in premium. Same story, one week further out.
Against that, the November 20 $125 calls hold 58,254 open contracts and added 585 more. That is a large, patient bullish position at the strike that doubles as the whole-chain call wall.
3 · Technical check
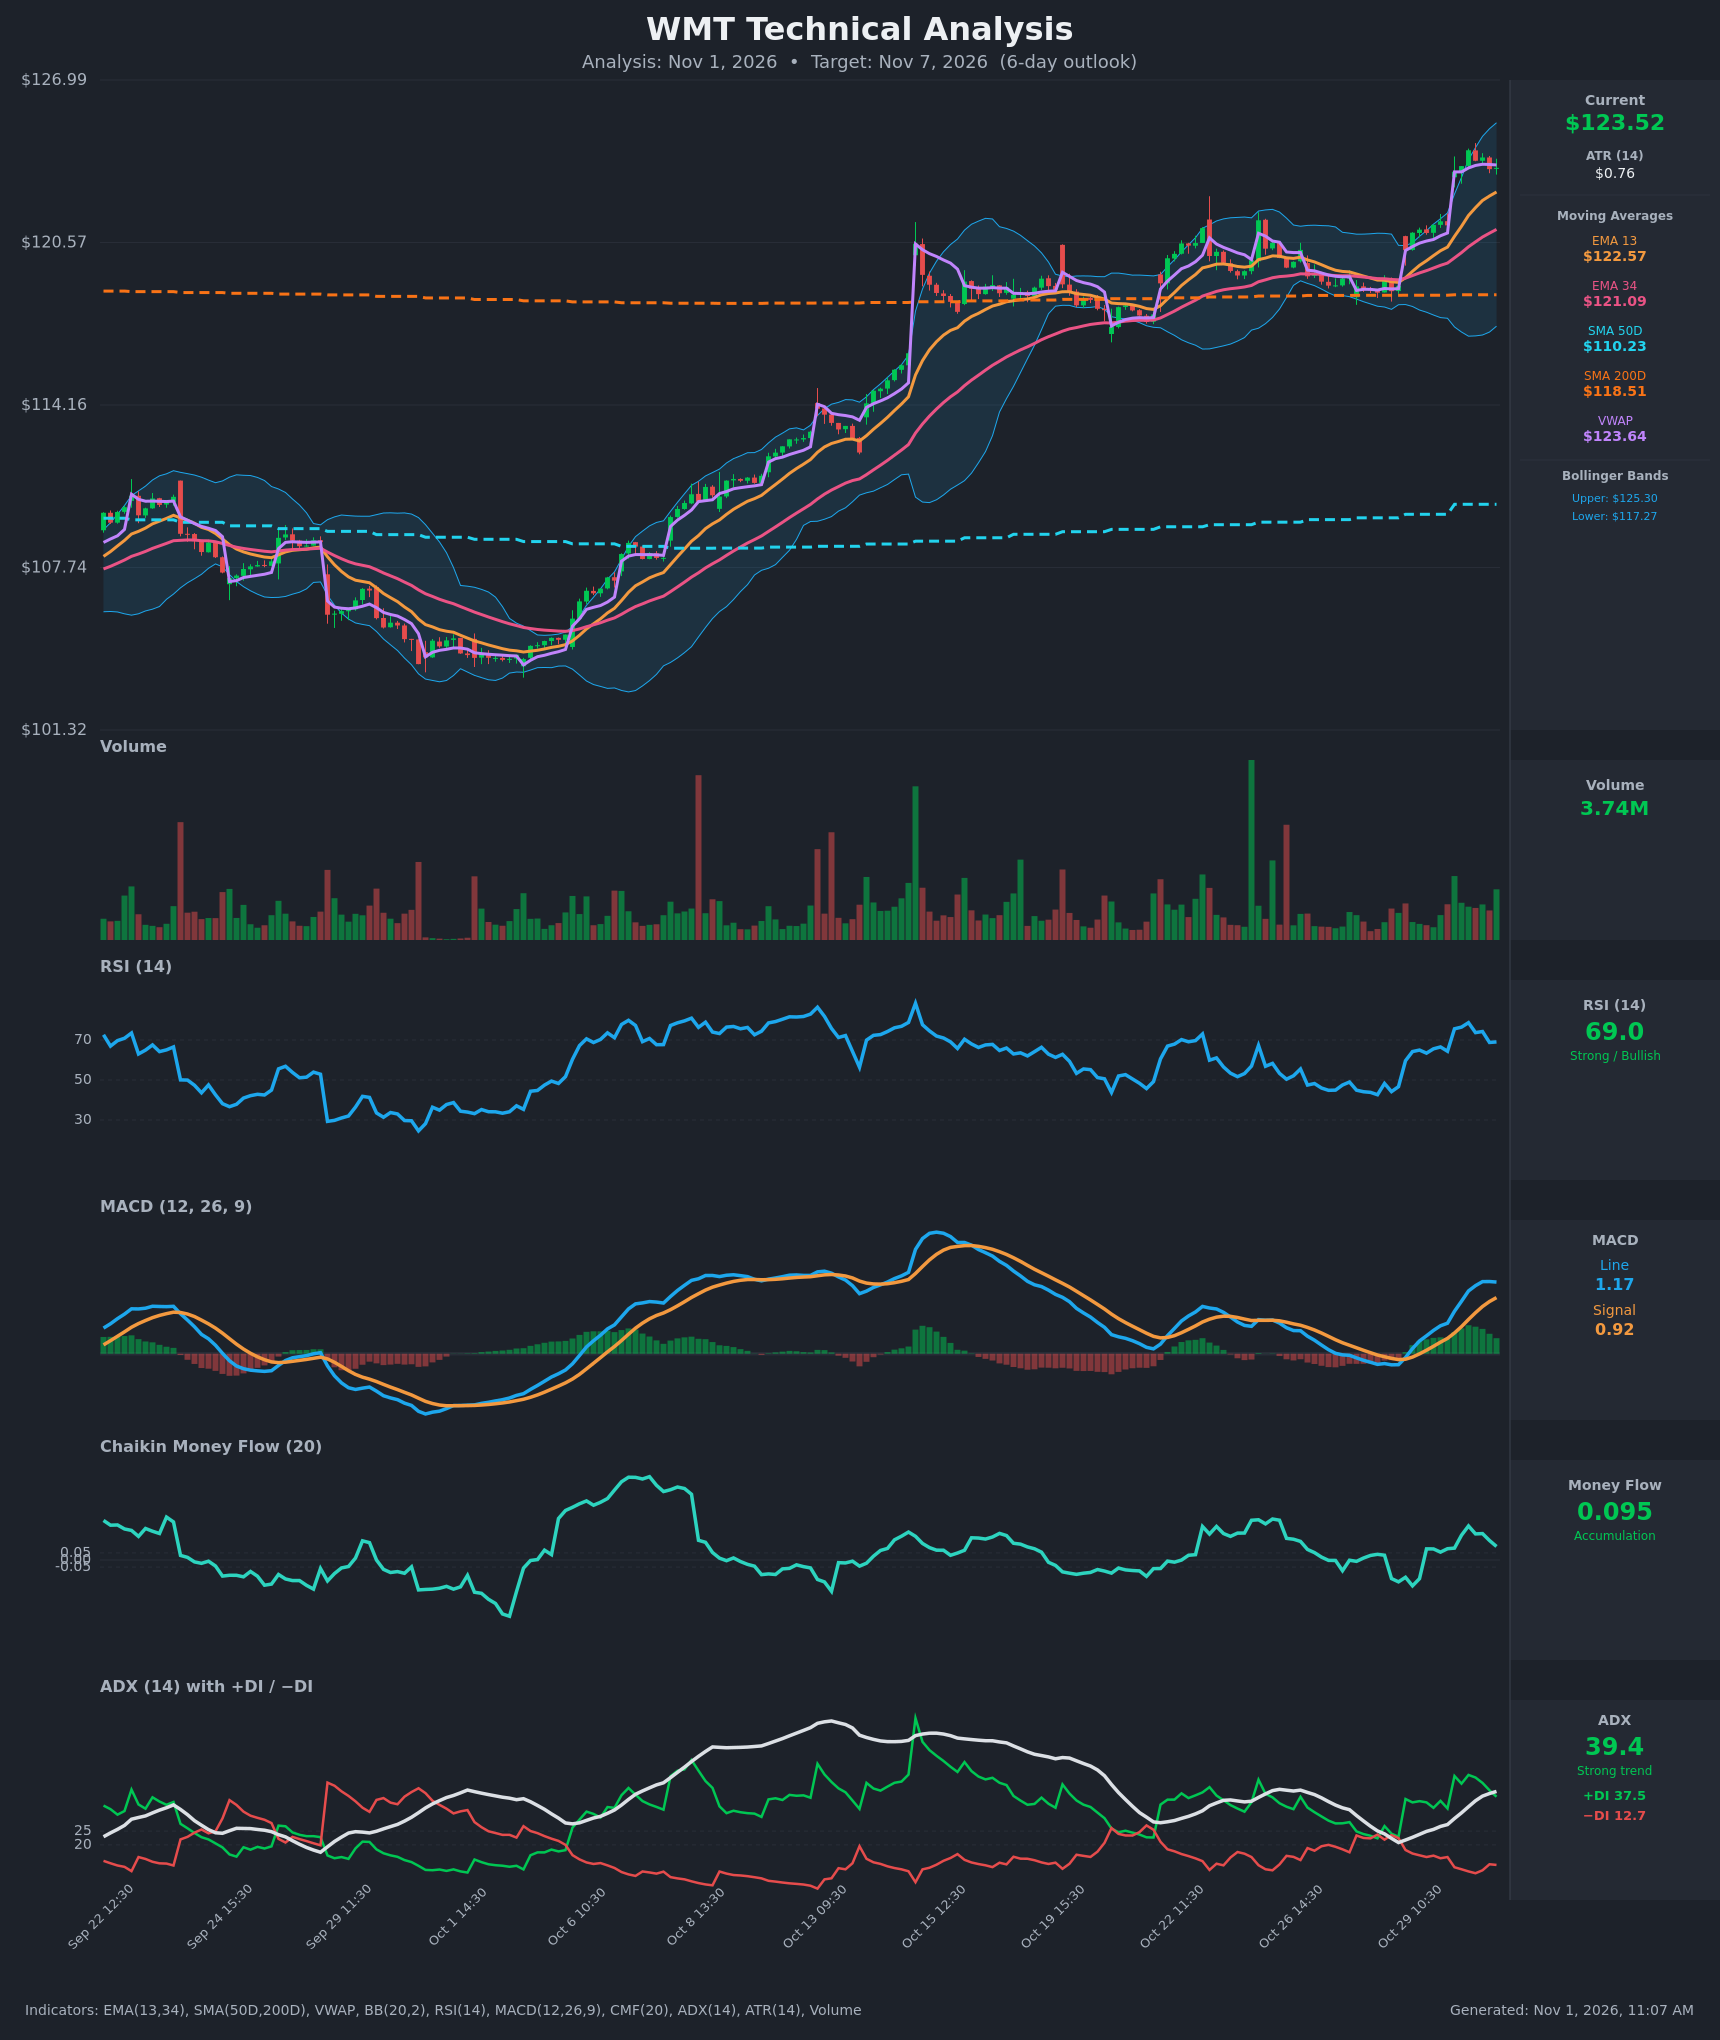
3-day model: bullish, with a $124.40 target for November 4 and a projected range of $121.40–$126.40. The target sits inside the options-implied range, so it confirms our slightly bullish read.
The model cites a strong trend reading (ADX near 39 with buyers clearly dominant) and price riding above its short-term averages. It also flags a cooling RSI near 69 and a flattening MACD, which suggest a grind rather than a surge. Its main invalidation is a close below $122.50.
5-day model: also bullish, with the same $124.40 target for November 6 and a projected range of $120.90–$126.90. It frames Friday's move as a breakout from a multi-week $117–$121.50 base and invalidates its dominant scenario on a close below $122.00. Again, this confirms: same direction, and a target well inside what options are pricing.
Both models put support near $122.57 (the 13-period average) and resistance at $125.30 (upper Bollinger Band). That lines up closely with the $125.00 call-wall barrier. The TA did not change the strike selection below; it reinforced keeping short calls above the $125–$127 zone.
Model vs. Market: The options market implies $119.06–$127.96 into November 6; the 5-day technical model targets $124.40. The chart model expects a modest drift higher well inside the priced range, which is one more reason expensive premium looks better to sell than to buy.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five sessions can go
If WMT pushes above the $125.00 call wall: The heaviest call open interest in the chain tends to slow rallies as hedging flows lean against it. A clean break leaves thinner positioning until the $130 gamma strike, with the implied range topping out near $127.96.
If WMT drifts between $120 and $125: This is the positive-gamma base case. Dealer hedging tends to absorb moves, and with the November 6 walls at $122 and $120 below spot, the zone just under the price acts as a floor.
Max pain at $115 is too far away to exert real pull over five sessions. The more likely pin zone is the $122–$125 band where call open interest is concentrated.
If WMT breaks below the $120.00 put wall: The breakout fails, and the stock is back inside the old range with the 200-day average ($118.51) as the next reference. Hedging should still cushion rather than accelerate a slide until spot nears the ~$115 flip estimate. Below that, one rough estimate suggests market-maker hedging amplifies selling rather than cushioning it.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 30, 2026. All structures are hypothetical. Verify live prices before trading; these will be stale by the open.
Because premium is the richest it has been versus delivered movement, the premium-selling structures lead. Each credit structure collects money up front and wins if WMT stays away from the short strike. Each debit structure pays up front for a directional bet with capped risk.
If you lean bullish: Nov 6 $121/$119 put credit spread
- Trade: Sell the Nov 6 $121 put ($0.785), buy the Nov 6 $119 put ($0.38). You collect a credit and keep it if WMT stays above $121.
- Credit: $0.405 ($40.50 per spread)
- Max profit: $40.50
- Max loss: $159.50
- Break-even: ~$120.60
- Why it fits: The short strike sits just above the $120 put wall, where traders added 659 contracts Friday, and below $121.89 swing support. You are selling into an IV rank of 76 and a premium over realized movement at the top of its recent range.
- Makes sense only if: The Friday gap holds and WMT stays in the $122–$125 zone.
- Invalidated if: WMT closes below $120.00.
- Earnings exposure: Expires 27 days before the December 3 report, so there is no earnings-gap risk.
- Managing it: Close at about 50% of max credit. Exit by Thursday, November 5 rather than carrying short-strike risk into expiration day. If WMT closes below $121, close rather than hope. With a short-week fight between flat near-term flow and a bullish bigger trend, take profits early.
- Liquidity note: The $121 puts quoted $0.75/$0.82 (7¢ wide) and the $119 puts $0.34/$0.42 (8¢ wide). Small in dollars but large in percent on contracts this cheap, so work a limit near the mid.
- Analyze this position →
If you expect the range to hold: Nov 6 $117/$119/$128/$130 iron condor
- Trade: Two credit spreads in one position, which wins if WMT stays between the short strikes:
- Sell the Nov 6 $119 put ($0.38), buy the $117 put ($0.17).
- Sell the Nov 6 $128 call ($0.405), buy the $130 call ($0.185).
- Credit: $0.43 ($43 per condor)
- Max profit: $43
- Max loss: $157
- Break-evens: $118.57 and $128.43
- Why it fits: Both short strikes sit just outside the $119.06–$127.96 implied range, in a positive-gamma regime that tends to dampen moves. The short call is above both the $125 call wall and the chart models' $126.40–$126.90 range highs.
- Makes sense only if: Premium stays rich and no shock pushes WMT through either rail.
- Invalidated if: WMT closes below $119.00 or above $128.00.
- Earnings exposure: Expires 27 days before the December 3 report, so there is no earnings-gap risk.
- Managing it: Take 50% of the credit if available. Close the tested side if spot reaches within $1 of a short strike. Exit by November 5 regardless.
- Liquidity note: The $128 calls traded 7¢ wide ($0.37/$0.44) and the $130 calls 3¢ wide ($0.17/$0.20). The $117 puts were 4¢ wide ($0.15/$0.19). Four legs mean four spreads to cross, so enter as a single order at a limit.
- Analyze this position →
If you lean bearish: Nov 6 $123/$120 put debit spread
- Trade: Buy the Nov 6 $123 put ($1.50), sell the Nov 6 $120 put ($0.56). You pay a debit and profit if WMT falls toward $120.
- Debit: $0.94 ($94 per spread)
- Max profit: $206
- Max loss: $94
- Break-even: $122.06
- Why it fits: It targets a failed breakout back to the $120 put wall. Selling the $120 put offsets much of the expensive premium you would otherwise pay for an outright put.
- Makes sense only if: WMT loses the Friday gap and closes below the $122 area.
- Invalidated if: WMT closes above $125.00.
- Earnings exposure: Expires 27 days before the December 3 report, so there is no earnings-gap risk.
- Managing it: Take profits near $120 rather than waiting for max value. Cut the trade if WMT reclaims $124.25.
- Liquidity note: The $123 puts quoted $1.45/$1.55 (10¢ wide) and the $120 puts $0.52/$0.60 (8¢ wide). Workable at a limit near the mid.
- Analyze this position →
If none of these: no trade
Rich premium is not free money, and there are honest reasons to stand aside.
First, the payoffs are lopsided. Both credit structures risk roughly $157–$160 to make $40–$43, so a single bad close wipes out several winners. The stock just rallied 18.5% in a month, and one gap like Thursday's or Friday's could cover most of the implied move by itself.
Second, part of the richness may be the market pricing that new volatility regime rather than overpaying for calm. Realized movement could catch up to implied, and premium sellers would then have been paid fairly, not richly.
If you already hold WMT or cannot watch a five-day position, sitting out is a legitimate choice.
6 · Quick FAQ
What is WMT's expected move this week? About ±$4.45 (±3.60%) into the November 6 expiration, a $119.06–$127.96 range, per straddle pricing as of October 30.
Is WMT expected to go up or down over the next week? Options positioning as of October 30 leans slightly bullish: new open interest was heavily call-side and spot sits above both November 6 walls. That is a read of what traders have done, not a forecast. The actionable map is the $119.06–$127.96 range, $120 support and $125 resistance.
Are WMT options expensive right now? Yes. IV rank is 76/100, so option prices are higher than about 76% of the past year's readings. They are also running about 12.5 vol points above the movement WMT has actually delivered, richer than every reading in this stock's recent history. That favors selling premium over buying it.
When is WMT's next earnings report? December 3, after the November 27 expiration and before December 4. So far the chain shows little extra premium specifically for the report.
Where is WMT's biggest options support and resistance? For November 6, the put wall is $120.00 and the call wall is $122.00, which is now below spot. Across the whole chain, the call wall at $125.00 is the main overhead barrier.
What invalidates this week's read? A WMT close below $120.00.
Methodology & disclosures. Data: end-of-day options-chain snapshot for WMT, 2026-10-30, generated 2026-11-01T11:07:46.298Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. Earnings dates and reported results are from the data provider's earnings feed as of 2026-11-01T11:07:46.298Z; report dates can change. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.