XLF Options Are Pricing a $1.15 Move — Our Chart Model Sees a Lower Close
Financial-sector options imply a $54.71–$57.01 range into the September 30 expiration while the technical model targets $55.30, and premium is thin enough that buying it beats selling it. Here are the levels and three defined-risk ways to trade the gap.
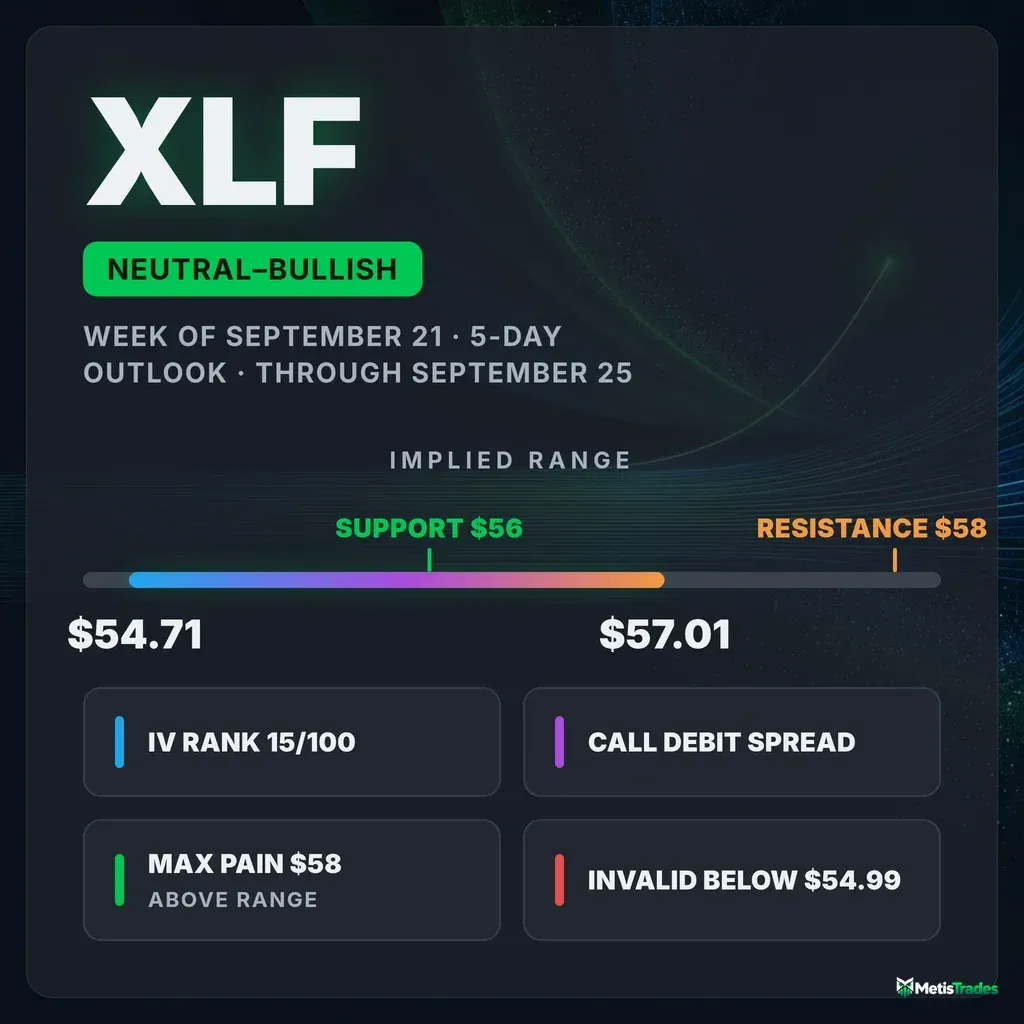
The options market implies a $54.71–$57.01 range into the September 30 expiration; here's what's driving it, where the Sep 25 walls sit, and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18 close
Explore the live XLF options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bullish tilt |
| Last close (Friday, September 18) | $55.86 |
| Options-implied range (into the September 30 expiration) | $54.71 – $57.01 (±2.06%, or ±$1.15) |
| Major support | $56.00 (put wall, September 25 expiration) |
| Major resistance | $58.00 (call wall, September 25 expiration) |
| Max pain (September 25) | $58.00 |
| Dealer gamma regime (estimate) | Negative — hedging tends to amplify moves; flip level ≈ $41.00 |
| Volatility condition | Falling — IV rank 15/100 · premium thin: options priced about 1.5 vol points above delivered movement, richer than only 19% of this fund's own recent readings |
| Technical check | Diverges (bearish, 3-day and 5-day models) |
| Best-fitting strategy | Call debit spread into the September 25 expiration (long premium, defined risk) |
| Analysis invalidated if | XLF closes below $54.99 |
1 · What matters today
XLF closed Friday, September 18 at $55.86 after sliding 2.4% over five sessions. Our read of options flow comes out neutral with a bullish tilt — not because traders are chasing the sector higher, but because the downside hedging that had been piling up all month stopped getting paid for. Puts have gone from expensive relative to calls to unusually cheap relative to calls in the space of a week, and that flattening is what pulls the composite off the floor.
The map is simple: the options market is pricing roughly $1.15 up or down into the September 30 expiration — the move derived from what straddles cost — and the September 25 expiration's own heaviest put strike sits at $56.00 with its heaviest call strike at $58.00. One caution: both chart models we ran are bearish, targeting $55.15 and $55.30. A close below $54.99 ends the constructive read entirely.
2 · What the options market is pricing
What changed this week
Price did the heavy lifting: XLF is down 2.43% over the trailing five sessions and 1.91% over twenty, leaving it 2.6% under its 20-day average and 2.3% under its 50-day, but still 4.0% above its 200-day. The volatility side barely reacted — at-the-money implied volatility (the market's estimate of how much XLF will move, baked into option prices) finished at 14.84%, down 4.4% on the day, up a trivial 0.8% over five sessions and down 28.7% over thirty. IV rank sits at 15/100 versus a 7-day average of 20 and a 14-day average of 17: option prices got cheaper while the fund fell, which is not how a genuine risk event behaves.
Put activity cooled sharply. Friday's put/call volume ratio was 1.20 — for every call contract traded there were 1.2 puts — against a 3-day average of 2.06 and a 14-day average of 2.56. Total option volume still ran 1.74× its 20-day average, so the tape was busy; it simply stopped being one-sided. Open interest tells the slower story: the put/call open-interest ratio is 1.67, meaning 1.67 puts held open for every call, essentially unchanged from its 7-day average of 1.72. The largest forward-looking open-interest builds were all downside protection further out — the January 15, 2027 $50 puts added 24,807 contracts, the November 20 $53 puts added 15,022 on 1,970 contracts of volume, and the October 16 $53 and $55 puts added 12,543 and 11,638 respectively. Into Friday's expiration, the settled $58 puts shed 64,796 contracts of open interest as they rolled off the board.
Our short- and long-term trend reads agree on direction but not on force: the past week's read is clearly bearish (price −2.4%), while the twenty-day and fifty-day reads are flat (−1.9% and +0.6%). The most recent momentum crossover turned bearish on September 8. Translation: this is a sharp two-week pullback inside a two-month range, not a trend break — and that argues for short-dated directional structures and early profit-taking rather than anything held for weeks.
Expected move
Quote quality on the nearest rungs was poor on Friday — every expiration from September 21 through September 29 had call-side and put-side at-the-money volatility too far apart to blend into a usable number, so the first rung this table can price is September 30. That rung implies ±2.06%, or about ±$1.15 around $55.86 — a $54.71 to $57.01 range.
| Expiration | Implied move | Range around $55.86 |
|---|---|---|
| September 30 | ±2.06% | $54.71 – $57.01 |
| October 2 | ±2.71% | $54.35 – $57.37 |
| October 9 | ±3.30% | $54.02 – $57.70 |
| October 16 | ±4.13% | $53.55 – $58.17 |
The ladder rises smoothly with time — no hump, no step-up, no single date the chain is bracing for. For a sector ETF with nothing scheduled inside the window, that flat progression is exactly what you'd expect, and it means the outlook window's pricing is pure time-decay math rather than event risk.
Volatility
At-the-money implied volatility of 14.84% puts IV rank at 15/100 — option prices are cheaper than roughly 85% of the past year's readings. Implied volatility sits below both its 30-day average (15.05%) and its 90-day average (16.50%), and the front-month read is unavailable today because Friday was an expiry date, which is a calendar artifact rather than missing data. Realized volatility — how much XLF has actually been moving — is 13.33% over twenty days and just 10.54% over ten, and the five-day-versus-twenty-day movement ratio of 0.78 sits modestly below this fund's own norm: the last week's slide was steady, not violent. For context, VIX is at the very bottom of its 52-week range (rank 8/100), and XLF's own implied volatility has tracked it only loosely this quarter.
Premium rich or cheap? The volatility risk premium — the gap between how much movement options are priced for and how much XLF has actually delivered — is about 1.5 vol points in favor of sellers. When that gap is positive, option sellers have been collecting more than realized movement cost them. But 1.5 points is thin for this fund: it sits at the 19th percentile of its own recent readings, meaning today's cushion is slimmer than roughly 81% of the last three months. The gap has narrowed steadily over the past week, from about 2.9 points on September 15 to 1.5 on Friday, with no sign flip. Combine IV rank 15/100 with a 19th-percentile premium and the verdict is clear: this is a week to own optionality rather than sell it, and any credit structure here has to earn its keep on structure rather than on rich premium.
Skew and sentiment
The skew reading is the week's outlier and deserves plain language. Skew measures whether puts and calls the same distance from the stock price cost the same — when puts are pricier, traders are paying up for crash protection. XLF's 25-delta measure printed at −35.3 vol points on Friday, against a 60-day median of +1.7. In other words, the usual modest put premium inverted into a large call premium, driven by a 25-delta call implied volatility of 52.0% against a 25-delta put at 16.7%. Versus this fund's own history that is an unusually flat, unusually complacent reading, and over five sessions the put premium bled off by about 40 vol points. Treat the magnitude with care — a one-day print that extreme usually reflects a thin quote on the call side as much as genuine demand — but the direction of travel over the week is real and it is the single biggest reason the positioning read turned constructive.
Sentiment across the curve is split. Short-dated options (0–7 days) lean bearish, as does the 7–30 day bucket, while the 30–60 day and 60–120 day buckets lean bullish — the overall summary reads as a "bullish recovery" profile, with positioning building further out while the front end stays defensive. Two other "vs its own norm" observations worth noting: Friday's price momentum was unusually negative for this fund, and call-side sweeps in the peer-relative unusual-flow screen were unusually dominant (one call contract cleared the bar, zero puts). Those two readings pull in opposite directions — which is precisely why the bias lands near neutral rather than firmly bullish.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $58.60 | 4.7% overhead; the ceiling of the past year |
| Swing resistance | $58.43 | Highest clustered swing pivot in recent price structure |
| Call wall / max pain (Sep 25 expiration) | $58.00 | Heaviest call open interest for the target expiration (2,078 contracts) and the strike where the most option value would expire worthless |
| Swing resistance | $57.36 | Secondary pivot cluster; sits just above the 50-day average |
| 20-day average | $57.38 | Price is 2.6% below it and it is rolling over |
| 50-day average | $57.18 | Price is 2.3% below; the medium-term downtrend marker |
| Swing resistance | $56.65 | First real overhead shelf from price structure |
| Put wall (Sep 25 expiration) / largest gamma strike | $56.00 | Heaviest put open interest for the target expiration (6,425) and the single largest gamma-by-strike concentration in the whole chain — a magnet just above spot |
| Spot | $55.86 | Friday's close, 14 cents under the put wall |
| Options-implied floor (Sep 30) | $54.71 | Lower rail of the priced-in range |
| Swing support | $54.99 | First structural support — the invalidation line for this read |
| 100-day average | $54.90 | Price is 1.75% above it |
| 200-day average | $53.69 | 4.0% below spot; the long-term uptrend is intact above it |
| Swing support | $53.33 | Next shelf if $54.99 fails |
| Gamma flip estimate | ≈ $41.00 | One rough estimate of where market-maker hedging would start amplifying selling — far below spot and not in play |
One disagreement worth naming: the September 25 expiration's own heaviest call strike is $58.00, but across the whole chain the heaviest call open interest sits at $55.00 (126,478 contracts) and the heaviest put at $56.00 (358,376). For the five-day window, the Sep 25 row is what matters; the chain-wide figures tell you where the bigger, longer-dated positions live.
Positioning and unusual flow
Dealer gamma is an estimate, not observed inventory, and it reads negative both across the chain and in the September 25 expiration's own row — under that estimate, market-maker hedging tends to amplify moves rather than cushion them. The flip level that estimate implies sits near $41, far below spot; by this fund's own history, price is sitting unusually far above the flip, which is the supportive side of that framing rather than the fragile one.
Three non-expired flow items stood out:
- September 25 $56 calls — 4,411 contracts traded against 374 open, about $183,000 of premium and the single largest dollar-premium contract at that expiration. Someone wanted short-dated upside right at the put wall.
- September 25 $54 puts — 4,236 contracts against 1,393 open, roughly $53,000 of premium. The mirror hedge, struck a full dollar below the implied-range floor.
- September 22 $56 calls — 1,215 contracts against just 3 open, a 405× turnover ratio. Pure fresh short-dated positioning, again at $56.
The common thread is the $56 strike. It is the put wall, the largest gamma concentration in the chain, and where the week's new short-dated money went. That is where this fund is magnetized.
3 · Technical check
Both chart-model runs are bearish, and both disagree with the options read. The 3-day model targets $55.15 with a projected range of $54.30 to $56.50; the 5-day model, which lands on the same date as our target expiration, targets $55.30 with a projected range of $54.35 to $57.15. Their reasoning is consistent: price is below the short- and medium-term moving averages, the directional index shows sellers in control with trend strength building, and the September 18 breakdown came on a volume spike. Both name $56.27 as the resistance to reclaim and $55.35–$55.45 as the support to defend.
Classify this as Diverges. The direction contradicts the options bias, even though both model targets sit comfortably inside the options-implied $54.71–$57.01 band — this is a disagreement about tilt, not about magnitude. The gap that resolves it is narrow and specific: a daily close back above roughly $56.30 would confirm the options-side read that the hedging wave has crested, while a close under $55.35 hands the argument to the chart.
Model vs. Market: The options market implies $54.71–$57.01 into September 30; the 5-day technical model targets $55.30. The chart expects XLF to drift toward the lower half of a range the options market is pricing symmetrically — a modest, entirely survivable disagreement, but enough to keep the directional structure below small and short-dated.
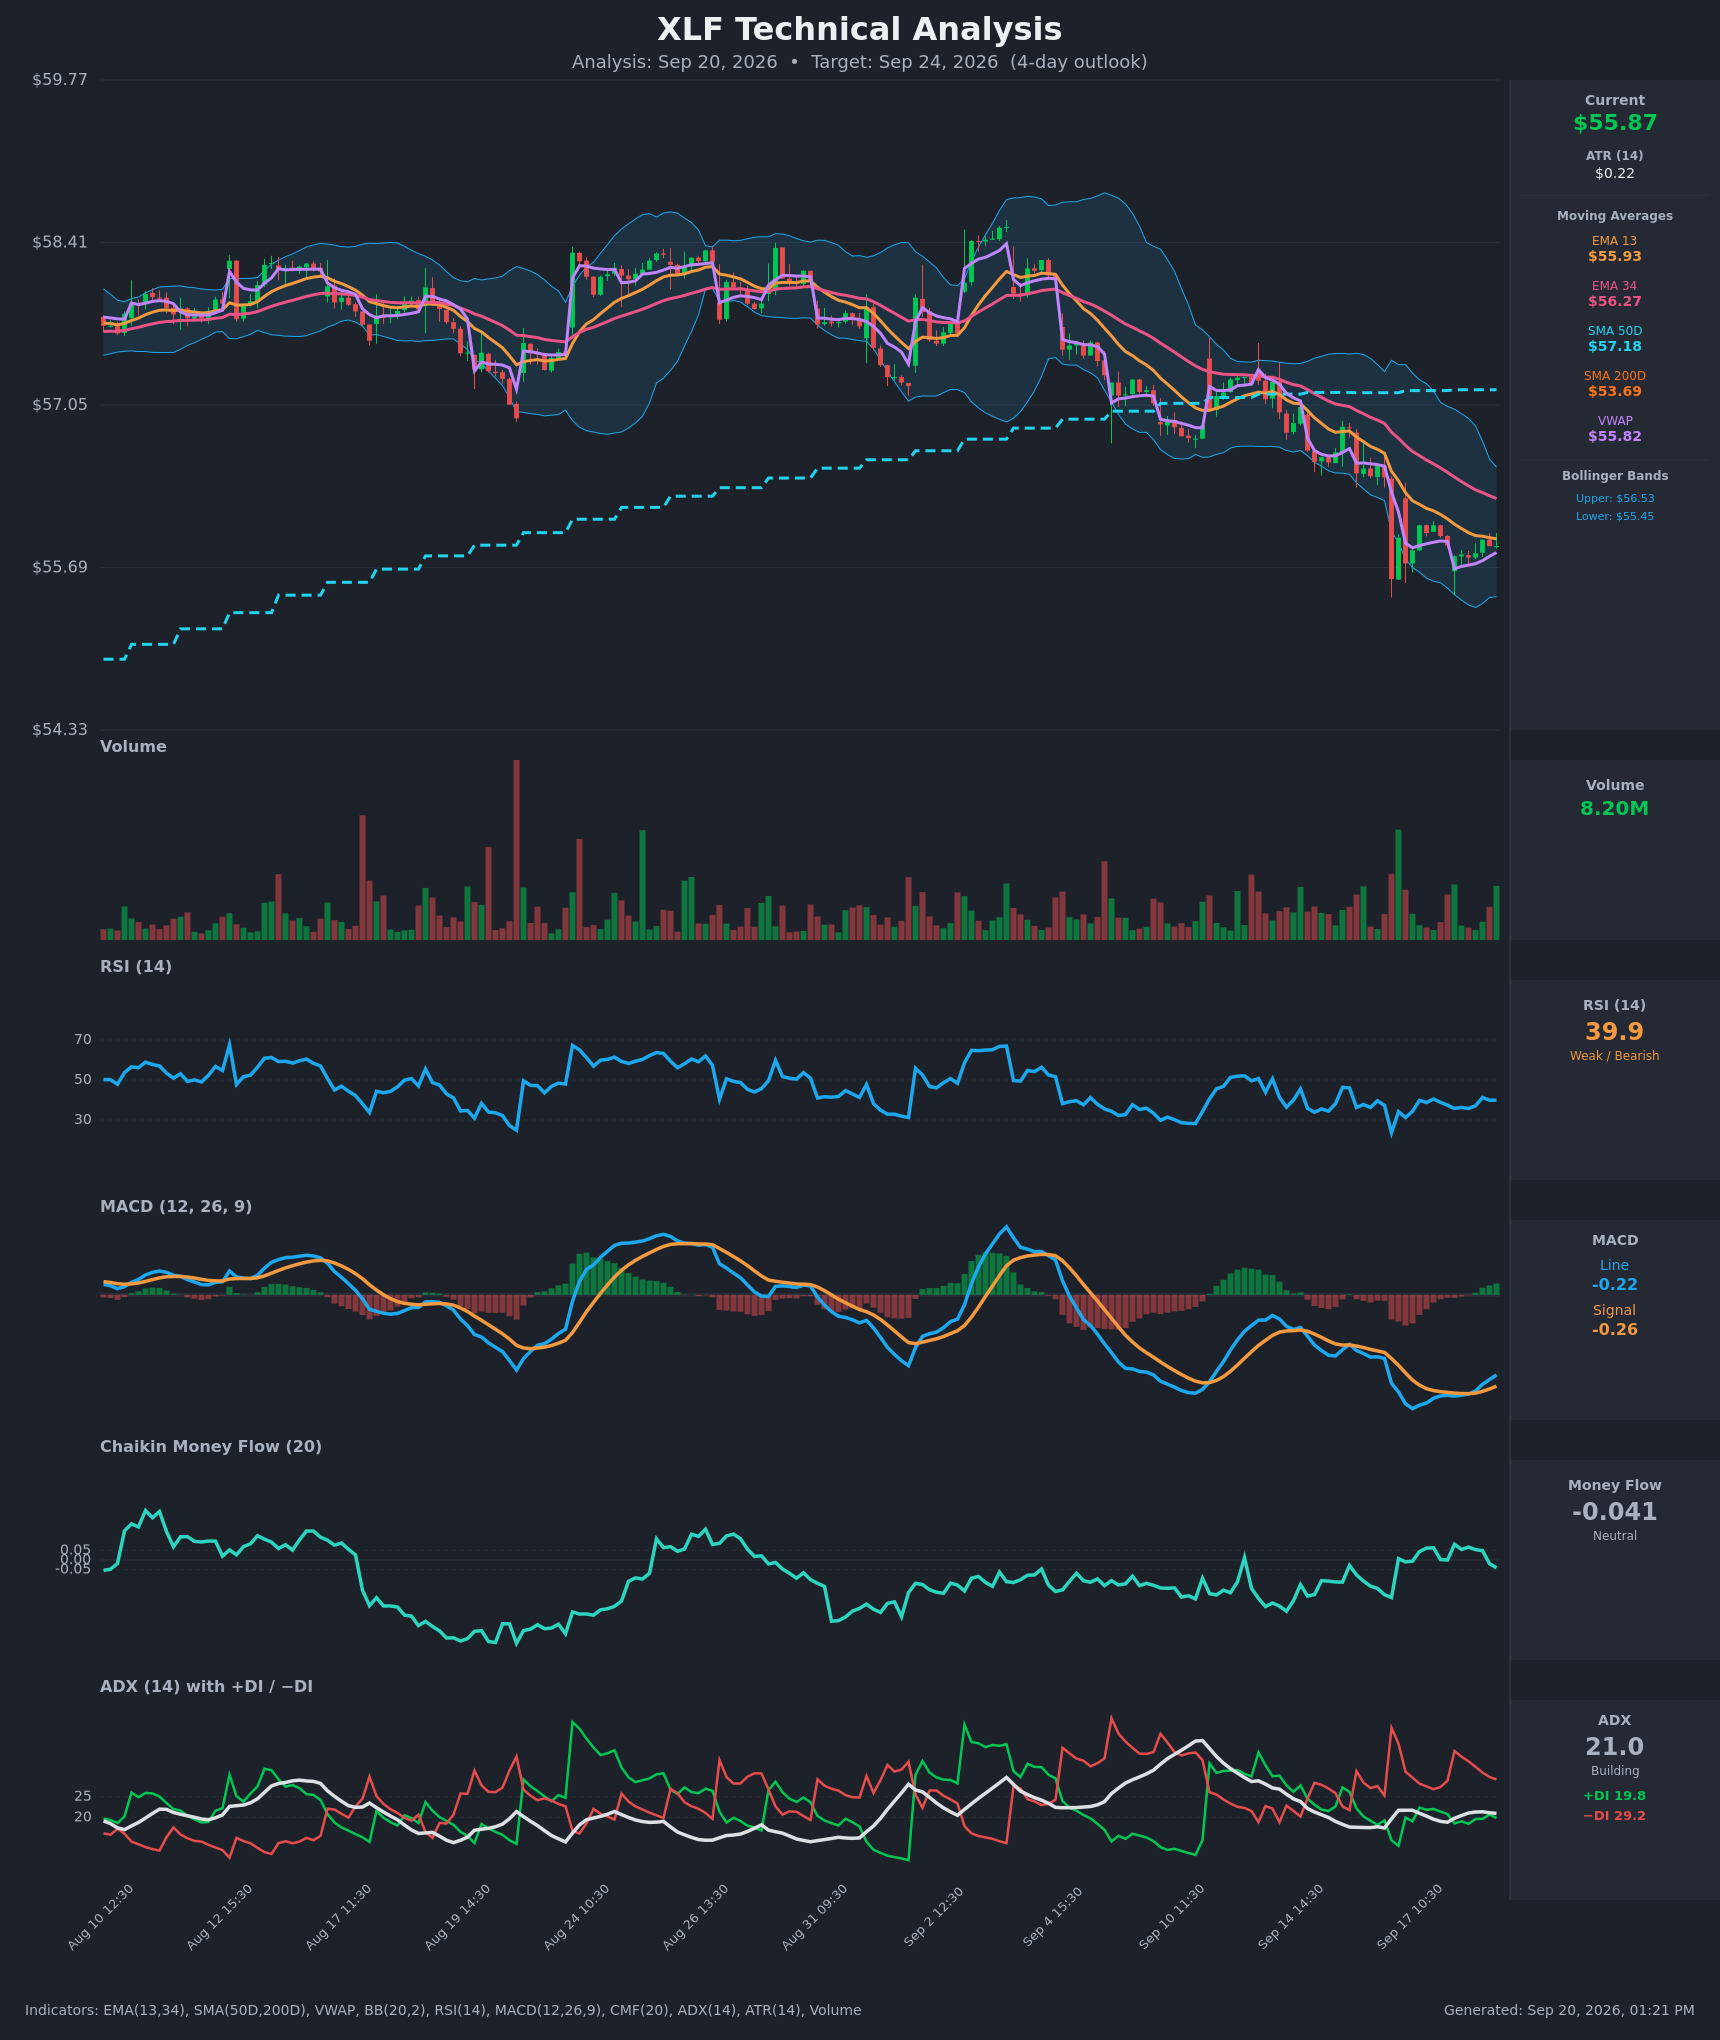
The divergence did move strike selection: rather than shading the bullish structure toward the call wall at $58, it is built to pay off on a move of less than a dollar, and the range structure is centered at $56 instead of above it.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If XLF pushes above the call wall ($58.00): that would require a 3.8% rally in five sessions — well outside anything the chain is pricing. The heaviest call open interest for the September 25 expiration sits there, and stacked call open interest overhead tends to slow rallies as dealers hedge into them. Above $58.00 the positioning above thins out quickly toward the $58.60 52-week high.
If XLF drifts between the walls: the base case. Max pain for September 25 is $58.00, but that strike sits above the entire implied range, so the more useful magnet is the $56.00 put wall — 14 cents above Friday's close, the largest gamma concentration in the chain, and where the week's fresh short-dated flow concentrated. Expirations gravitate toward strikes where the most contracts expire worthless, and between $55 and $57 the hedging flows have plenty to pin against.
If XLF breaks below the put wall and then $54.99: the acceleration case. The negative dealer-gamma estimate implies hedging that adds to moves rather than damping them, and there is no structural support between the implied floor at $54.71 and the swing shelf at $54.99 until the 100-day average at $54.90. That said, the gamma flip estimate near $41 is nowhere near in play, so "acceleration" here means a faster slide toward $53.33, not a cascade.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-09-18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open. One market-wide caveat: bid-ask spreads at the September 25 expiration are wide relative to the option values, so every fill below should be worked with limit orders and none of them should be entered at market.
Premium is thin by this fund's own standards (19th percentile), so the long-premium structure leads and the credit structure carries a health warning.
If you lean bullish: September 25 $56/$57 call debit spread
- Trade: Buy the September 25 $56 call, sell the September 25 $57 call
- Debit: $0.36 · Max profit: $0.64 · Max loss: $0.36 · Break-even: $56.36
- Why it fits: A debit spread means you pay up front and profit if XLF rises — exactly the right shape when IV rank is 15/100 and the premium over delivered movement is only 1.5 vol points. The long strike sits on the $56.00 put wall and the largest gamma strike in the chain; the short strike sits a dollar below the $58.00 call wall, so you are not selling into the heaviest resistance. Risking $36 to make up to $64 on a move of roughly two percent is the cleanest expression of a tilt this modest.
- Makes sense only if: you believe the put-skew flattening is real demand-side news rather than a thin quote, and you accept that both chart models disagree.
- Invalidated if: XLF closes below $54.99.
- Managing it: the short-term trend is fighting this position, so take profit early rather than holding for max value — close at roughly $0.65 if XLF trades through $56.50, and exit by September 23 regardless if the fund is still stuck under $56. Do not add on weakness.
- Liquidity note: the $56 calls quoted 28¢ bid / 55¢ ask on Friday and traded about $183,000 of premium — the busiest contract at that expiration — while the $57 calls quoted 4¢ / 7¢. The long leg is the wide one; leg in with a limit near the midpoint and expect to give up a couple of cents.
- Analyze this position →
If you expect the range to hold: September 25 $56 iron butterfly
- Trade: Sell the September 25 $56 call and the $56 put; buy the $57 call and the $55 put
- Credit: $0.855 · Max profit: $0.855 (at exactly $56.00) · Max loss: $0.145 · Break-evens: $55.15 and $56.86
- Why it fits: A credit structure means you collect premium up front and keep it if price stays put. Every magnet in the chain points at $56.00 — the put wall, the largest gamma strike, the destination of the week's short-dated flow — and the implied move into September 30 is only ±$1.15, so a pin near the body is a live scenario.
- Health warning: you are selling premium that has not been rich lately. At a 19th-percentile volatility premium and IV rank of 15, there is no volatility edge here — only a positioning one. And be honest about the fill: those midpoint prices sit inside very wide markets. Filled at the bid on the short legs and the ask on the longs, the credit drops to about $0.48, max loss rises to about $0.52 and the break-evens tighten to roughly $55.52 and $56.48. Price the trade on that pessimistic version before entering.
- Makes sense only if: you can get filled near the midpoint and you are comfortable with a structure that needs XLF to go almost nowhere.
- Invalidated if: XLF closes below $54.99 or above $57.01.
- Managing it: close at roughly 50% of the credit received; exit no later than September 24 rather than carrying a short-gamma position into expiration day, and if XLF closes through either break-even, close it instead of hoping for a reversion.
- Liquidity note: the $56 puts quoted 46¢ / 82¢ against 6,425 contracts of open interest and the $55 puts 10¢ / 19¢ against 5,806 — the open interest is there, the quotes are not tight. This is a limit-order-only structure.
- Analyze this position →
If you lean bearish: September 25 $56/$55 put debit spread
- Trade: Buy the September 25 $56 put, sell the September 25 $55 put
- Debit: $0.495 · Max profit: $0.505 · Max loss: $0.495 · Break-even: $55.505
- Why it fits: This is the structure that follows the charts rather than the flow. Both technical models target $55.15–$55.30, which sits below this spread's break-even, and the short-term trend read is the most negative of the three horizons. Because implied volatility is cheap, buying the spread costs less than it would in a normal volatility regime — the same reason the bullish structure is a debit.
- Makes sense only if: you weight the price trend above the options positioning, and you treat the skew flattening as a quote artifact rather than a signal.
- Invalidated if: XLF closes above $56.65 (the first swing resistance and the level a reclaim of the moving-average cluster runs through).
- Managing it: this one fights the put wall it is struck on, so take profit into the $55.30 model target rather than waiting for $55.00 — close at roughly $0.80 or exit by September 24, whichever comes first.
- Liquidity note: the $56 puts quoted 46¢ / 82¢ and the $55 puts 10¢ / 19¢; the 36¢ spread on the long leg is wider than most of your max profit, so a bad fill materially changes this trade's arithmetic. Work the spread as a package with a limit.
- Analyze this position →
If none of these: no trade
There is a real case for standing aside here, and it has nothing to do with direction. The September 25 expiration's quotes are wide enough that the ATM volatility reading could not even be computed for that rung, and the bid-ask spreads on every leg above run far past the level where slippage stays a rounding error. Add an options read that tilts up and two chart models that tilt down, and you have a setup where the edge is thin and the execution cost is not. Selling premium is not the answer either: at a 19th-percentile volatility premium, the compensation for taking short-gamma risk is near the bottom of its own recent range. If you cannot get filled close to the midpoint, the honest move is to wait for the October expirations, where the quotes are tighter and the implied ranges are wide enough to build around.
6 · Quick FAQ
What is XLF's expected move over the next week? About ±$1.15, or ±2.06%, into the September 30 expiration — a $54.71 to $57.01 range, per the options market's straddle pricing as of 2026-09-18. The September 25 rung itself could not be priced because call and put quotes disagreed too much to blend.
Is XLF expected to go up or down over the next five days? Options positioning as of 2026-09-18 leans mildly bullish — the put premium that had been building all month flattened out sharply — but that is a read of what traders have already done, not a forecast. Both technical models point the other way, toward $55.15–$55.30. The actionable map is the $54.71–$57.01 range and the $56.00 / $58.00 levels.
Are XLF options expensive right now? No. IV rank of 15/100 says option prices are lower than about 85% of the past year's readings, and on top of that they are running only about 1.5 vol points above the movement XLF has actually delivered — thinner than roughly 81% of this fund's own recent readings. The verdict favors owning premium over collecting it.
Where is XLF's biggest options support and resistance? For the September 25 expiration, the put wall is $56.00 and the call wall is $58.00. Across the entire chain the heaviest put strike is also $56.00, while the heaviest call strike is $55.00 — the longer-dated positioning sits lower than the target expiration's.
What invalidates this read? A close below $54.99.
Methodology & disclosures. Data: end-of-day options-chain snapshot for XLF, 2026-09-18, generated 2026-09-20T13:20:59.297Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.