ARM Options Are Pricing a $21.83 Move Into November 13: Positioning Leans Bearish Below the $190 Wall
ARM options imply a $152.79–$196.45 range into the November 13 expiration. Put skew is at an extreme for this stock, flow is put-heavy, and both chart models lean lower, so our read is neutral with a bearish tilt.
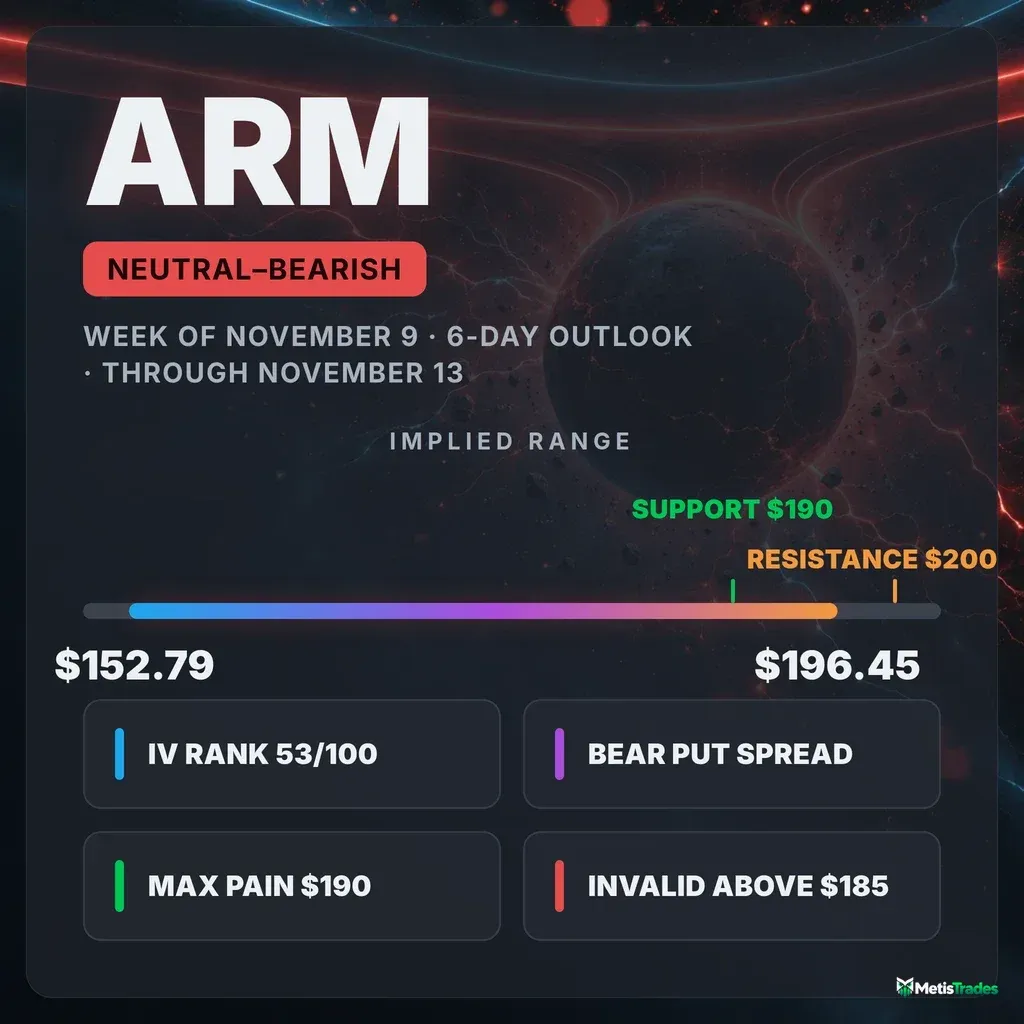
The options market implies a $152.79–$196.45 range for ARM into the November 13 expiration. Below: what is driving that range, where the key levels sit, and three defined-risk ways to trade it.
Published Saturday, November 7, 2026 · Data as of Friday, November 6, 2026 close
Explore the live ARM options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bearish (neutral with a bearish tilt) |
| Options-implied range (into Nov 13) | $152.79 – $196.45 (±12.50%, ±$21.83 around $174.62) |
| Major support | $190.00 put wall for the Nov 13 expiration. It sits above spot, so the nearest real floor below price is the $170 heavy-gamma strike and the $168 technical support. |
| Major resistance | $200.00 call wall (Nov 13 expiration and the whole chain) |
| Max pain (Nov 13) | $190.00 |
| Dealer gamma regime (estimate) | Negative: hedging tends to amplify moves. Flip level: n/a (no estimate available today) |
| Volatility condition | Neutral to easing. ATM IV is 77.54%, down 9.9% on the day and flat over 5 days. IV rank is 53/100. Premium is thin: options are priced about 9 vol points below the movement ARM has actually delivered. |
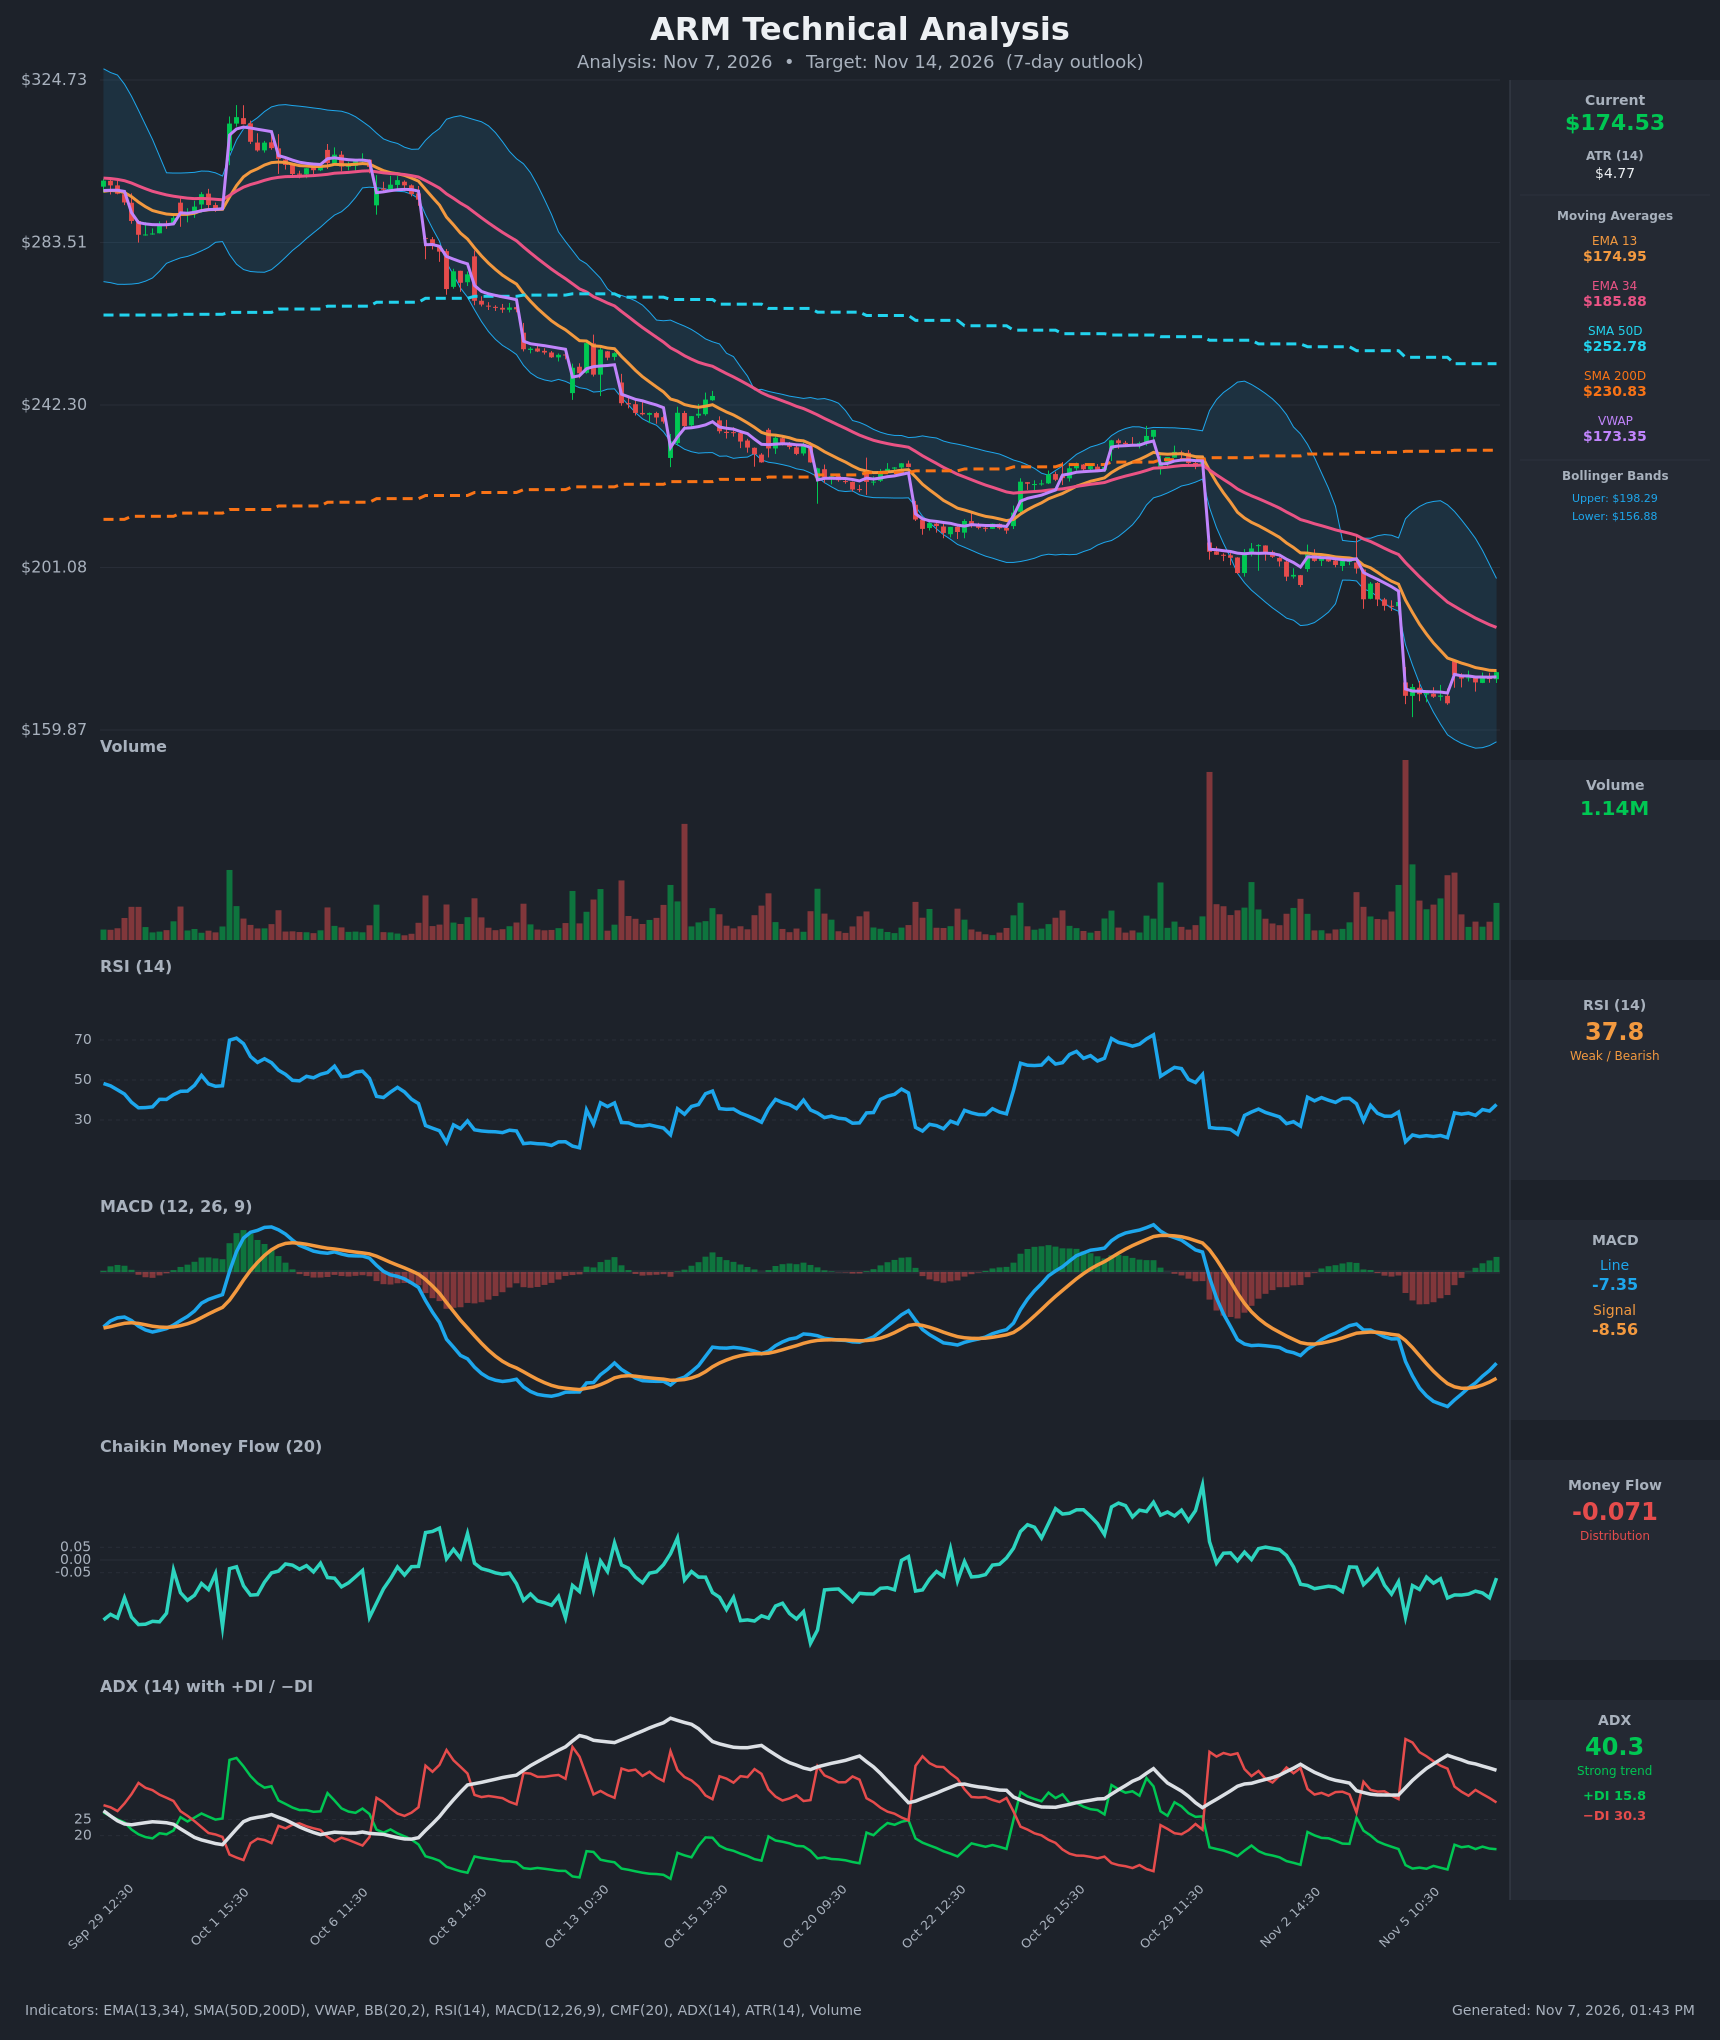
| Technical check | Confirms. Both models are bearish: the 3-day model targets $171.00 and the 6-day model targets $170.00. |
| Best-fitting strategy | Nov 13 $175/$165 bear put (debit) spread, for readers who lean bearish |
| Analysis invalidated if | ARM closes above $185 |
1 · What matters today
ARM closed Friday, November 6, 2026 at $174.62. That is a 15% drop in a week and 34% in a month. Options traders are still paying up for protection.
Puts now cost far more than equally distant calls, which is an extreme reading for this stock. Put trading ran 1.6 times call trading. Our read is neutral with a bearish tilt.
The options market is pricing a move of about $21.83 either way into November 13, a $152.79 to $196.45 range. That is the move implied by what straddles cost.
The level that changes the picture is $185. A close above it would put ARM back into the heavy strike cluster around the $190 max-pain level and undo the bearish tilt.
Both chart-based technical models also lean lower, with targets near $170–$171.
2 · What the options market is pricing
What changed this week
ARM fell 15.2% over the past five sessions. The damage came from two gap-downs: a 9.6% gap on October 30 and a 10.3% gap on November 5. Friday's 6.3% gap up recovered only part of that.
The put/call open-interest ratio climbed from 1.74 to 1.95 over five days. That means 1.95 put contracts are held open for every call contract, above its 7-day average of 1.82. Traders have been adding downside protection, not closing it.
Friday's put/call volume ratio of 1.61 compares with a 7-day average of 1.23 and a 14-day average of 1.00. The tilt toward puts accelerated into the weekend.
The single biggest open-interest build in a live contract was the November 20 $150 puts. They added 1,786 contracts, from 651 to 2,437, which is a hedge placed about 14% below spot.
Into Friday's expiration, the November 6 $170 puts traded 7,567 contracts. That is settled history now, but it shows where the battle was fought.
Our options-flow momentum read flipped bearish on November 5, a week after a brief bullish turn. It sits well below its own two-week average. The short-, medium- and longer-term trend reads all point the same way, so this is not a case of a fresh bounce fighting a bigger downtrend.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For the November 13 expiration it is ±12.50%, or ±$21.83 around $174.62. That gives an implied range of $152.79 – $196.45.
| Expiration | Implied move | Range around $174.62 |
|---|---|---|
| Nov 13 | ±12.50% | $152.79 – $196.45 |
| Nov 20 | ±16.33% | $146.11 – $203.14 |
| Nov 27 | ±18.45% | $142.40 – $206.84 |
| Dec 4 | ±21.65% | $136.81 – $212.43 |
The ladder widens more slowly than time alone would suggest. Front-week options carry about 90% implied volatility, against roughly 74–77% further out. The market is paying the biggest premium for the next few sessions rather than for the weeks after.
Volatility
Implied volatility (IV) is the market's estimate of how much ARM will move, baked into option prices. At-the-money IV is 77.54%. It fell 9.9% on Friday after spiking to about 86% on Thursday's gap-down, and it is essentially flat over five days (−0.5%).
IV sits above its 30-day average (74.2%) but below its 90-day average (80.0%), and it is up 13.1% over 30 sessions.
IV rank shows where today's IV sits versus the past year. At 53/100, it means today's IV is cheaper than 47% of the past year's readings. The percentile is higher, at 71: more than two-thirds of the past year's days traded at lower IV.
The front-month term-structure read is unavailable today (expiry day). The per-expiration chain still shows near-dated options priced richer than the 60-day tenor (73.8%).
ARM's realized movement is running hot. The 10-day realized volatility is 107.9%. The ratio of 5-day to 20-day realized movement is unusually high for this name compared against its own recent history, so moves are accelerating, not calming.
Is premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much ARM has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them.
Today the gap is negative. Options are priced about 9 vol points below the 86.3% the stock has delivered over 20 days. The VRP percentile, which places today's gap against this stock's own recent readings, is 42/100: richer than only 42% of them.
The gap flipped sign in a single session. It was +3.5 points on November 5 and −8.7 points on November 6, after shrinking from about +11.6 points on October 20. Those back-to-back gap-downs loaded the realized-movement window. No earnings report is involved here; the stock has simply been moving harder than options were pricing.
The combination of a mid-range IV rank of 53 and a negative premium over delivered movement argues against selling premium this week. If you trade, owning defined-risk premium makes more sense.
Skew and sentiment
Skew means that puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection.
ARM's 25-delta puts trade at 84.7% IV against 67.8% for the matching calls, so puts run 16.8 vol points over calls. The 60-day norm for this name is −3.7 points, meaning calls were usually the pricier side. Over the past 7 sessions skew averaged roughly flat.
A 20-point swing to the put side in about a week is extreme for ARM. Traders are paying a heavy premium to insure against a further drop.
The put/call ratio measures how much put activity there is relative to calls; above 1 means puts dominate. Friday's put/call volume ratio of 1.61 is unusually put-heavy compared against ARM's own recent history. Its 60-day median is 0.63.
All four put-side contracts that cleared a peer-relative "unusual" volume bar were puts. None were calls.
One counter-current: call open interest rose by 5,709 contracts while put open interest fell by 12,633. That is an unusually large tilt toward calls in new positioning for this name, though part of the put drop reflects positions closing into Friday's expiration.
Sentiment by expiration tells a split story:
- The 0–7 day window reads strongly bullish at +90, but that score rests on a single input: calls being added in the front week.
- The 7–30 day window reads bearish at −29. Its 7-day average is −22.
The overall pattern looks like a leveraged short-dated call chase against a bearish backdrop. We treat it as speculative bounce-buying rather than a change in the underlying positioning.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 50-day moving average | $252.78 | Price is 30.9% below it; the longer trend is firmly down |
| 200-day moving average | $230.83 | 24.4% above spot; a distant overhead marker |
| 20-day moving average | $218.52 | The first trend average overhead, 20% away |
| Swing resistance | $208.30 | The nearest heuristic pivot cluster above price |
| Call wall (Nov 13 and whole chain) | $200.00 | Heaviest call open interest (3,551 contracts on Nov 13) and the chain's largest gamma strike; tends to cap rallies |
| Implied range top (Nov 13) | $196.45 | Upper edge of the priced-in move |
| Put wall and max pain (Nov 13) | $190.00 | The 1,047 puts here are now in the money; max pain also sits here, and it is the chain's second-largest gamma strike |
| Gap-fill zone | $185 – $192 | The unfilled part of the November 5 gap-down; $185 is also a heavy-gamma strike and this article's kill switch |
| Gamma strike | $180 | A heavy open-interest cluster just overhead |
| Technical resistance | $177.60 – $178 | Bollinger midline and the chart models' resistance |
| Spot | $174.62 | Friday's close |
| Gamma strike | $170 | The third-largest gamma strike and the nearest options-based floor below price |
| Technical support | $168 / $166.60 | Near the November 5 low; the chart models' support |
| Implied range bottom (Nov 13) | $152.79 | Lower edge of the priced-in move |
| Put cluster | $150 | Fresh put building in the November 20 expiration |
| Whole-chain put wall | $110 | Heaviest put open interest across all expirations; far below this week's range |
| 52-week low | $100.02 | ARM sits 74.6% above it and 61.4% below the $452.70 high |
The two wall readings disagree. The November 13 put wall ($190) sits above spot, while the whole chain's heaviest put strike is far below at $110. For this window, the Nov 13 levels are the ones that matter.
Positioning and unusual flow
Market makers hedge the options they've sold. One rough estimate suggests that for both the November 13 expiration and the chain as a whole, their hedging currently sits in a negative-gamma regime. In that regime, hedging tends to amplify moves rather than dampen them.
No gamma-flip estimate is available today, so there is no single price where that behavior is estimated to change. Practically, expect follow-through rather than mean reversion on decisive breaks.
Notable live flow from Friday:
- Nov 13 $160 puts: 1,030 contracts traded and open interest jumped from 285 to 811. That is about $350,000 of premium on a short-dated downside bet placed just above the implied range floor.
- Dec 18 $190 calls: 1,448 contracts traded, about $1.68 million in premium, the largest dollar trade in the chain. Someone is positioning for a recovery toward the gap-fill zone over six weeks.
- Feb 19, 2027 $100 puts: 3,735 contracts traded against just 60 open. This is deep crash insurance about 43% below spot.
3 · Technical check
3-day model (target date November 10): bearish, target $171.00, projected range $163.50–$178.50. Key levels are $168 support and $178 resistance. Its dominant scenario, a bearish flag breakdown, is invalidated by a close above $180.
The target sits well inside the options-implied range and matches our bearish tilt. Classification: Confirms.
6-day model (target date November 13): bearish, target $170.00, projected range $164.00–$178.00. Key levels are $166.60 support and $177.60 resistance. Its dominant scenario is invalidated by a daily close above $178 on rising volume.
Classification: Confirms. Both reports point to the same evidence:
- A strong, easing downtrend: ADX is near 40, with sellers' directional strength about double buyers'.
- A bounce on light volume.
- A fresh MACD bullish crossover deep below zero. Both models treat it as a relief signal, not a reversal.
Model vs. Market: The options market implies $152.79–$196.45 into November 13. The 6-day technical model targets $170.00 inside a much tighter $164.00–$178.00 band. Options are pricing roughly three times the movement the chart model expects, so the market is bracing for another gap rather than a drift.
The technical targets shaped strike selection below. The bearish spread's break-even sits near $171, and its short strike at $165 sits just under the models' $166.60–$168 support.
Full technical write-ups: 3-day report → · 6-day report →
4 · Three ways the week can go
If ARM pushes back toward the max-pain level ($190) and the call wall ($200): A close above $185 would mean ARM is filling the November 5 gap and climbing back into the heaviest strike cluster. The November 13 max pain and the in-the-money put pile both sit at $190, so expiring positioning could pull price there.
Above that, the 3,551-contract call wall at $200 tends to slow rallies. Getting there would take a recovery of roughly 15% in six sessions.
If ARM drifts between $168 and $180: This is the consolidation case both chart models allow for. Heavy open interest at $170 and $180 brackets price, but negative gamma means that drift is fragile.
The short-dated call chase could fade or it could squeeze. Either way, the expiring structure gives no strong pin inside this band.
If ARM breaks below $168: This is the acceleration case. One rough estimate suggests market-maker hedging is currently amplifying moves, so a break of the November 5 lows could follow through toward the $160 puts traders bought on Friday.
The lower edge of the implied range sits at $152.79, and fresh put building at $150 sits just beyond it.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 6, 2026. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
Because options are currently priced below delivered movement, the debit (premium-buying) structures lead. The bearish spread comes first because it matches our tilt.
If you lean bearish: bear put spread
A bear put spread means you pay a debit to buy a higher-strike put and sell a lower-strike put. You profit if the stock falls, and both your risk and your reward are capped.
- Trade: Buy the Nov 13 $175 put (mid $8.90), sell the Nov 13 $165 put (mid $5.03).
- Debit: $3.88 ($387.50 per spread) · Max profit: $612.50 · Max loss: $387.50 · Break-even: $171.13
- Why it fits: It owns premium at a time when options are priced about 9 points below delivered movement. Put skew is extreme, flow is put-heavy, and the break-even sits at the two technical targets ($170–$171).
- Makes sense only if: ARM stays below the $177.60–$178 resistance band in the first sessions.
- Invalidated if: ARM closes above $180.
- Managing it: Take profits around 60–75% of max value if ARM reaches the $166–$168 area early. With the near-term flow and the bigger trend both pointing down, there is little reason to rush. Close by November 12 rather than hold through expiration-day gamma.
- Liquidity note: The $175 puts were 80¢ wide ($8.50/$9.30) and the $165 puts 45¢ wide ($4.80/$5.25), roughly 9% of mark. Expect some slippage; work the order near the mid.
- Analyze this position →
If you expect the range to hold: iron condor
An iron condor means you collect a credit by selling an out-of-the-money put spread and an out-of-the-money call spread. You keep it if ARM stays between the short strikes.
- Trade: Sell the Nov 13 $155 put (mid $2.60) and buy the $150 put (mid $1.84). Sell the Nov 13 $195 call (mid $1.92) and buy the $200 call (mid $1.29).
- Credit: $1.40 ($139.50) · Max profit: $139.50 · Max loss: $360.50 · Break-evens: $153.61 and $196.40
- Why it fits: The short strikes sit right at the implied-range edges ($152.79/$196.45). The call side is tucked under the $200 call wall. The chart models' ranges sit comfortably inside.
- Health warning: You're selling premium that hasn't been rich lately. ARM has been delivering more movement than options price, and negative gamma can carry a break straight through a short strike.
- Makes sense only if: You expect the post-gap consolidation to hold and volatility to cool.
- Invalidated if: ARM closes below $155 or above $195.
- Managing it: Close at about 50% of the credit. Exit the threatened side immediately if price tags $160 or $190.
- Liquidity note: The $200 calls were 11¢ wide and the $155/$150 puts 28¢/24¢ wide. The $195 calls were 42¢ wide, about 22% of mark, so that leg will leak edge.
- Analyze this position →
If you lean bullish: bull call spread
A bull call spread means you pay a debit to buy a call and sell a higher-strike call. You profit from a rise, capped at the short strike.
- Trade: Buy the Nov 13 $175 call (mid $8.55), sell the Nov 13 $185 call (mid $4.38).
- Debit: $4.18 ($417.50) · Max profit: $582.50 · Max loss: $417.50 · Break-even: $179.18
- Why it fits: It plays the front-week call chase and the MACD relief signal toward the $185–$192 gap-fill zone, while capping cost when premium is not rich.
- Makes sense only if: ARM reclaims $177.60–$178 on rising volume early in the window.
- Invalidated if: ARM closes below $168.
- Managing it: This trade fights the trend, so keep it short and tight. Take profits near $183–$185 and cut it if $178 fails twice.
- Liquidity note: The $175 calls were 50¢ wide and the $185 calls 25¢ wide, both about 6% of mark. Fills are workable.
- Analyze this position →
If none of these: no trade
Standing aside is a reasonable choice this week. ATM IV of 77.54% still makes every debit structure expensive in absolute terms. At the same time, the negative premium over delivered movement removes the usual edge for selling.
The positioning itself is contradictory:
- Extreme put skew and put-heavy volume point lower.
- A max-pain level and in-the-money put pile sit $15 above spot.
- Front-week calls are being chased.
With hedging likely amplifying moves, a gap of $20 or more in either direction is entirely within what the market prices. If you can't size for that, watching is a position too.
6 · Quick FAQ
What is ARM's expected move into November 13? About ±$21.83 (±12.50%), a $152.79–$196.45 range, per straddle pricing as of November 6, 2026.
Is ARM expected to go up or down this week? Options positioning as of November 6 leans slightly bearish, driven by extreme put skew and put-heavy flow. That is a read of what traders have done, not a forecast. The actionable map is the $152.79–$196.45 range, the $190 put wall/max pain and the $200 call wall.
Are ARM options expensive right now? IV rank of 53/100 says option prices are higher than 53% of the past year's readings. They are also running about 9 vol points below the movement ARM has actually delivered, richer than only 42% of this stock's own recent readings. Premium is not rich relative to how the stock is moving.
Where is ARM's biggest options support and resistance? For the Nov 13 expiration, the put wall is $190 and the call wall is $200. Because the put wall sits above spot, the nearest options floor below price is the $170 gamma strike.
What invalidates this week's read? A close above $185.
Methodology & disclosures. Data: end-of-day options-chain snapshot for ARM, 2026-11-06, generated 2026-11-07T13:43:30.855Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.