NIO Options Outlook: Will $3.50 Pull Price In Before November 13?
NIO options imply a $3.15–$3.63 range into the November 13 expiration, and that expiration's call wall, put wall and max pain all sit at $3.50, just above Friday's $3.39 close. Here is what the positioning shows and three defined-risk ways to trade it.
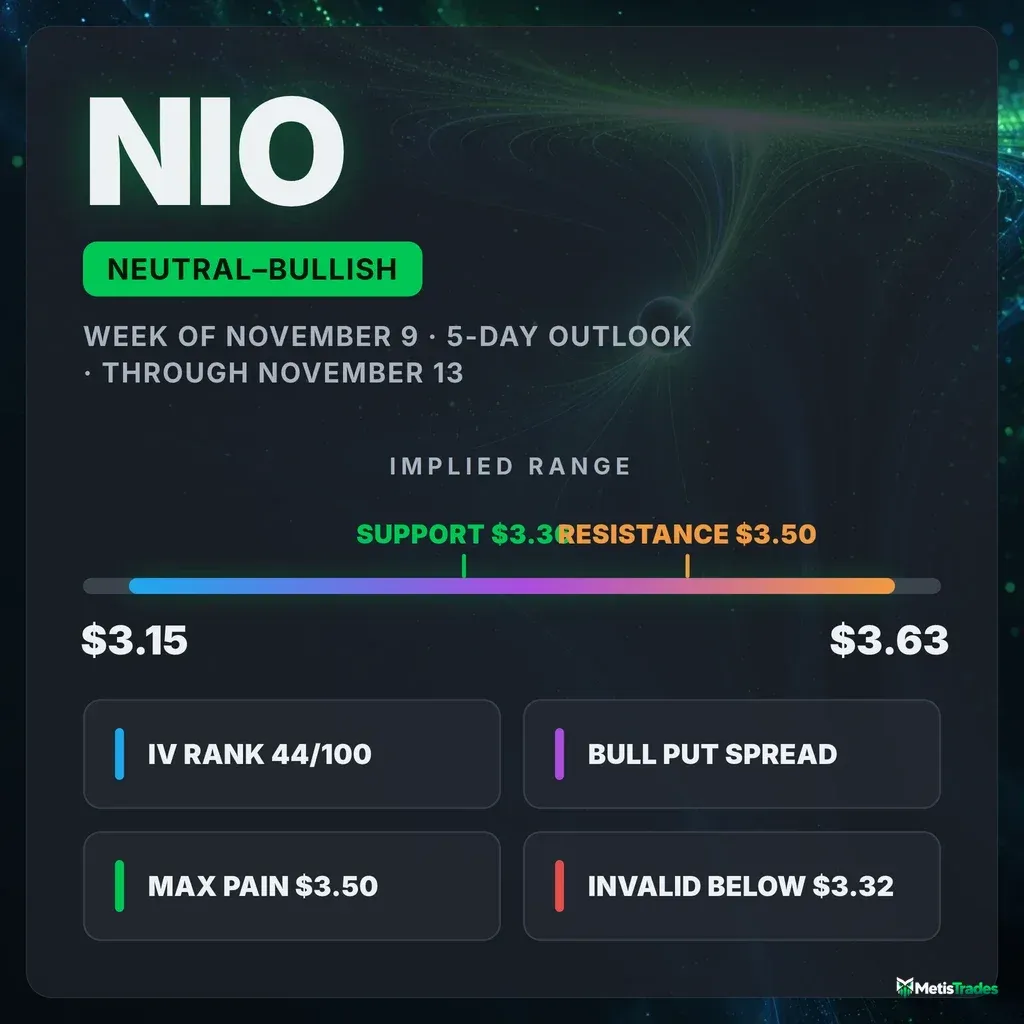
The options market implies a $3.15–$3.63 range into the November 13 expiration. That expiration's heaviest call strike, heaviest put strike and max pain all sit at $3.50, and the sections below cover what that means and three defined-risk ways to trade it.
Published Sunday, November 8, 2026 · Data as of Friday, November 6, 2026 close
Explore the live NIO options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a slight bullish tilt |
| Options-implied range (into November 13) | $3.15 – $3.63 (±6.95%, about ±$0.24) |
| Major support | $3.36 (swing support). The November 13 put wall is at $3.50, above spot. |
| Major resistance | $3.50 (November 13 call wall) |
| Max pain (November 13) | $3.50 |
| Dealer gamma regime (estimate) | Positive, so hedging tends to dampen moves. Flip level ≈ $7 (a rough estimate driven by far out-of-the-money call open interest). |
| Volatility condition | Neutral: flat this week after a 33% rise over 30 days. IV rank 44/100. Premium is fair, with options priced about 16 vol pts above delivered movement. |
| Technical check | Confirms (bullish; 3-day model target $3.43, 5-day model target $3.46) |
| Best-fitting strategy | Bull put spread at $3.50/$3.00 (November 13), only if the gap holds |
| Analysis invalidated if | NIO closes below $3.32 |
1 · What matters today
NIO closed Friday at $3.39 after a 5.6% bounce over five sessions. The options market leans neutral with a slight bullish tilt into the November 13 expiration.
The single most important fact is that the expiration's biggest call position, biggest put position and max pain all stack on one strike, $3.50. Max pain is the price where the most option value would expire worthless, and expirations sometimes gravitate toward it. When all three cluster on one strike just 11 cents above spot, that strike tends to act as a magnet.
Options are pricing a move of about $0.24 either way, a $3.15–$3.63 range. The level that changes the picture is $3.32. A close below it says Friday's gap-up has failed.
Both chart models agree with a modest drift higher, targeting the mid-$3.40s.
2 · What the options market is pricing
What changed this week
The week's headline is price. NIO rose 5.6% over five sessions, including four straight gap-up opens, the latest from a $3.20 prior close.
Options flow turned with it, sharply. Our read of options-flow momentum jumped to +40 on Friday from −6 the day before, against a 7-day average of −9. That is a one-session swing, not a settled trend.
Implied volatility barely moved over the five days (down 0.9%). Put/call open interest drifted to 0.68, slightly below its 7-day average of 0.70. In plain terms, traders thinned out puts a little rather than piling into calls.
The biggest open-interest change was a cut: the December 18 $4 calls shed 2,243 contracts. In the target expiration, the November 13 $3.50 calls added 744 contracts to 6,155. Into Friday's now-settled expiration, the November 6 $3.50 puts shed 1,125 contracts of open interest, which is history rather than a live level.
The bigger tension is between timeframes. The past week's bounce runs against a stock still down 5.3% over the past month and about 22% over the past two-and-a-half months. Near-term flow and the bigger trend point different ways. That argues for short-dated structures and early profit-taking rather than open-ended bullish bets.
Expected move
The expected move is the move the options market is pricing in, derived from what straddles cost. For November 13 it is ±6.95%, or about $0.24 either way from the $3.39 chain price. That gives a range of $3.15 to $3.63.
| Expiration | Implied move | Range around $3.39 |
|---|---|---|
| November 13 | ±6.95% | $3.15 – $3.63 |
| November 20 | ±11.82% | $2.99 – $3.79 |
| November 27 | ±13.9% | $2.92 – $3.86 |
| December 4 | ±15.04% | $2.88 – $3.90 |
The November 13 rung is priced noticeably cheaper than the next one. Its at-the-money IV is about 50%, against roughly 60% for November 20. So the near week is priced calmer than the weeks behind it.
Volatility
Implied volatility (IV) is the market's estimate of how much NIO will move, baked into option prices. At-the-money IV is 56.34%.
IV rank is 44/100. IV rank shows where today's IV sits versus the past year, so 44 means today's IV is cheaper than about 56% of the past year's readings, or roughly mid-range. IV is down 4.4% on the day and flat over five days. Over 30 days it is up 33%, and it sits above both its 30-day average (49.5%) and its 90-day average (52.9%).
Term structure compares option prices across expiration dates. The front-month read is unavailable today because Friday was an expiry day. The ~60-day IV reads 57.1%.
Measured against this stock's own recent history, two things stand out. Here, "unusually high" means unusual for NIO, not versus the broader market. First, NIO's movement has been accelerating: the past week's realized swings are running well above its pace for the month. Second, the five-day price push is unusually strong for this name.
Is premium rich or cheap? The volatility risk premium is the gap between how much movement options are priced for and how much NIO has actually delivered. When it is positive, option sellers have been collecting more than realized movement cost them.
- Options are priced about 16 vol points above NIO's 20-day realized volatility of 40.3%.
- That gap sits at 48/100 versus this stock's own recent readings, so it is richer than about half of them. In other words, it is ordinary for NIO.
Together, IV rank 44 and a middling premium over delivered movement give neither buyers nor sellers of premium a structural edge this week. Structure choice should follow direction, not volatility.
Skew and sentiment
Skew describes the fact that puts and calls the same distance from the stock price don't cost the same. When puts are pricier, traders are paying up for crash protection.
On Friday the relationship flipped hard. Out-of-the-money calls priced at about 130.7% IV versus 66.9% for the equivalent puts, so calls are 63.7 vol points richer. That compares with a 60-day norm where puts ran about 5.5 points over calls, and it is stretched well beyond NIO's usual range. The same reading showed puts richer by 106.6 points on November 2. On a $3 stock with $0.50 strikes these wing readings swing violently, so treat the size as noise and the direction as the signal: the fear premium in puts has drained out.
The put/call ratio measures how much put activity there is relative to calls; above 1 means puts dominate.
- Volume: put/call volume was 0.19, meaning about one put traded for every five calls. That is in line with the 7-day average of 0.20 and below the 14-day average of 0.22, so call-leaning but not frenzied.
- Total activity: total option volume ran at only 0.78× its 20-day average, so this was not a high-conviction rush.
Sentiment in short-dated options reads "broadly bullish." The 0–7 day expirations score +23, slightly below their 7-day average of +30. The 7–30 day expirations score +39, well above their 7-day average of +14. Our leading positioning read, built only from flow and skew, sits near the top of its range for the past month.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Whole-chain call wall / gamma flip estimate | $7 | 230,540 open calls across all expirations. The flip level is a rough estimate anchored by that pile, not a level in play this week. |
| 200-day moving average | $4.86 | Long-term trend line; price sits 30% below it. |
| 100-day moving average | $4.15 | Intermediate trend; 18% overhead. |
| November 20 walls and max pain; largest gamma strike | $4 | Next expiration's call wall (69,900) and put wall (33,963) both sit here, the next magnet beyond this window. |
| Swing resistance | $3.79 | Prior pivot cluster. |
| Swing resistance / upper implied edge | $3.63 | Prior pivot that coincides with the top of the November 13 range. |
| Swing resistance | $3.55 | Pivot cluster just above the 50-day. |
| 50-day moving average | $3.54 | The line that defines the current downtrend. |
| November 13 call wall, put wall and max pain | $3.50 | 6,155 calls and 1,822 puts. All three markers of the target expiration sit here, and it is also the second-largest gamma strike. |
| Spot (Friday close) | $3.39 | Reference price. |
| Swing support | $3.36 | First pivot support below spot. |
| 20-day moving average | $3.34 | Price reclaimed it this week. |
| Gap origin | $3.20 | Friday's gap opened from this prior close. |
| Swing support | $3.16 | Lower pivot, essentially at the $3.15 lower implied edge. |
| 52-week low | $3.10 | Price is only 9% above it. |
| Gamma strike | $3 | Third-largest gamma concentration in the chain. |
| Whole-chain put wall | $2 | 188,198 open puts, mostly long-dated hedges. |
Positioning and unusual flow
Market makers hedge the options they've sold. One rough estimate puts both the whole chain and the November 13 expiration in a positive-gamma regime, where their hedging tends to dampen moves. In that regime, price is often leaned back toward heavy strikes like $3.50 rather than pushed away from them.
The same estimate places the gamma flip, the level below which hedging tends to accelerate selling rather than cushion it, near $7. Spot sits unusually far below that for NIO, which would normally suggest fragility. Because that flip estimate reflects a giant far out-of-the-money call pile, we give more weight to the expiration-level read.
Notable live flow (open interest is contracts currently held open):
- January 15 $4 calls: 2,767 contracts traded, about $37,354 in premium, the day's largest by dollars. Open interest rose by 1,190 to 40,714. That is longer-dated upside interest, not a bet on this week.
- November 27 $4 calls: 2,537 contracts traded against 3,844 open, about $8,879 in premium. That is heavy turnover in a cheap lottery-style strike.
- November 13 $3.50 calls: 1,807 traded and open interest grew to 6,155. This is the wall itself getting bigger, reinforcing the pin.
3 · Technical check
3-day model (target November 11): Bullish, with a $3.43 target and a projected range of $3.30–$3.47. Both sit inside the options-implied $3.15–$3.63 range, so this confirms the options read. Its key levels are support at $3.32 and resistance at $3.48. It flags a rising trend-strength reading of 26.2, with buyers in control, as the main bullish evidence.
5-day model (target November 13): Also bullish, with a $3.46 target and a projected range of $3.30–$3.52. This also confirms, landing just shy of the $3.50 pin. Both models flag the same caution: money-flow stays negative at −0.166 despite the rally, meaning the bounce has not had volume-weighted buying behind it. Both name a close below $3.32 as their invalidation, which we adopt as ours.
Model vs. Market: The options market implies $3.15–$3.63 into November 13; the 5-day technical model targets $3.46. Both point at a modest drift toward the $3.50 cluster rather than a breakout.
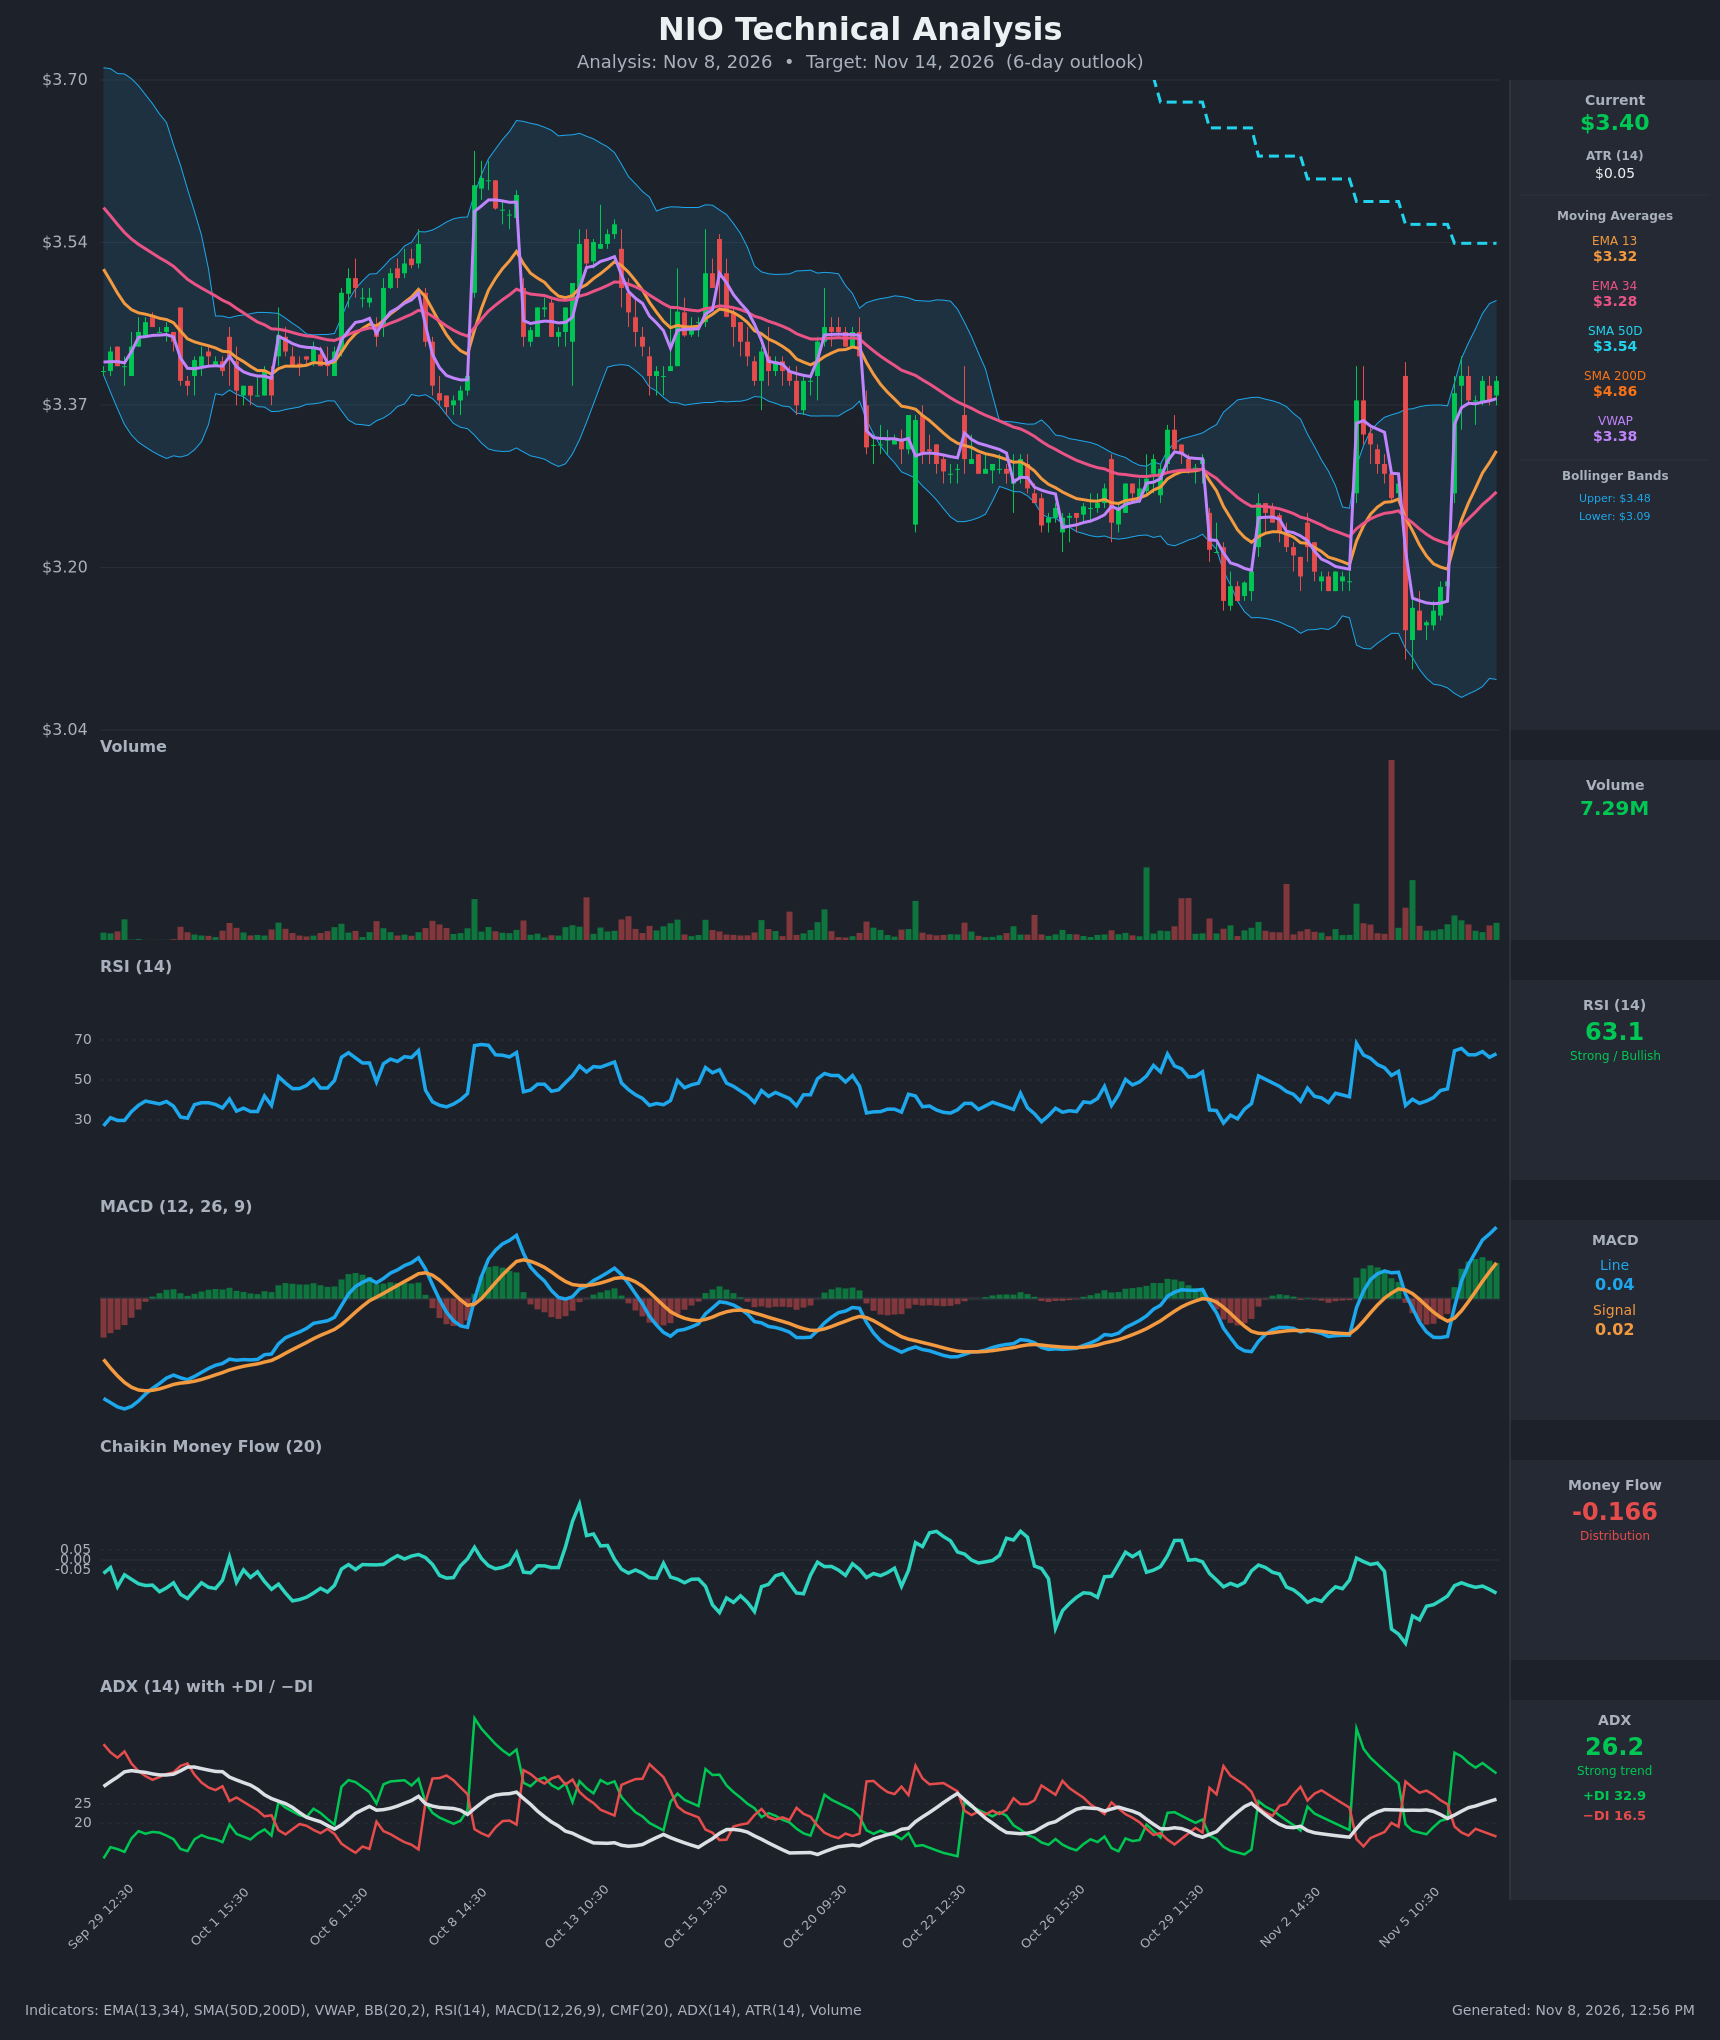
Full technical write-ups: 3-day report → · 5-day report →
The technicals didn't move our strikes. They reinforced keeping the upside target at $3.50 and setting the invalidation at $3.32.
4 · Three ways the week can go
If NIO pushes through $3.50: The heaviest November 13 call stack sits right there, so rallies tend to slow as they arrive. A clean close above $3.50 meets the 50-day average ($3.54) and swing resistance ($3.55) almost immediately. The next clear marker is $3.63, which is also the top of the implied range. Beyond that, the November 20 walls at $4 become the next magnet, but that is outside this window.
If NIO drifts toward the cluster: This is the pin case. With the call wall, put wall and max pain all at $3.50, and a positive-gamma estimate at that expiration, hedging flows and expiring open interest tend to pull price toward $3.50 into November 13. This is the branch our tilt favors, and it is where the range and pin structures below get paid.
If NIO loses $3.36 and then $3.32: A close below $3.32 means Friday's gap has failed. Little positioning stands between there and the $3.20 gap origin, then $3.16 support near the lower implied edge. The far-off gamma flip estimate offers no cushion story either. Downside moves on this name have tended to run, which is why that is the kill switch.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of November 6. All structures are hypothetical. Verify live prices before trading, because these will be stale by the open. All three expire November 13.
If you lean bullish: Bull put spread
A credit spread: you collect premium up front and keep it if the stock stays above the short strike.
- Trade: Sell the November 13 $3.50 put ($0.165) and buy the November 13 $3.00 put ($0.01).
- Credit: $0.155 ($15.50 per spread) · Max profit: $15.50 at or above $3.50 · Max loss: $34.50 at or below $3.00 · Break-even: $3.345
- Why it fits: The short strike is the $3.50 pin itself. You earn full credit if the max-pain magnet pulls price there, and you keep most of it on a mild drift up. Bullish 7–30 day sentiment and drained put skew support a modest upward lean.
- Makes sense only if: Friday's gap holds above the 20-day average ($3.34).
- Invalidated if: NIO closes below $3.32.
- Managing it: Close at about 50–60% of the credit. Exit by November 12 rather than holding into expiration-day pin risk. Because the near-term pop fights the bigger downtrend, take profits early rather than waiting.
- Liquidity note: The $3.50 puts quoted $0.14/$0.19, 5¢ wide, which is about 30% of the mark. The $3.00 puts trade at a penny. Work the order near the mid and expect some slippage.
- Analyze this position →
If you expect the range to hold: Iron butterfly centered on $3.50
A four-leg credit structure: you sell the $3.50 straddle and buy wings for protection. It profits most if price lands right on the center strike.
- Trade: Buy the November 13 $3.00 put ($0.01), sell the $3.50 put ($0.165), sell the $3.50 call ($0.045), and buy the $4.00 call ($0.01).
- Credit: $0.19 ($19 per structure) · Max profit: $19 at exactly $3.50 · Max loss: $31 at or beyond $3.00 or $4.00 · Break-evens: $3.31 and $3.69
- Why it fits: This is the purest expression of the pin. Max pain, both walls and a positive-gamma estimate all sit on the center strike. The profit zone of $3.31–$3.69 covers most of the implied range above the gap.
- Makes sense only if: NIO stays between the gap and the 50-day average for most of the window.
- Invalidated if: NIO closes below $3.32.
- Managing it: Take 30–40% of max profit when offered, since butterflies rarely pay in full. Exit by November 12 if price drifts away from $3.50.
- Liquidity note: The $3.50 calls quoted $0.04/$0.05 (1¢ wide) and the $3.50 puts were 5¢ wide. Both wings trade at a penny. Four legs on sub-$0.20 options means fills can eat a meaningful share of a $0.19 credit, so enter as a single order at a limit.
- Analyze this position →
If you lean bearish: Bear put spread
A debit spread: you pay up front and profit if the stock falls toward the lower strike.
- Trade: Buy the November 13 $3.50 put ($0.165) and sell the November 13 $3.00 put ($0.01).
- Debit: $0.155 ($15.50 per spread) · Max profit: $34.50 at or below $3.00 · Max loss: $15.50 at or above $3.50 · Break-even: $3.345
- Why it fits: This is the contrarian case. The bigger trend is still down, the stock sits only 9% above its 52-week low, and both chart models flag that money-flow never confirmed the bounce. It is the exact mirror of the bullish spread, with cheap entry for a gap-fill toward $3.20.
- Makes sense only if: NIO loses $3.32 early in the window.
- Invalidated if: NIO closes above $3.50.
- Managing it: Take profits near $3.20. Cut the trade if the $3.32 break hasn't happened by November 11, the midpoint checkpoint.
- Liquidity note: Same strikes as the bullish spread. The $3.50 puts are 5¢ wide, so expect to pay above mid.
- Analyze this position →
If none of these: no trade
Standing aside is a reasonable choice here:
- Premium is only ordinary for NIO, so there is no volatility edge either way.
- Strikes are 50 cents apart on a $3.39 stock.
- Bid-ask spreads are a large fraction of every leg's value.
- Friday's bullish flow is a single-session swing against a two-month downtrend.
If you can't get fills near the midpoint, the costs can wipe out the edge the pin offers. Watching how price behaves around $3.36 and $3.50 by the November 11 checkpoint costs nothing.
6 · Quick FAQ
What is NIO's expected move this week?
About ±$0.24 (±6.95%) into November 13, a $3.15–$3.63 range, per straddle pricing as of November 6.
Is NIO expected to go up or down over the next week?
Options positioning as of November 6 leans neutral with a slight bullish tilt. Max pain and both walls sit at $3.50, just above spot, and short-dated sentiment is call-leaning. That is a read of what traders have done, not a forecast. The actionable map is the $3.15–$3.63 range, $3.36 support and $3.50 resistance.
Are NIO options expensive right now?
IV rank of 44/100 says option prices are cheaper than about 56% of the past year's readings. They run about 16 vol points above the movement NIO has actually delivered, richer than about half of this stock's own recent readings. Overall, that is fair pricing with no clear edge for buyers or sellers.
What invalidates this week's read?
A close below $3.32, which would mean Friday's gap-up has failed.
Methodology & disclosures. Data: end-of-day options-chain snapshot for NIO, 2026-11-06, generated 2026-11-08T12:56:36.318Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.