NIO Options Are Pricing a $0.23 Move: Our Positioning Read Leans Bearish While the Chart Says Up
NIO options imply a $3.35–$3.81 range into the October 16 expiration. Skew and put-volume pace give positioning a slightly bearish lean, while both chart models point modestly higher.
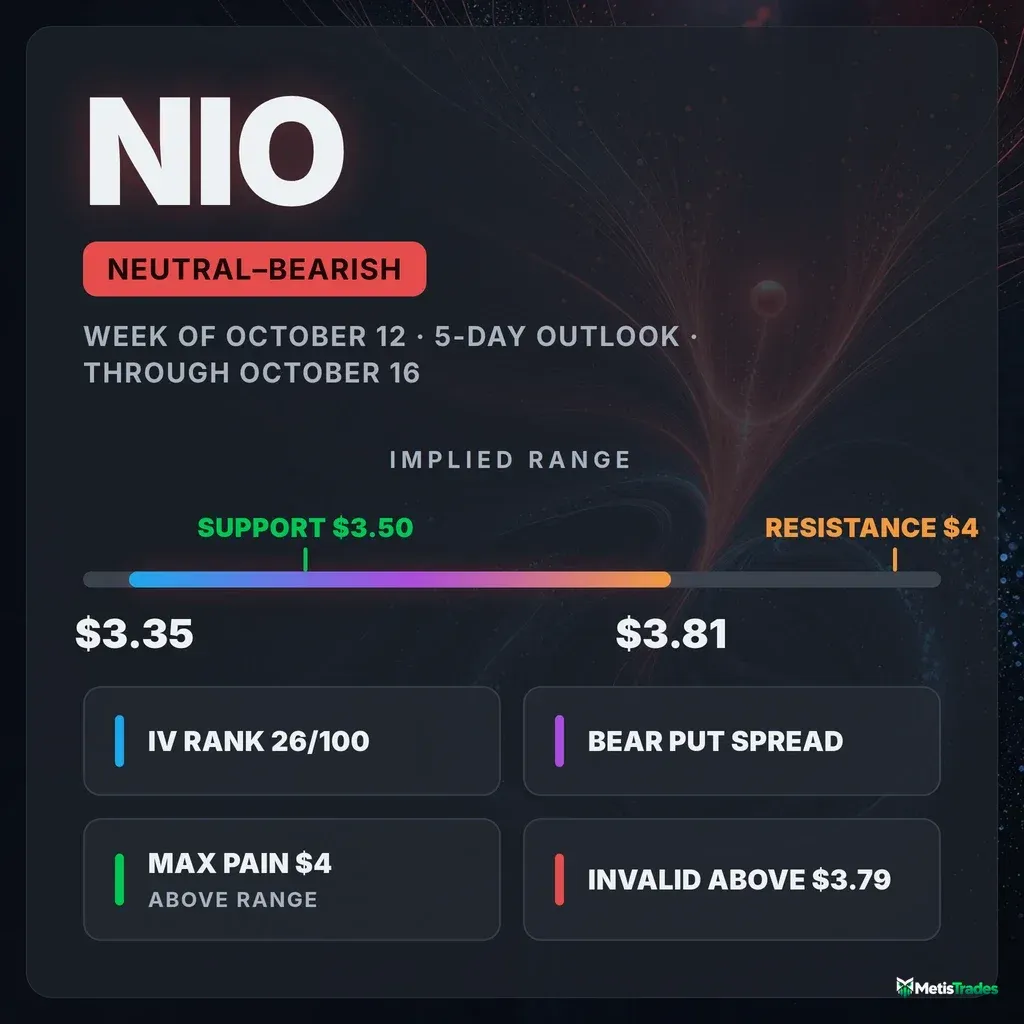
The options market implies a $3.35–$3.81 range into the October 16 expiration. Here is what drives the slightly bearish positioning lean, where the chart disagrees, and three defined-risk ways to trade it.
Published Sunday, October 11, 2026 · Data as of Friday, October 9, 2026 close
Explore the live NIO options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Slightly bearish |
| Options-implied range (into October 16) | $3.35 – $3.81 (±$0.23, ±6.30%) |
| Major support | $3.50, the heaviest near-spot gamma strike, with $3.55 swing support just above. Note that the October 16 put wall sits at $4.00, above the stock, so it is not a floor. |
| Major resistance | $4.00 (October 16 call wall); $3.79 swing resistance first |
| Max pain (October 16) | $4.00 |
| Dealer gamma regime (estimate) | Positive, so hedging tends to dampen moves; flip level ≈ $1 |
| Volatility condition | Neutral. IV rank 25.86/100 · premium fair: options priced ~12 vol pts above delivered movement |
| Technical check | Diverges (bullish; 3-day target $3.64, 5-day target $3.66) |
| Best-fitting strategy | October 16 $4/$3.50 bear put spread, sized small |
| Analysis invalidated if | NIO closes above $3.79 |
1 · What matters today
NIO closed Friday, October 9 at $3.58 after a 6% bounce over five sessions. The options market is not cheering. Our positioning read comes out slightly bearish. The main reason is that traders paid sharply more for downside puts as the stock rose, and put-buying ran heavier than this stock's recent norm.
Options are pricing a move of about $0.23 either way by the October 16 expiration, a range of roughly $3.35 to $3.81. That figure is "the expected move," derived from what straddles cost.
The level that changes the picture is $3.79. A close above it would mean buyers pushed through the nearest overhead resistance and the bearish lean is wrong.
Both chart-based technical models disagree with the options read. They point modestly higher, toward $3.64–$3.66, which is the central tension this week.
2 · What the options market is pricing
What changed this week
NIO rose 6.2% over the past five trading days, capped by Friday's gap up from a $3.41 prior close to a $3.49 open.
The options crowd hedged into that strength rather than chasing it:
- Put/call volume: Friday's ratio hit 0.43, meaning about 43 put contracts traded for every 100 calls. The 7-day average is 0.33 and the 14-day average is 0.24, so put activity roughly doubled its two-week pace.
- Open interest (contracts currently held open): The put/call OI ratio was flat at 0.72, against a 7-day average of 0.72. The hedging showed up in trading and pricing more than in new put inventory.
- Implied volatility: IV rose 3.6% over five sessions even as the stock climbed.
- Biggest single change: January 15, 2027 $3.50 calls added 5,603 contracts, bringing open interest to 29,034. That is longer-dated bullish money.
The short-term and long-term trend reads diverge. The past week's bounce runs against a stock that is still down about 3% over the past month and 26% over the past ~50 trading days. Near-term flow and the bigger trend point different ways, which argues for short-dated structures and quick profit-taking.
Into Friday's settled expiration, the October 9 $3.50 calls traded 12,976 contracts. That is now history.
Expected move
Into October 16, the options market prices a 1-standard-deviation move of ±6.30%, or about ±$0.23 around $3.58. That is "the move the options market is pricing in — derived from what straddles cost." Roughly two-thirds of the time, a move of that size or smaller would be consistent with today's pricing.
| Expiration | Implied move | Range around $3.58 |
|---|---|---|
| October 16 | ±6.30% | $3.35 – $3.81 |
| October 23 | ±8.15% | $3.29 – $3.87 |
| October 30 | ±10.88% | $3.19 – $3.97 |
| November 6 | ±13.05% | $3.11 – $4.05 |
The ladder widens smoothly with time. There is no single expiration where premium jumps, so the chain shows no scheduled-event bulge inside this window.
Volatility
At-the-money implied volatility is 46.52%. IV is "the market's estimate of how much NIO will move, baked into option prices."
IV rank is 25.86/100. IV rank shows "where today's IV sits versus the past year": 26/100 means cheaper than about 74% of the past year's readings. The IV percentile is even lower, about 5, meaning almost every day of the past year printed a higher IV than today.
Direction:
- IV dipped 2.1% on Friday.
- It is up 3.6% over five days and down 12.7% over 30 days.
- It sits below both its 30-day average (48.8%) and its 90-day average (54.4%).
- The term-structure comparison (comparing option prices across expiration dates) is unavailable today because of Friday's expiry.
Realized movement is speeding up. NIO's 10-day realized volatility is 46.7% against a 20-day reading of 34.7%. The ratio of short-window to month-long movement is running well above this stock's recent norm. That is a "vs its own norm" reading, meaning compared against NIO's own recent history rather than the broader market.
Premium rich or cheap? The volatility risk premium is "the gap between how much movement options are priced for and how much NIO has actually delivered." When it is positive, option sellers have been collecting more than realized movement cost them.
- Options are priced about 12 vol points above NIO's 20-day realized movement.
- That gap sits at the 31st percentile of this stock's own recent readings: richer than only about 31% of them. The gap is also running a bit narrower than usual for NIO.
- Over the past week the gap swung between roughly 9 and 19 points without changing sign.
IV rank in the mid-20s plus a premium only modestly above delivered movement adds up to fair, not rich. With 10-day realized movement already matching implied volatility, neither collecting nor owning premium has a clear edge. That favors small, defined-risk positions over aggressive premium selling.
Skew and sentiment
Skew means "puts and calls the same distance from the stock price don't cost the same — when puts are pricier, traders are paying up for crash protection."
NIO's 25-delta puts are quoting about 120 vol points over equivalent calls. The norm for this name over the past 60 days is near zero, the 7-day average is about 42 points, and five sessions ago the skew was far flatter.
Some of that magnitude reflects thin, wide-quoted put strikes on a sub-$4 stock, so treat the exact number loosely. The direction is unmistakable: downside protection got much more expensive while the stock rallied.
The put/call volume ratio measures "how much put activity there is relative to calls — above 1 means puts dominate." At 0.43, calls still outnumber puts in raw volume. However, put activity ran about 50% above its 60-day median of 0.28. Total options volume was 2.7× its 20-day average.
The flow is not one-sided:
- Call open interest grew by about 11,250 contracts on Friday while put OI shrank by about 720.
- Sentiment in the shortest-dated options (0–7 days) reads mildly positive.
- The 7–30 day window is slightly negative.
- The 30–60 day window leans clearly negative.
The overall sentiment regime across expirations is "Mixed." Our early-warning positioning read is built only from flow, skew and term structure. It swung from firmly positive on October 2 to firmly negative now, even as price rose. Option traders are using the bounce to buy protection.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| Whole-chain call wall | $7.00 | Largest call pile across all expirations, mostly long-dated; irrelevant in a 5-day window |
| 200-day moving average | $5.02 | Long-term trend line; NIO is 28.6% below it |
| Swing resistance cluster | $4.46 – $4.82 | Prior pivot highs from the downtrend |
| 50-day moving average | $4.04 | Medium-term trend line, 11.3% overhead |
| Call wall / put wall / max pain (October 16) | $4.00 | Heaviest call pile (34,149 contracts) and heaviest put pile (14,962, in-the-money) both sit here; also the whole chain's largest gamma strike |
| Top of implied range | $3.81 | Upper edge of the ±$0.23 expected move |
| Swing resistance | $3.79 | Nearest overhead pivot; the article's invalidation level |
| Spot (October 9 close) | $3.58 | Reference price |
| Swing support / 20-day MA | $3.55 | First cushion; the 20-day average sits at $3.55 as well |
| Near-spot gamma strike | $3.50 | Second-largest gamma strike in the chain and the at-the-money strike; primary support |
| October 9 gap origin | $3.41 | Prior close before Friday's gap; a gap-fill target if the bounce fades |
| Swing support / 52-week low | $3.37 / $3.36 | Year's floor |
| Bottom of implied range | $3.35 | Lower edge of the expected move |
| Whole-chain put wall | $2.00 | Largest put pile across all expirations, far below |
| Gamma flip (estimate) | ≈ $1 | One rough estimate puts it far below spot |
Positioning and unusual flow
Market makers hedge the options they have sold. One rough estimate says the October 16 expiration, like the chain overall, sits in a positive gamma regime, where their hedging tends to dampen moves. The gamma flip level is the price "below which market-maker hedging tends to accelerate selling rather than cushion it." It is estimated near $1, so spot is unusually far above it for this name. That leans toward contained, choppy trading rather than air pockets.
The October 16 chain is unusual: the call wall, the put wall and max pain all sit at $4.00. Max pain is "the price where the most option value would expire worthless — expirations sometimes gravitate toward it."
Max pain is 42 cents above spot and outside the implied range. With the stock at $3.58, the $4 calls are out of the money and the $4 puts are in the money. Treat $4.00 as a ceiling worth noting rather than a likely pin.
Three flow items stand out:
- October 16 $3.50 calls: 5,857 contracts traded, about 1.8× the existing open interest, which rose by 610 to 3,252. That is short-dated upside speculation right at the money.
- November 20 $4 puts: 12,010 contracts traded, roughly $607,000 in premium, the largest dollar flow in the chain. Open interest barely changed, so this looks like position turnover rather than fresh hedges.
- October 23 $3.50 calls: open interest grew by 842 contracts on 3,142 traded. Near-dated bulls are present; they simply were not alone this week.
3 · Technical check
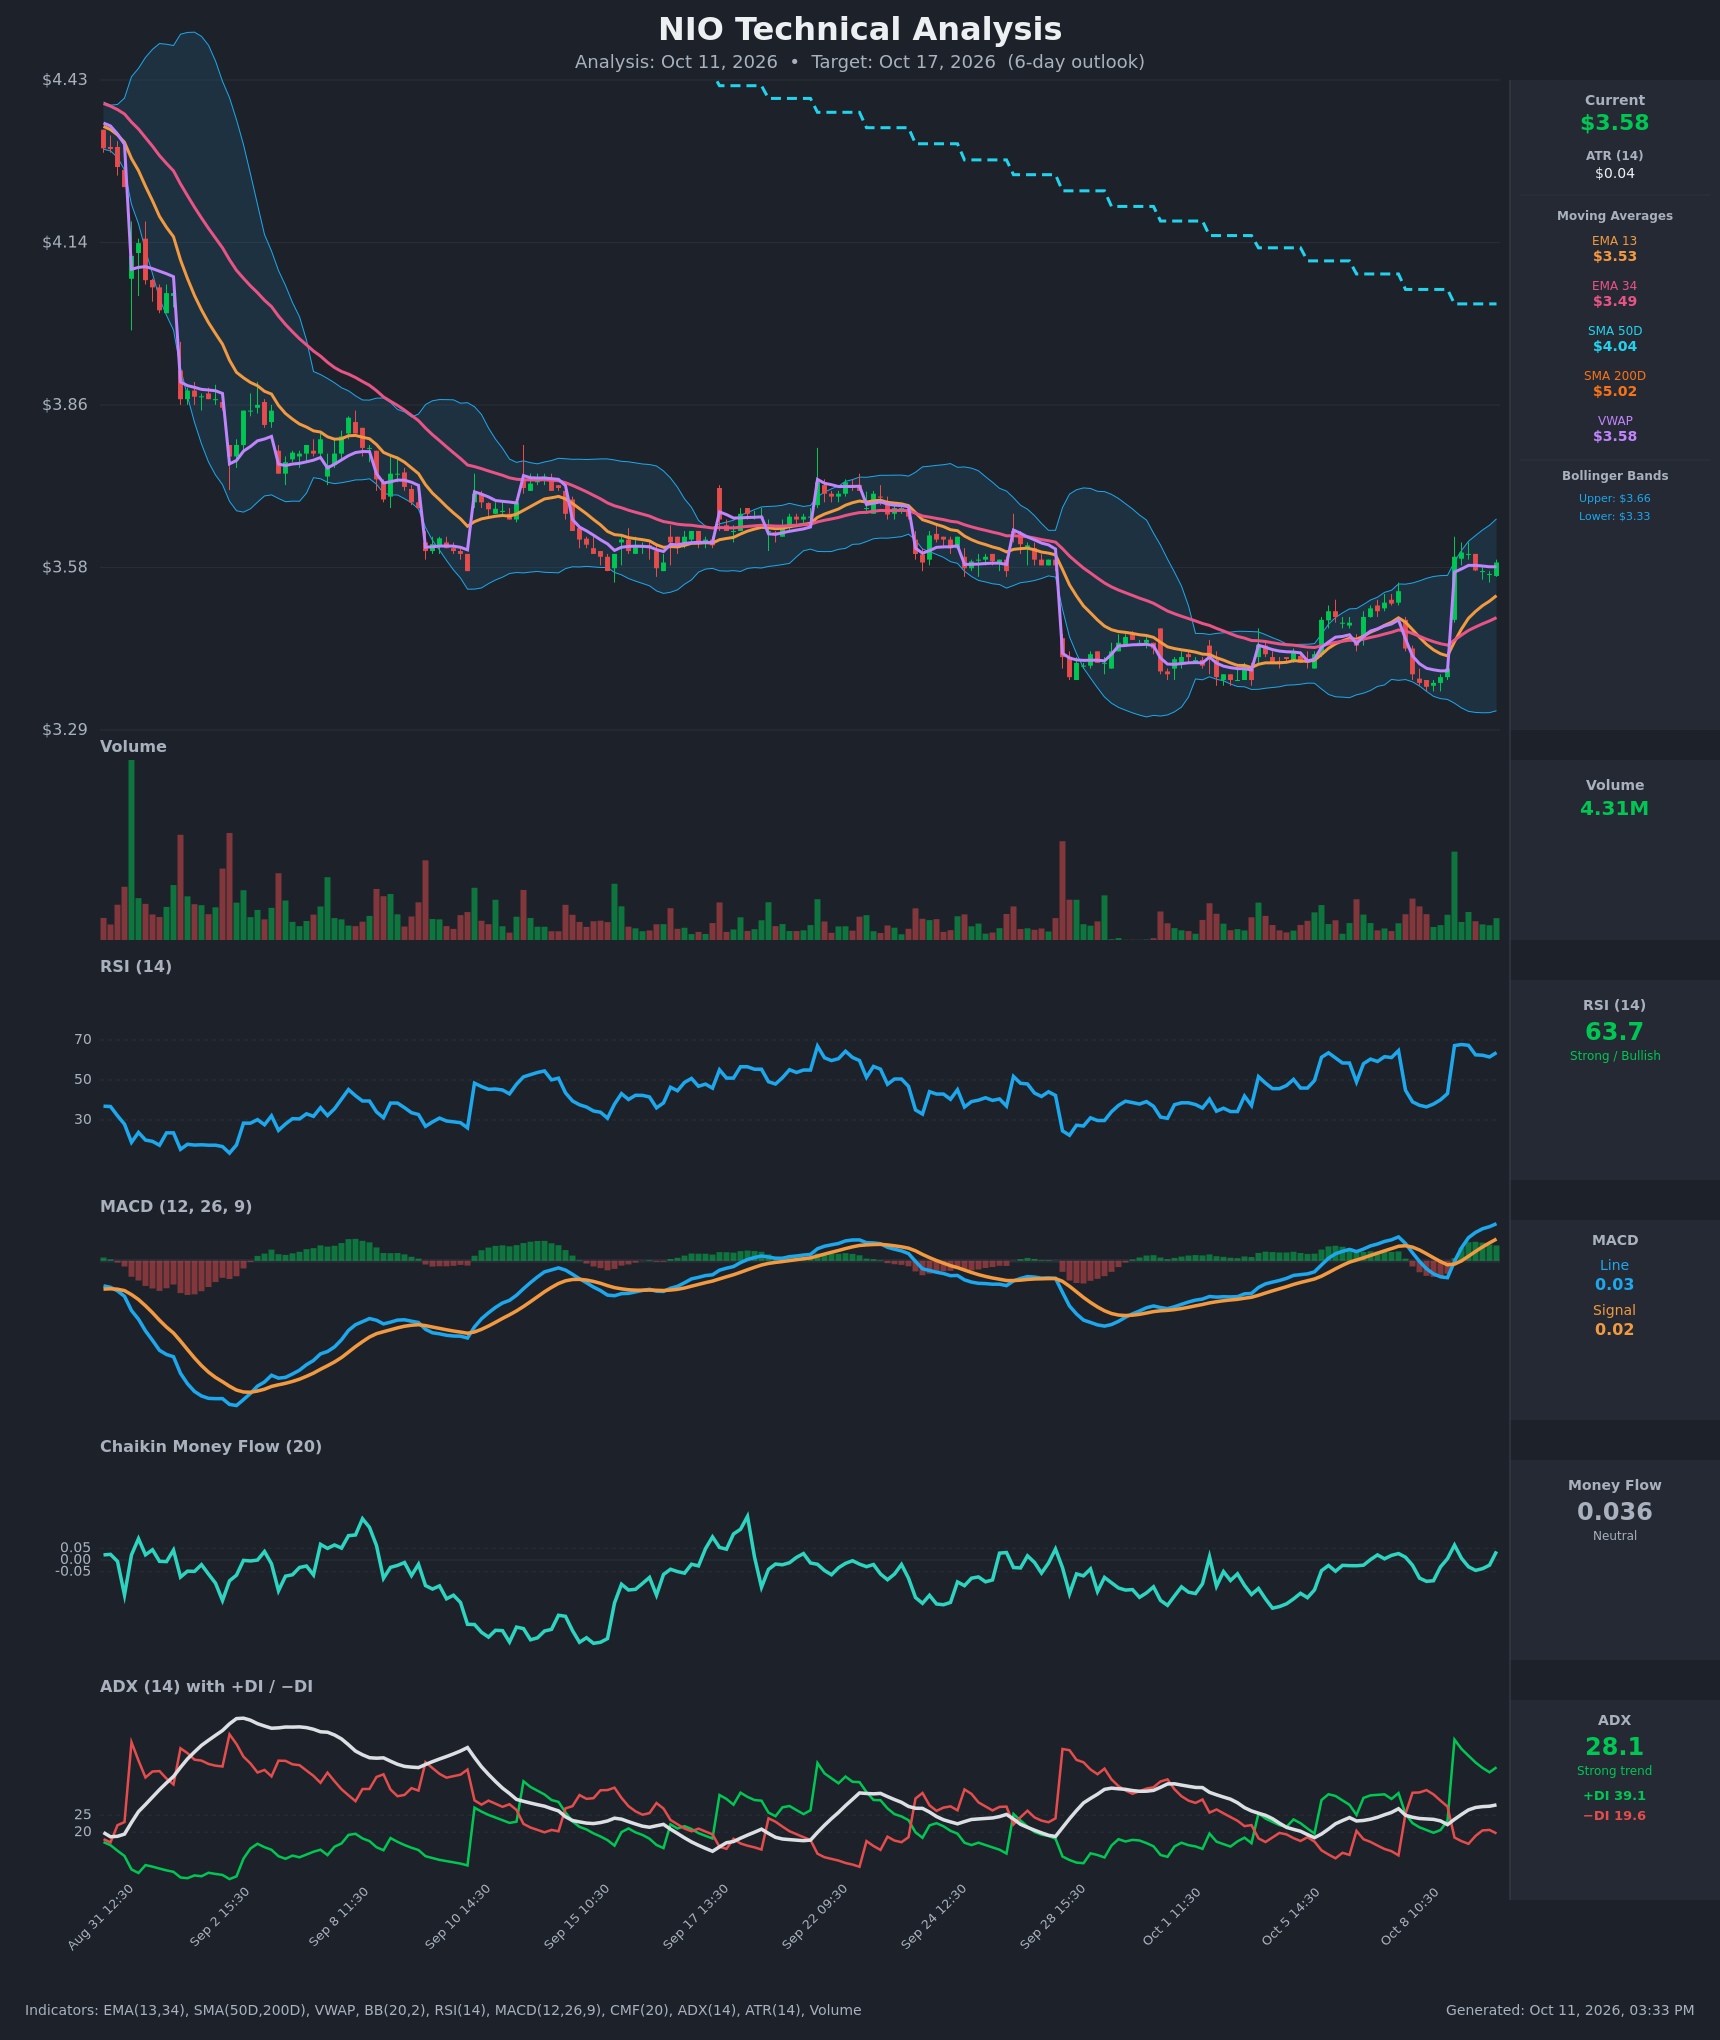
Both chart-model reports lean bullish, which diverges from the options read.
- 3-day report (checkpoint October 14): target $3.64, projected range $3.50–$3.68.
- 5-day report (ending October 16): target $3.66, projected range $3.47–$3.71.
Both targets sit inside the options-implied $3.35–$3.81 range. The disagreement is about direction, not size.
The chart case rests on fresh crossovers from Friday's gap. ADX is 28 and rising, with the positive directional line at 39 versus 20 on the negative side, which signals an emerging short-term uptrend. The weak spot is money flow: the 20-period Chaikin Money Flow sits at a neutral 0.036, so buying pressure isn't confirmed.
The chart's key levels are support at $3.53 and resistance at $3.66. Its dominant bullish scenario is invalidated on a close below $3.52.
Model vs. Market: The options market implies $3.35–$3.81 into October 16; the 5-day technical model targets $3.66. A close above $3.66 tips the argument toward the chart. Slipping back below $3.52 confirms what the skew and put-buying pace were hinting at.
The chart did shape strike selection. The bullish spread's break-even ($3.63) sits right at the technical targets, and the range structure's break-evens ($3.32–$3.68) bracket both projected ranges.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If NIO pushes toward the call wall ($4.00): First it has to clear $3.79 swing resistance and the $3.81 top of the implied range. The 34,149 open calls at $4.00 are the biggest overhead pile for this expiration, and heavy call open interest tends to slow rallies. Hitting it would also mean a move beyond what options price for the window.
If NIO drifts between $3.50 and $3.79: This is the dampened, positive-gamma case. Hedging flows around the large $3.50 gamma strike tend to absorb moves, and the stock chops inside the implied range into October 16. Max pain at $4.00 sits above this zone and is unlikely to pull price that far in five sessions.
If NIO breaks below $3.50: The October 9 gap origin at $3.41 and the 52-week low at $3.36 come into view, close to the $3.35 bottom of the expected move. With the gamma flip estimate near $1, one rough estimate suggests hedging still cushions rather than accelerates this decline. A slide toward the lows would likely be orderly, not a crash.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of October 9, 2026. All structures are hypothetical. Verify live prices before trading; these will be stale by the open.
On a sub-$4 stock, one or two cents of bid-ask spread is a large percentage of each option's price. Use limit orders at or near the midpoint, and expect to give up a penny or two.
If you lean bearish: October 16 bear put spread
- Trade: Buy the October 16 $4 put, sell the October 16 $3.50 put
- Debit: $0.365 ($36.50 per spread) · Max profit: $13.50 · Max loss: $36.50 · Break-even: $3.635
- Why it fits: It matches the slightly bearish lean from steepening skew and a heavy put-volume pace. The spread earns a small gain if NIO merely stays where it is, since it is worth about $0.42 at $3.58. Full profit comes below $3.50. You pay for the expensive downside without owning it outright.
- Makes sense only if: the October 9 bounce stalls under $3.66 and the hedging footprint in the chain persists.
- Invalidated if: NIO closes above $3.66.
- Managing it: Take profits at roughly 60–70% of max value. If NIO closes above $3.66, cut it rather than ride it to $4.00. Because short-term direction fights the longer downtrend, don't hold for the last penny.
- Liquidity note: The $4 puts traded $0.40/$0.43, 3¢ wide (about 7% of mid). The $3.50 puts traded $0.04/$0.06, only 2¢ wide but 40% of mid. Slippage is real here, so work the order.
- Analyze this position →
If you expect the range to hold: October 16 $3/$3.50/$4 call butterfly
- Trade: Buy one October 16 $3 call, sell two $3.50 calls, buy one $4 call
- Debit: $0.32 ($32) · Max profit: $18 (at $3.50) · Max loss: $32 · Break-evens: $3.32 and $3.68
- Why it fits: The positive-gamma estimate favors dampened movement. The $3.50 strike is the largest gamma concentration near spot. The profit zone covers most of the implied range and both technical projections. A butterfly is a debit, which suits fair rather than rich premium.
- Makes sense only if: NIO stays boxed between support near $3.50 and resistance at $3.79 through October 16.
- Invalidated if: NIO closes above $3.68 or below $3.32.
- Managing it: Butterflies gain most in the final days. Take 40–50% of max profit if NIO sits near $3.50 by the October 14 checkpoint, and close outright if either break-even is breached.
- Liquidity note: The $3 calls traded $0.57/$0.61 (4¢, about 7% of mid). The $3.50 calls traded $0.13/$0.15 (about 14%). The $4 calls quote a flat $0.01. Leg in carefully or use a single combo order.
- Analyze this position →
If you lean bullish: October 16 bull call spread
- Trade: Buy the October 16 $3.50 call, sell the October 16 $4 call
- Debit: $0.13 ($13 per spread) · Max profit: $37 (at $4.00 or above) · Max loss: $13 · Break-even: $3.63
- Why it fits: This is the chart's side of the argument. The break-even sits at the technical targets of $3.64–$3.66, max profit lands at the $4.00 call wall and max pain, and the cost is small. Heavy call buying in the $3.50 strike shows near-term bulls are active.
- Makes sense only if: NIO clears the $3.60–$3.62 consolidation top early in the week, as the technical reports describe.
- Invalidated if: NIO closes below $3.50.
- Managing it: Take half off on a move through $3.79. Because this fights the longer downtrend, take profits early and exit by the October 14 checkpoint if NIO hasn't cleared $3.66.
- Liquidity note: The $3.50 calls traded $0.13/$0.15 (2¢, about 14% of mid). The $4 calls quote a flat $0.01. Fills are workable at mid but not free.
- Analyze this position →
If none of these: no trade
Standing aside is a reasonable call this week:
- The bearish lean is only slight.
- Positioning and the chart point opposite ways.
- Premium is fair rather than rich, so sellers have no cushion.
- The October 16 strikes sit a coarse 50 cents apart, so every structure carries percentage-heavy bid-ask costs.
If you can't tolerate giving up a few cents per spread to slippage, wait. A decisive close above $3.66 or below $3.52 will resolve the Model vs. Market question and make the next setup cleaner.
6 · Quick FAQ
What is NIO's expected move this week? About ±$0.23 (±6.30%) into the October 16 expiration, a $3.35–$3.81 range, per straddle pricing as of October 9.
Is NIO expected to go up or down over the next week? Options positioning as of October 9 leans slightly bearish, because traders paid up sharply for puts during the bounce. That is a read of what traders have done, not a forecast. The actionable map is the $3.35–$3.81 range, with $3.50 support and $4.00 resistance.
Are NIO options expensive right now? IV rank of 25.86/100 says option prices are lower than about 74% of the past year's readings. On top of that, options are running about 12 vol points above the movement NIO has actually delivered, richer than only about 31% of this stock's recent readings. Premium is fair, not rich.
Where is NIO's biggest options support and resistance? For October 16, the call wall, put wall and max pain all sit at $4.00, with the put pile in the money above the stock. Practical support is the $3.50 strike, and $3.79 is the nearest swing resistance.
What invalidates this week's read? A close above $3.79.
Methodology & disclosures. Data: end-of-day options-chain snapshot for NIO, 2026-10-09, generated 2026-10-11T15:33:05Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.