NIO Options Outlook: Will the $3.50 Put Wall Hold Into September 25?
The options market is pricing NIO in a $3.44–$3.88 band into the September 25 expiration, with the heaviest call open interest capping at $4.00 and the put wall parked at $3.50. Here's what the positioning says, where the chart model disagrees, and three defined-risk ways to trade a compressed tape.
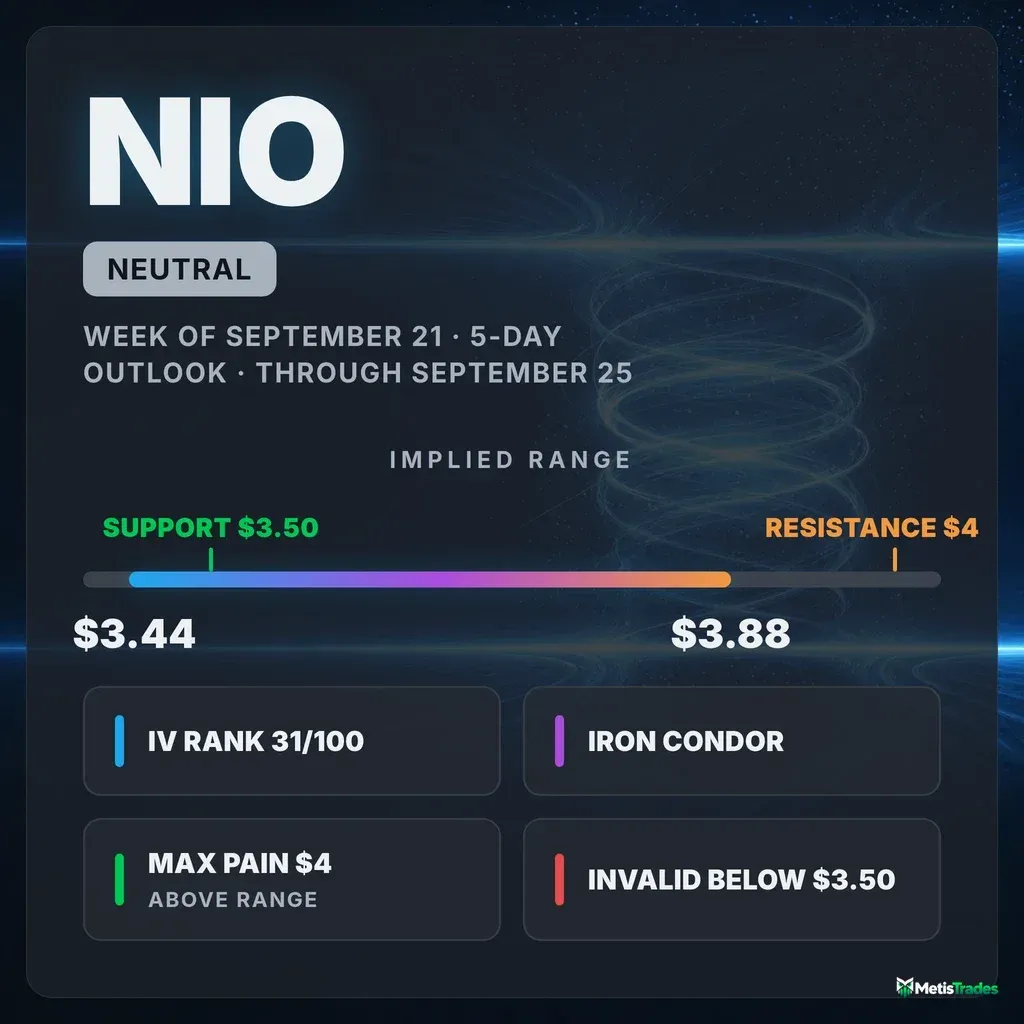
The options market implies a $3.44–$3.88 range into the September 25 expiration; here's what's driving it and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18 close
Explore the live NIO options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral |
| Options-implied range (into September 25) | $3.44 – $3.88 (±6.03%, about ±$0.22) |
| Major support | $3.50 (put wall, September 25 expiration) |
| Major resistance | $4.00 (call wall, September 25 expiration) |
| Max pain (September 25) | $4.00 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $1.50 (estimate) |
| Volatility condition | Rising — IV rank 31/100 · premium moderately rich: options priced about 18 vol points above delivered movement |
| Technical check | Mixed (bullish, 3-day and 5-day chart models) |
| Best-fitting strategy | Iron condor — conditional, and only if the payout ratio is acceptable to you (see Section 5) |
| Analysis invalidated if | NIO closes below $3.50 |
1 · What matters today
NIO closed Friday, September 18 at $3.66, and the options market is pricing roughly $0.22 of movement up or down — a $3.44 to $3.88 band — through the September 25 expiration. That figure comes from what straddles cost: it's the move the options market is pricing in, not a forecast. Our read of the flow lands squarely neutral: leading positioning is flat, short-dated sentiment leans mildly positive, and momentum leans mildly negative. They cancel.
The map that matters is simple. The heaviest pile of open put contracts for that expiration sits at $3.50 — the single level that has held this stock up for a week. The heaviest call open interest sits at $4.00, which is also where the most option value would expire worthless. Both chart models we checked lean bullish but land inside the options range. A close below $3.50 breaks the whole picture.
2 · What the options market is pricing
What changed this week
Price barely moved: NIO is down 0.81% over the past five sessions after falling 19.2% over the prior month. Volatility, however, woke up. The market's estimate of how much NIO will move — implied volatility baked into option prices — rose 5.7% in a single session and 23.2% over five, lifting the 52-week IV rank to 31/100 against a 7-day average of 21 and a 14-day average of 16. Options got more expensive while the stock stood still.
Flow was lopsided and thin. Total option volume ran at just 0.56× its 20-day average, and put volume came in at 2,525 contracts against 32,383 calls — a put/call volume ratio of 0.08 versus a 7-day average of 0.20. For every 100 calls traded Friday, only eight puts changed hands, an unusually call-tilted session even by this name's own standards. Open interest tells the opposite story: the put/call open-interest ratio now sits at 0.67 (67 puts held open for every 100 calls) against a 14-day average of 0.41 — though part of that jump reflects a broadening of the covered chain mid-week rather than fresh hedging alone, so treat the magnitude, not the direction, with care.
The single biggest live change in contracts held open was the November 20 $3 put, which added 1,014 contracts. Closer in, the October 2 $4 calls traded 4,397 contracts and grew open interest by 859 — $15,389 of premium chasing a strike 9% above spot. Into Friday's now-settled expiration, the $4 puts shed 1,445 contracts of open interest as they expired in the money; that's history, not a live level.
One tension worth naming: the short-, medium- and long-term trend reads all point the same way, and it isn't up. The past week is effectively flat, but NIO is down 19.2% over roughly 20 sessions and 23.4% over roughly 50. The stabilization is real; the backdrop it's stabilizing inside is a firmly broken tape.
Expected move
Into September 25, the options market is pricing about ±$0.22, or ±6.03%, around the $3.66 close — a $3.44 to $3.88 band. Here's how that scales out the curve:
| Expiration | Implied move | Range around $3.66 |
|---|---|---|
| September 25 | ±6.03% | $3.44 – $3.88 |
| October 2 | ±9.16% | $3.32 – $4.00 |
| October 9 | ±11.08% | $3.25 – $4.07 |
| October 16 | ±13.86% | $3.15 – $4.17 |
The ladder widens smoothly with time, with no kink or step-up between rungs — there is no event bulge priced into any single date here. (The October 30 rung is skipped: quote quality on that expiration was too poor to price it.)
Volatility
Chain-wide at-the-money implied volatility sits at 56.9%. IV rank is 31/100 — meaning today's reading is cheaper than about 69% of the past year's readings — with an IV percentile of 27.8. Direction is up: IV is 5.7% higher on the day, 23.2% higher over five sessions, and now sits above its 30-day average of 54.1% while still just under its 90-day average of 57.8%. The front-month read is unavailable today (Friday was an expiry day, so the nearest-expiration ATM volatility can't be interpolated), which also means the comparison of near-dated to longer-dated option prices is off the table for this snapshot.
Worth noting: the September 25 rung itself prices an ATM volatility of only 43.5%, well below the chain-wide 56.9%. The expensive part of this curve lives 30 to 60 days out, not in the front week. Meanwhile, NIO's actual delivered movement has been decelerating hard — the 5-day realized-volatility pace is running at about half the 20-day pace, an unusually depressed reading versus this stock's own recent history, even as the 20-day measure itself (38.8%) sits about where it normally does.
Premium rich or cheap. The gap between how much movement options are priced for and how much NIO has actually delivered — the volatility risk premium — stands at roughly 18 vol points. That's the level where option sellers have historically been collecting more than realized movement cost them. Where does it sit versus this stock's own recent readings? Around the 60th percentile: richer than about 60% of them. The gap has also widened steadily over the past week, climbing from about 7 vol points on September 11 to 18 today, with no sign flip. That combination — IV rank 31 and a 60th-percentile premium over delivered movement — tilts mildly toward collecting premium rather than owning it, but only mildly, and the caveat in the paragraph above matters: the richness is concentrated in the 30-to-60-day part of the curve, not in the seven-day tenor this article is built around.
Skew and sentiment
Puts and calls the same distance from the stock price don't cost the same, and in NIO they currently favor the upside: 25-delta calls carry an implied volatility of 85.0% against 79.5% for 25-delta puts — calls are about 5.5 vol points more expensive than equidistant puts. That is almost exactly this name's own 60-day median (also about 5.5 vol points). Traders are paying up for upside optionality, and they are doing so at a perfectly normal intensity for this stock. The caution is that this measure has been whipsawing violently in recent weeks, so read it as "at its norm today," not "settled."
Volume sentiment is loud and one-sided: put/call volume at 0.08 is 72% below its 60-day median, one of the more call-tilted sessions this name has printed relative to its own history. Open-interest sentiment across expirations is the mirror image, with the put/call OI ratio building at an unusual clip. Short-dated directional lean is mildly positive — the 0-to-7-day bucket scores +13 and the 7-to-30-day bucket +1 — and the overall regime summary reads "broadly bullish," though the front bucket is running below its 7-day average of +22. Net: chase in the volume, hedging in the inventory.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $8.02 | NIO sits 54.4% below it — context, not a level in play |
| Whole-chain heaviest call strike | $7.00 | 221,201 contracts held open, overwhelmingly in the January 2027 expiration — not a near-term ceiling |
| 200-day moving average | $5.13 | Price is 28.6% below it — the long-term trend is broken |
| 50-day moving average | $4.42 | Price is 17.1% below it |
| Call wall (September 25) / max pain / largest gamma strike | $4.00 | Heaviest call open interest for the week (8,393) and where the most option value expires worthless; also the single biggest gamma strike chain-wide |
| 20-day moving average | $3.96 | Price is 7.6% below it — first real trend hurdle |
| Top of implied range | $3.88 | Upper rail of the options-implied band into September 25 |
| Chart-model resistance | $3.80 | Both technical reports name it as the resistance shelf |
| Swing resistance | $3.79 | Nearest heuristic swing-pivot cluster (estimate) |
| Spot / last close | $3.66 | Friday, September 18 close |
| Chart-model support | $3.58 | Both technical reports' first support and their invalidation zone |
| Swing support / 52-week low | $3.55 | The floor of the past week's base; price is only 3.1% above the 52-week low |
| Put wall (September 25) | $3.50 | Heaviest put open interest for the week (5,298) — the level this article's thesis rests on |
| Bottom of implied range | $3.44 | Lower rail of the options-implied band |
| Whole-chain heaviest put strike | $2.00 | 188,292 contracts, concentrated in far-dated tenors — not a weekly level |
| Gamma flip estimate | ≈ $1.50 | One rough estimate of where market-maker hedging would flip from dampening to amplifying — far below spot |
Note the disagreement, because it matters: the September 25 expiration's own walls are $4.00 (calls) and $3.50 (puts). The whole chain combined puts them at $7.00 and $2.00, driven almost entirely by January 2027 positioning. For this week, use $4.00 and $3.50.
Positioning and unusual flow
The dealer-positioning estimate reads positive for both the full chain and the September 25 expiration specifically: under the model's assumed sign convention, market makers hedging their book would tend to dampen moves rather than amplify them, with the flip level estimated far below at around $1.50. That is an estimate built on an assumed dealer inventory, not observed inventory — but it does fit what the tape has actually done: a week of $3.55-to-$3.70 chop.
Three live flow items stood out. The September 25 $3.50 calls traded 1,147 contracts against 1,481 held open — $22,367 of premium, the biggest dollar print in the target expiration, on a strike that is already in the money and sits right on the put wall. The October 2 $4.00 calls traded 4,397 contracts and added 859 to open interest, $15,389 of premium betting on a move to the call wall two weeks out. And on the other side, the October 30 $4.00 puts turned over 319 contracts against just 182 held open — a turnover ratio of 1.75, small in absolute size but the most lopsided put activity in the file.
3 · Technical check
Both chart models lean the same way. The 3-day report targets $3.72 with a projected range of $3.57 to $3.76; the 5-day report, which lands on the same September 25 date this article is built around, targets $3.76 with a projected range of $3.55 to $3.80. Both cite the same evidence: a MACD line crossing above its signal for the first time since the early-September collapse, RSI climbing off the low 30s to 55, and short-term directional strength (+DI at 29.3 versus −DI at 14.9) favoring buyers. Both also flag the same warning — money flow (CMF at −0.115) has stayed in distribution territory through the entire bounce, and trend strength (ADX 20.9) is below the threshold that would confirm a real trend.
Classification: mixed. The direction diverges from our neutral options read, but the magnitude confirms it — the 5-day model's $3.80 upper projection sits comfortably inside the options-implied $3.88 ceiling, and its $3.55 lower bound sits inside the $3.44 floor. In other words, the chart says "lean up," the options say "don't go far," and both agree the week stays in a narrow box. The 5-day report's own invalidation for its dominant scenario is a close back below $3.60.
Model vs. Market: The options market implies $3.44–$3.88 into September 25; the 5-day technical model targets $3.76. The chart's bullish case fits entirely inside the options-implied band — which means a reader who believes the technicals doesn't need to bet on a breakout, only on the upper half of the same range.
That's how the technicals adjusted strike selection below: the bullish structure is built to $4.00, the call wall, rather than anything above it, and the neutral structure's upper rail also sits at $4.00 rather than being shaded lower.
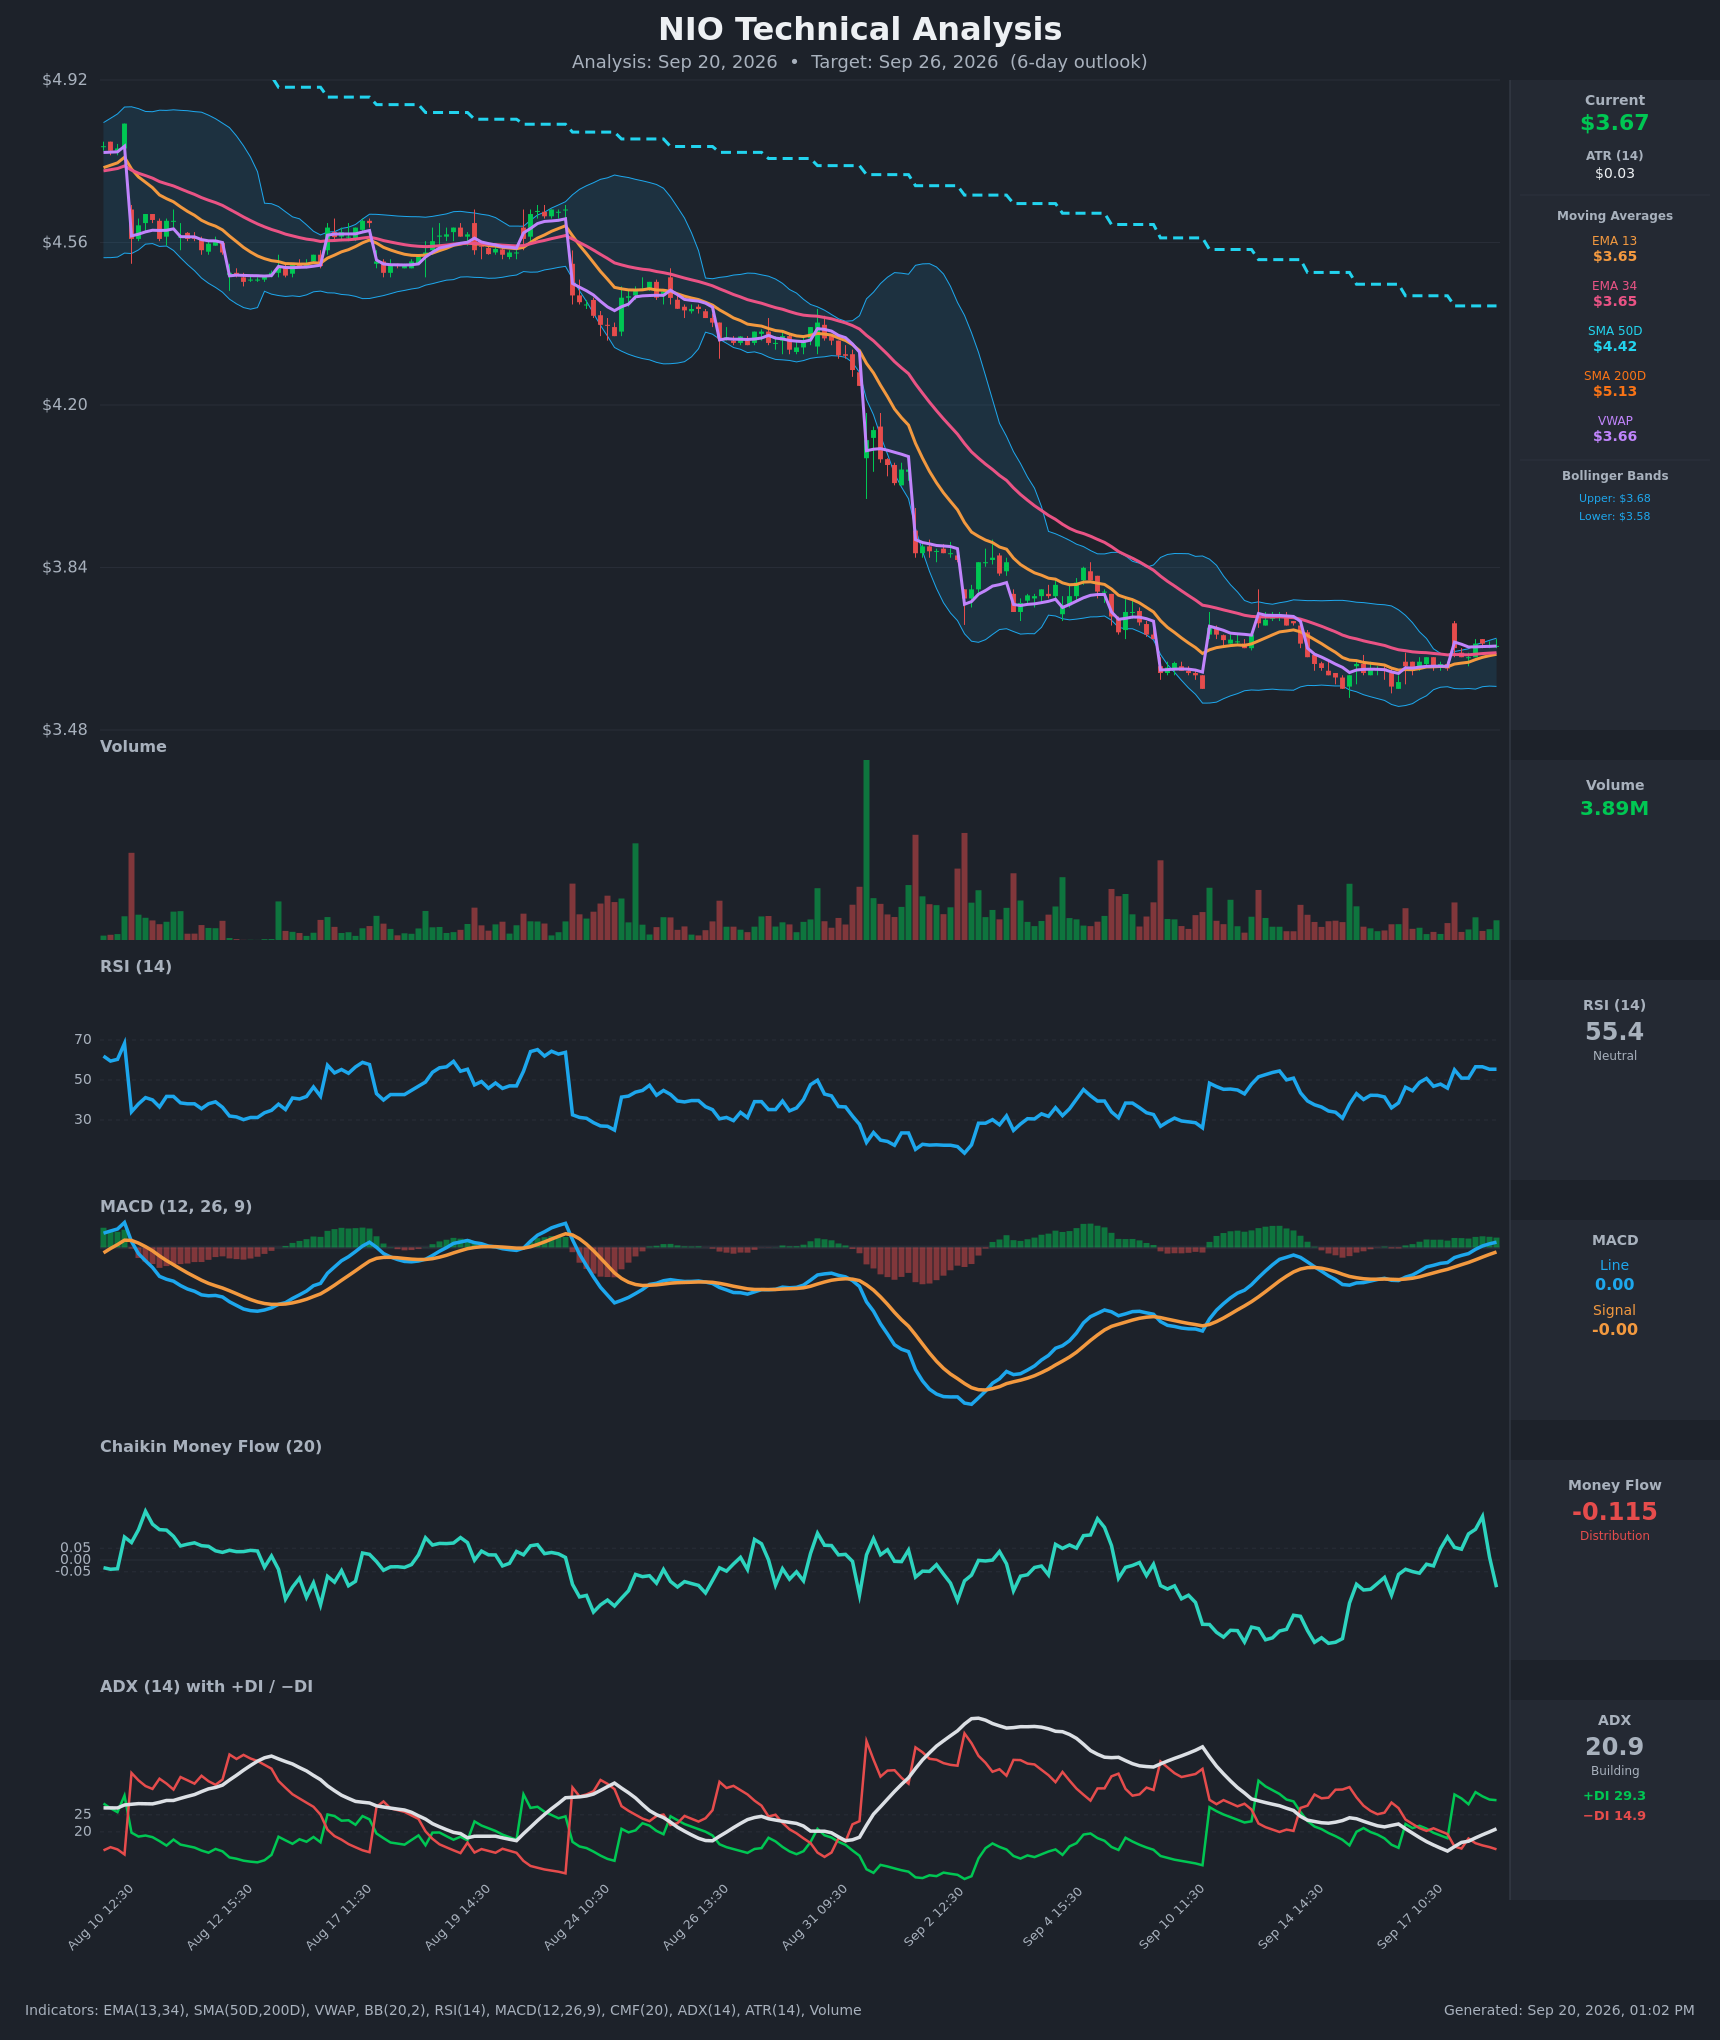
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If NIO pushes above the call wall ($4.00): That is where the heaviest call open interest for the week sits and also where the most option value would expire worthless, so positioning tends to slow rallies into it rather than through it. A clean break above would also clear the 20-day moving average at $3.96 and leave thin weekly positioning overhead until the 50-day average near $4.42 — but that requires a 9% move in five sessions, well outside what the options are pricing.
If NIO drifts between the walls: This is the base case the positioning describes. Max pain for the expiration is $4.00, above spot and above the top of the implied range — a pull, not a magnet, and one the price would have to fight the implied move to reach. With the dealer-hedging estimate reading positive, hedging flows have been the kind that damp rather than extend moves, which is consistent with the $3.55-to-$3.70 chop of the past week continuing.
If NIO breaks below the put wall ($3.50): That level carries 5,298 contracts of put open interest for the week and sits just under the $3.55 swing low and 52-week low. Below it, the nearest structural reference in this file is the bottom of the implied range at $3.44 and then open air — there is no meaningful weekly put positioning between there and $3.00. Spot sits far above the gamma flip estimate (~$1.50), so the mechanical acceleration case isn't in play here; the risk is simply that the base breaks and there is nothing priced beneath it.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of September 18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you expect the range to hold: iron condor
- Trade: Sell the September 25 $3.50/$3.00 put spread and the $4.00/$4.50 call spread
- Credit: $0.025 ($2.50 per condor) · Max profit: $2.50 · Max loss: $47.50 · Break-evens: $3.475 and $4.025
- Why it fits: Both short strikes are the expiration's own walls, the implied range ($3.44–$3.88) sits entirely inside them, and the dealer-hedging estimate is in the move-dampening regime. A credit spread means you collect premium up front and win if price stays between the short strikes.
- Makes sense only if: you accept a genuinely poor payout ratio. Collecting $2.50 against $47.50 of risk is about five cents on the dollar — at $3.66 with 50-cent strike spacing, seven-day premium simply isn't there. This is the structure that matches the bias, not the structure that pays for it.
- Invalidated if: NIO closes below $3.50 or above $4.00
- Managing it: there is no meaningful 50%-of-credit exit at this size — either hold to expiration or close the tested side the moment a short strike is breached. Use the September 23 midpoint as a hard check-in.
- Liquidity note: the $3.50 puts are quoted 1¢ wide ($0.02 × $0.03) and the $3.50 calls 1¢ wide on a $0.195 mid, but the $3.00 puts show no bid and the $4.00 calls are 1¢ wide on a $0.015 mid — in percentage terms both wings are extremely wide, and slippage can eat the entire credit. Work the legs or skip it.
- Analyze this position →
If you lean bullish: $3.50/$4.00 call debit spread
- Trade: Buy the September 25 $3.50 call, sell the September 25 $4.00 call
- Debit: $0.18 ($18 per spread) · Max profit: $32 · Max loss: $18 · Break-even: $3.68
- Why it fits: a debit spread means you pay up front and win if price rises past your break-even. The break-even at $3.68 is two cents above spot, the maximum payout sits exactly at the call wall and max-pain strike ($4.00), and both chart models target $3.72–$3.76 — above break-even, below the cap. The September 25 rung also prices the cheapest volatility on the curve (43.5% ATM), so you're buying the least-inflated tenor.
- Makes sense only if: you believe the chart models' bullish crossover over the neutral options read, and you're content with a structure that needs price merely to hold, not to break out.
- Invalidated if: NIO closes below $3.58 (both technical reports' support and the 5-day model's own invalidation zone)
- Managing it: take profit if NIO trades to $3.88, the top of the implied range — the last 12 cents of payout requires a move the options aren't pricing. Given the short-term bounce is fighting a trend that's down 23% over 50 sessions, take profits early rather than pressing; exit regardless by the September 23 checkpoint if price is still under $3.66.
- Liquidity note: the $3.50 calls traded $22,367 of premium Friday and are quoted 1¢ wide ($0.19 × $0.20), roughly 5% of mid — easy fills. The short $4.00 call is 1¢ wide but on a 1.5¢ mid; expect to give up a penny there.
- Analyze this position →
If you lean bearish: $3.50/$3.00 put debit spread
- Trade: Buy the September 25 $3.50 put, sell the September 25 $3.00 put
- Debit: $0.02 ($2 per spread) · Max profit: $48 · Max loss: $2 · Break-even: $3.48
- Why it fits: this is a lottery ticket on the one event that would break the whole week's structure — a close through the $3.50 put wall and the $3.55 52-week-low shelf. The trend reads are bearish over 20 and 50 sessions, and the put/call open-interest ratio has been climbing hard. Risk is $2 per spread; that is the entire downside.
- Makes sense only if: you size it as insurance rather than a position. The $3.50 put carries roughly a 21% delta and the $3.00 put about 3% — the odds of a full payout are small and the odds of total loss are large.
- Invalidated if: NIO closes above $3.80, the resistance shelf both chart models name
- Managing it: at $2 of risk there is nothing to manage on the downside; if NIO trades to $3.44 (the bottom of the implied range), close and bank it rather than holding for the full $48.
- Liquidity note: the $3.50 puts are 1¢ wide ($0.02 × $0.03) — that's 40% of mid, and it means your $2 entry could easily become $3. The short $3.00 put shows no bid at all; if you can't sell it for a penny, buy the $3.50 put outright and accept the slightly higher cost.
- Analyze this position →
If none of these: no trade
Standing aside is a defensible call here, and the reason is specific. The gap between priced-in and delivered movement is genuinely positive — about 18 vol points, richer than roughly 60% of this stock's own recent readings — which normally argues for selling premium. But that richness lives in the 30-to-60-day part of the curve, not in the seven-day tenor this outlook covers, where ATM volatility prints just 43.5%. Combine that with 50-cent strike spacing on a $3.66 stock and the arithmetic collapses: the best defined-risk credit available into September 25 pays $2.50 against $47.50 of risk, before slippage on quotes that are 40% to 67% of mid. You are not being paid for the premium that looks rich on the surface. If you want to sell NIO volatility, the October 16 through November 20 expirations are where the data says the premium actually sits — and that's a different article. For the next five days, no position beats a bad one.
6 · Quick FAQ
What is NIO's expected move this week? About ±$0.22, or ±6.03%, into the September 25 expiration — a $3.44 to $3.88 range around the $3.66 close, per the options market's straddle pricing as of September 18.
Is NIO expected to go up or down over the next five days? Options positioning as of September 18 reads neutral — leading positioning is flat, short-dated sentiment leans mildly bullish, and momentum leans mildly bearish, and they offset. That's a read of what traders have done, not a forecast. The actionable map is the $3.44–$3.88 range and the $3.50 / $4.00 levels.
Are NIO options expensive right now? Two lenses. IV rank of 31/100 says option prices are lower than 69% of the past year's readings. On top of that, they're running about 18 vol points above the movement NIO has actually delivered — richer than roughly 60% of this stock's own recent readings. The verdict: moderately rich overall, but the richness is concentrated 30 to 60 days out, not in the September 25 week, where ATM volatility prints only 43.5%.
Where is NIO's biggest options support and resistance? For the September 25 expiration, the put wall is $3.50 (5,298 contracts of open interest) and the call wall is $4.00 (8,393 contracts). The combined-chain figures of $2.00 and $7.00 are driven by January 2027 positioning and are not this week's levels.
What invalidates this week's read? A close below $3.50. That breaks the put wall and the $3.55 52-week-low shelf together, and the file shows no meaningful weekly put positioning beneath it.
Methodology & disclosures. Data: end-of-day options-chain snapshot for NIO, 2026-09-18, generated 2026-09-20T13:02:28.438Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.