PFE Options Are Pricing a $0.71 Move Into September 25 — Our Read Leans the Other Way From the Chart
Pfizer's options market implies a $26.95–$28.37 range through the September 25 expiration, with max pain at $27.50 and a call wall at $28.50. Our positioning read comes out neutral with a bearish tilt — while both chart models point modestly higher, which makes this week's setup interesting.
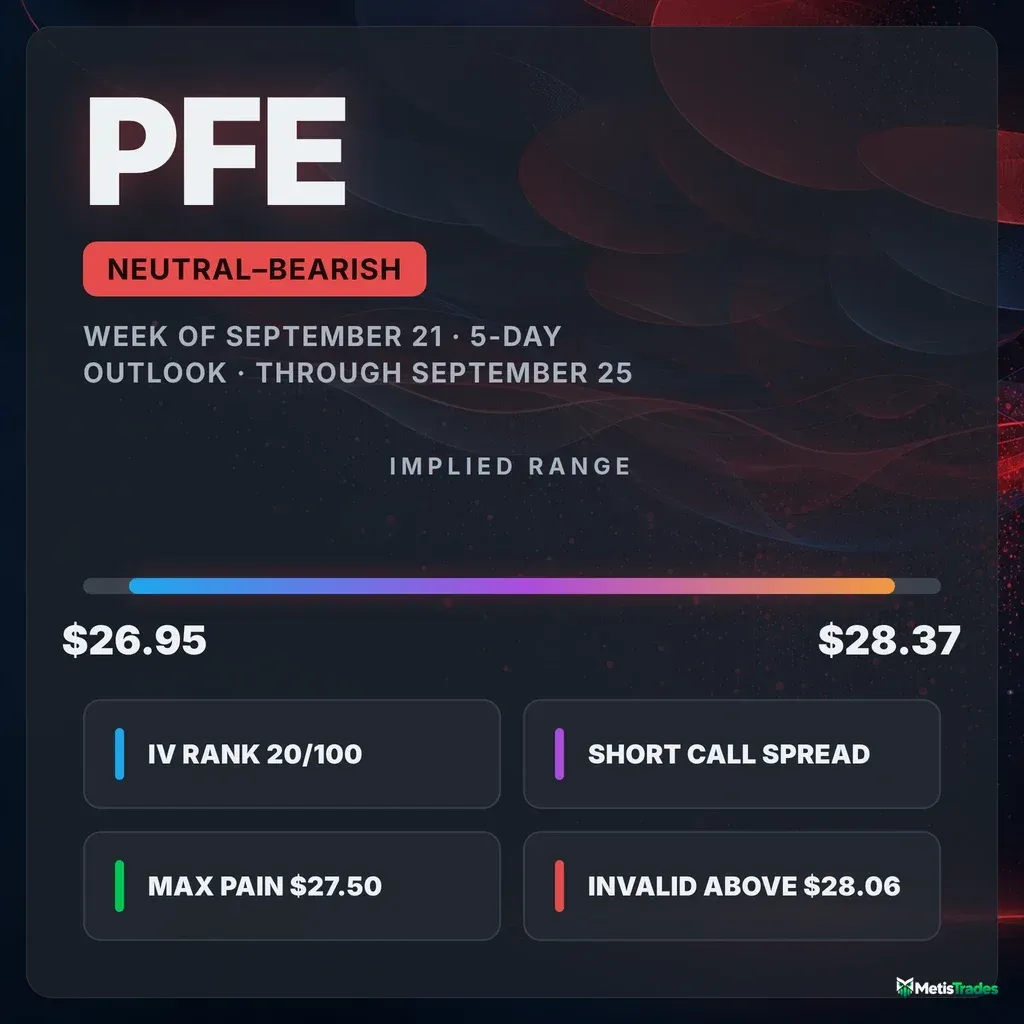
The options market implies a $26.95–$28.37 range into the September 25 expiration; here's what's driving it, where the walls sit, and three defined-risk ways to trade it.
Published Sunday, September 20, 2026 · Data as of Friday, September 18 close
Explore the live PFE options data in the Detailed Options Analyzer →
Quick answer
| Item | Answer |
|---|---|
| Market bias | Neutral with a bearish tilt |
| Options-implied range (into September 25) | $26.95 – $28.37 (±2.58%, about ±$0.71) |
| Major support | $25.00 (September 25 put wall) |
| Major resistance | $28.50 (September 25 call wall) |
| Max pain (September 25) | $27.50 |
| Dealer gamma regime (estimate) | Positive — hedging tends to dampen moves; flip level ≈ $28.00 |
| Volatility condition | Falling — IV rank 19.6/100 · premium rich: options priced about 3.7 vol points above delivered movement |
| Technical check | Diverges (bullish, 3-day and 5-day chart models) |
| Best-fitting strategy | Short call spread just above the max-pain zone (credit) |
| Analysis invalidated if | PFE closes above $28.06 |
1 · What matters today
Pfizer closed Friday, September 18 at $27.66 after going almost nowhere for a week — down 0.22% over five sessions. The options market is pricing a move of about $0.71 in either direction through the September 25 expiration, which frames a $26.95–$28.37 range. Inside that range, the most-owned call strike for that expiration sits at $28.50 and max pain — the price where the largest pile of option value expires worthless — sits at $27.50, just under spot.
Our read of the flow comes out neutral with a slight bearish tilt: put open interest has been building faster than call open interest, and spot is parked in the upper half of the week's wall corridor with more room below it than above. Both chart models disagree and point modestly higher. The level that settles it: a close above $28.06 would reclaim the 20-day average and put the $28.50 wall in play.
2 · What the options market is pricing
What changed this week
The story of the week is compression, not direction. The stock moved 0.22% over five sessions and 0.47% over twenty, while at-the-money implied volatility — the market's estimate of how much PFE will move, baked into option prices — fell 3.7% on Friday alone and 2.4% over five sessions, to 20.91%. That reading sits below both its 30-day average (21.25%) and its 90-day average (22.40%), and the 52-week IV rank of 19.6 compares with a 7-day average of 26.4 and a 14-day average of 27.1. Option prices have been leaking lower all week.
Underneath the quiet, positioning shifted put-side. The put/call open-interest ratio — how many put contracts are held open for every call — went from 0.68 to 0.75 over five sessions, an 11% build, against a 7-day average of 0.70. Put/call volume printed 0.45 on Friday versus a 7-day average of 0.33: still call-dominated, but the most put-heavy session of the past week. Compared against this stock's own recent history, the pace at which puts are being added relative to calls is unusually heavy for PFE — one of the most stretched readings in the file.
The single biggest forward-looking change in open contracts was on the call side, though: the September 25 $28.50 calls added 7,085 contracts to 9,602 on 818 traded, effectively building this week's call wall in one session, while the October 2 $28.50 calls added 5,992. On the other side, the September 25 $27.50 puts added 1,549 contracts on 2,469 traded. Into Friday's expiration — settled history, not a live level — the $28.50 calls shed 9,928 contracts and the $27 calls 1,688 as those positions ran off. Total option volume ran at just 0.73× its 20-day average even as share volume printed 2.22× its own 20-day average; the flow was thin relative to the tape.
One piece of context worth holding: the short- and long-term trend reads agree in only one direction. Over roughly 50 sessions PFE is up 14.1%, and the stock sits 3.9% above its 50-day moving average and 5.3% above its 200-day. Over the past week and the past month, price is flat. The bigger trend is intact and the near-term drift is the only thing in question — which is exactly the environment defined-risk, range-friendly structures are built for. A momentum crossover turned back up on September 15, but the daily flow composite has already drifted back to roughly neutral, so treat that turn as tentative.
Expected move
The expected move — the move the options market is pricing in, derived from what straddles cost — is about ±$0.71, or ±2.58%, into the September 25 expiration. That is the $26.95–$28.37 range in the quick-answer table.
| Expiration | Implied move | Range around $27.66 |
|---|---|---|
| September 25 (7 days) | ±2.58% | $26.95 – $28.37 |
| October 2 (14 days) | ±3.61% | $26.66 – $28.66 |
| October 16 (28 days) | ±5.77% | $26.06 – $29.26 |
The ladder steps up smoothly — no humps, no kinks. Each rung roughly tracks the square root of time, which is what a chain looks like when no scheduled event is being priced between the rungs.
Volatility
At-the-money implied volatility is 20.91% with an IV rank of 19.6/100 — option prices are cheaper than roughly 80% of the past year's readings — and an IV percentile of just 7.9, meaning PFE has closed with lower implied vol on only about 8% of the last year's sessions. The September 25 rung itself prices even lower, at 18.6%. The front-month read is unavailable today because Friday was an expiration day, so the usual comparison of near-dated against 60-day option prices can't be computed; the 60-day figure, 25.04%, is comfortably above the front of the curve, which is the normal, calm shape.
Realized movement has collapsed. Twenty-day realized volatility is 17.19% and the 10-day figure is 13.63% — and compared against this stock's own recent history, that 20-day reading is unusually depressed for PFE. The ratio of 5-day to 20-day realized volatility is 0.44, meaning the last week of actual movement has run at well under half the pace of the prior month. That is the "vs its own norm" context that matters here: unusually quiet for Pfizer, not versus the broader market.
Premium rich or cheap. The gap between what options are priced for and what PFE has actually delivered — the volatility risk premium — stands at about 3.7 vol points in the market's favour, which is richer than roughly 74% of this stock's own recent readings. When that gap is positive, sellers of options have been collecting more than the realized movement cost them. Note how it got there: two sessions before the snapshot the gap was essentially zero, and it jumped to +3.6 and then +3.7 points not because options got more expensive (implied vol fell) but because realized movement dried up. That is a mechanical widening from the realized side, and it is the one piece of evidence that argues for collecting premium rather than owning it this week — IV rank of 19.6 on its own would say the opposite. The snapshot reading of the same gap is also well above its own norm, reinforcing the point. On balance: sell premium in small, defined size, and don't pay up for long options into a stock that has stopped moving.
Skew and sentiment
Skew — the fact that puts and calls the same distance from the stock price don't cost the same — is running the unusual way for PFE. The 25-delta put trades at 20.05% implied volatility against 22.26% for the 25-delta call, so calls are about 2.2 vol points richer than puts. Against this name's own 60-day median of roughly 2.1 vol points of call richness, that is almost exactly normal for Pfizer, and slightly flatter than the 7-day average of 3.4 points. Translation: nobody is paying up for crash protection here. Upside calls remain the pricier side of the chain, and the flow that built the $28.50 call wall is consistent with that.
Sentiment across expirations is mixed and split by term. The 0–7 day bucket scores modestly negative — driven by call open interest running off faster than put open interest into Friday's settlement — while the 7–30 day and 30–60 day buckets score firmly positive on call-side building and call-dominated delta-weighted flow. In plain terms: the very front of the curve leaned defensive on Friday, everything past next week leaned constructive. That tension is exactly why the composite lands near neutral instead of picking a side.
The key levels map
| Level | Price | Why it matters |
|---|---|---|
| 52-week high | $29.21 | 5.31% above spot; also the upper structural resistance level in the price data |
| Call wall (September 25) | $28.50 | Heaviest call open interest for this expiration (9,602 contracts) — and it was built Friday with +7,085 added |
| Swing resistance | $28.40 | Nearest heuristic resistance cluster from recent price pivots |
| Top of implied range | $28.37 | The upper rail of the ±2.58% expected move into September 25 |
| 20-day moving average | $28.06 | Price sits 1.42% below it — the kill switch for this week's read |
| Gamma flip estimate | ≈$28.00 | One rough estimate of the pivot in dealer hedging; also the chain's second-largest gamma strike |
| Spot / Friday close | $27.66 | Sits 1.2% under the estimated flip — an unremarkable distance for this name |
| Swing support | $27.64 | Nearest heuristic support, effectively at the money |
| Max pain (September 25) | $27.50 | Where the most option value would expire worthless; expirations sometimes gravitate toward it |
| Swing support | $27.23 | Next pivot cluster below — the first real shelf if $27.50 gives way |
| Largest gamma strike | $27.00 | Biggest combined gamma-weighted open interest across the whole chain |
| Bottom of implied range | $26.95 | The lower rail of the ±2.58% expected move |
| 50-day moving average | $26.62 | 3.9% below spot; the bigger uptrend's first real test |
| 200-day moving average | $26.27 | 5.28% below spot; longer-term structure remains intact above it |
| Put wall (September 25) | $25.00 | Heaviest put open interest for this expiration (3,673) — and the whole chain's put wall too (163,234) |
Two disagreements are worth naming. The September 25 expiration's own call wall is $28.50, but the whole chain's heaviest call strike is $30.00 with 167,104 contracts — that's a longer-dated magnet, not this week's ceiling. And the September 25 put wall at $25.00 is so far below spot (9.6%) that it is not a usable weekly reference; for the next five days, the $27.00 gamma cluster and the $26.95 range floor are the levels that actually matter on the downside.
Positioning and unusual flow
One rough estimate of dealer positioning puts net gamma positive both for the chain overall and for the September 25 expiration specifically, with the estimated flip level near $28.00. In that regime, market-maker hedging tends to dampen moves rather than amplify them — it leans toward pinning price inside the corridor. Treat this as an estimate built on an assumed convention about which side dealers are on, not as observed inventory.
Three flow items stood out on Friday, all of them still live:
- September 25 $27.50 calls — 3,387 contracts traded against 1,712 open, about $120,000 of premium and the heaviest dollar flow at this expiration. Turnover nearly double the existing position means fresh money, not maintenance.
- September 25 $27.50 puts — 2,469 traded, open interest up 1,549 to 2,640, roughly $53,000 of premium. The two together say traders are positioning around the max-pain strike from both sides.
- September 25 $28.50 calls — 818 traded but open interest up 7,085, the largest non-expired open-interest change in the file. That is the single build that created this week's call wall.
3 · Technical check
Both chart models point the other way from the options read, which is the most interesting thing on the page. The 3-day model (target date September 23) is bullish with a target of $27.85 and a projected range of $27.25–$28.15, citing RSI recovering from the September 18 low back to the midline and a MACD histogram that has flipped positive. The 5-day model (target date September 25, matching our expiration) is also bullish, same $27.85 target, projected range $27.05–$28.15, built around a tight Bollinger squeeze resolving upward. Both flag a weak ADX near 12.8 — a range-bound, low-conviction tape — and both name $27.75 as the resistance that must be cleared and roughly $27.36 as the level whose loss kills the bullish case.
Classification: diverges on direction, agrees on magnitude. The chart models want higher, our positioning read tilts lower — but their $27.85 target sits comfortably inside the options market's $26.95–$28.37 rails, and their projected range is narrower than the options', meaning neither side expects much. The gap that resolves the question is small and specific: a close above $27.75 would validate the chart models and put the 20-day average at $28.06 directly in play; failure there leaves the max-pain pull at $27.50 in control.
Model vs. Market: The options market implies $26.95–$28.37 into September 25; the 5-day technical model targets $27.85 within a projected $27.05–$28.15. The chart is asking for a 0.7% drift up, the options are pricing 2.6% of noise either way — the disagreement is about direction, not size, which is exactly the setup where selling the wings beats guessing the arrow.
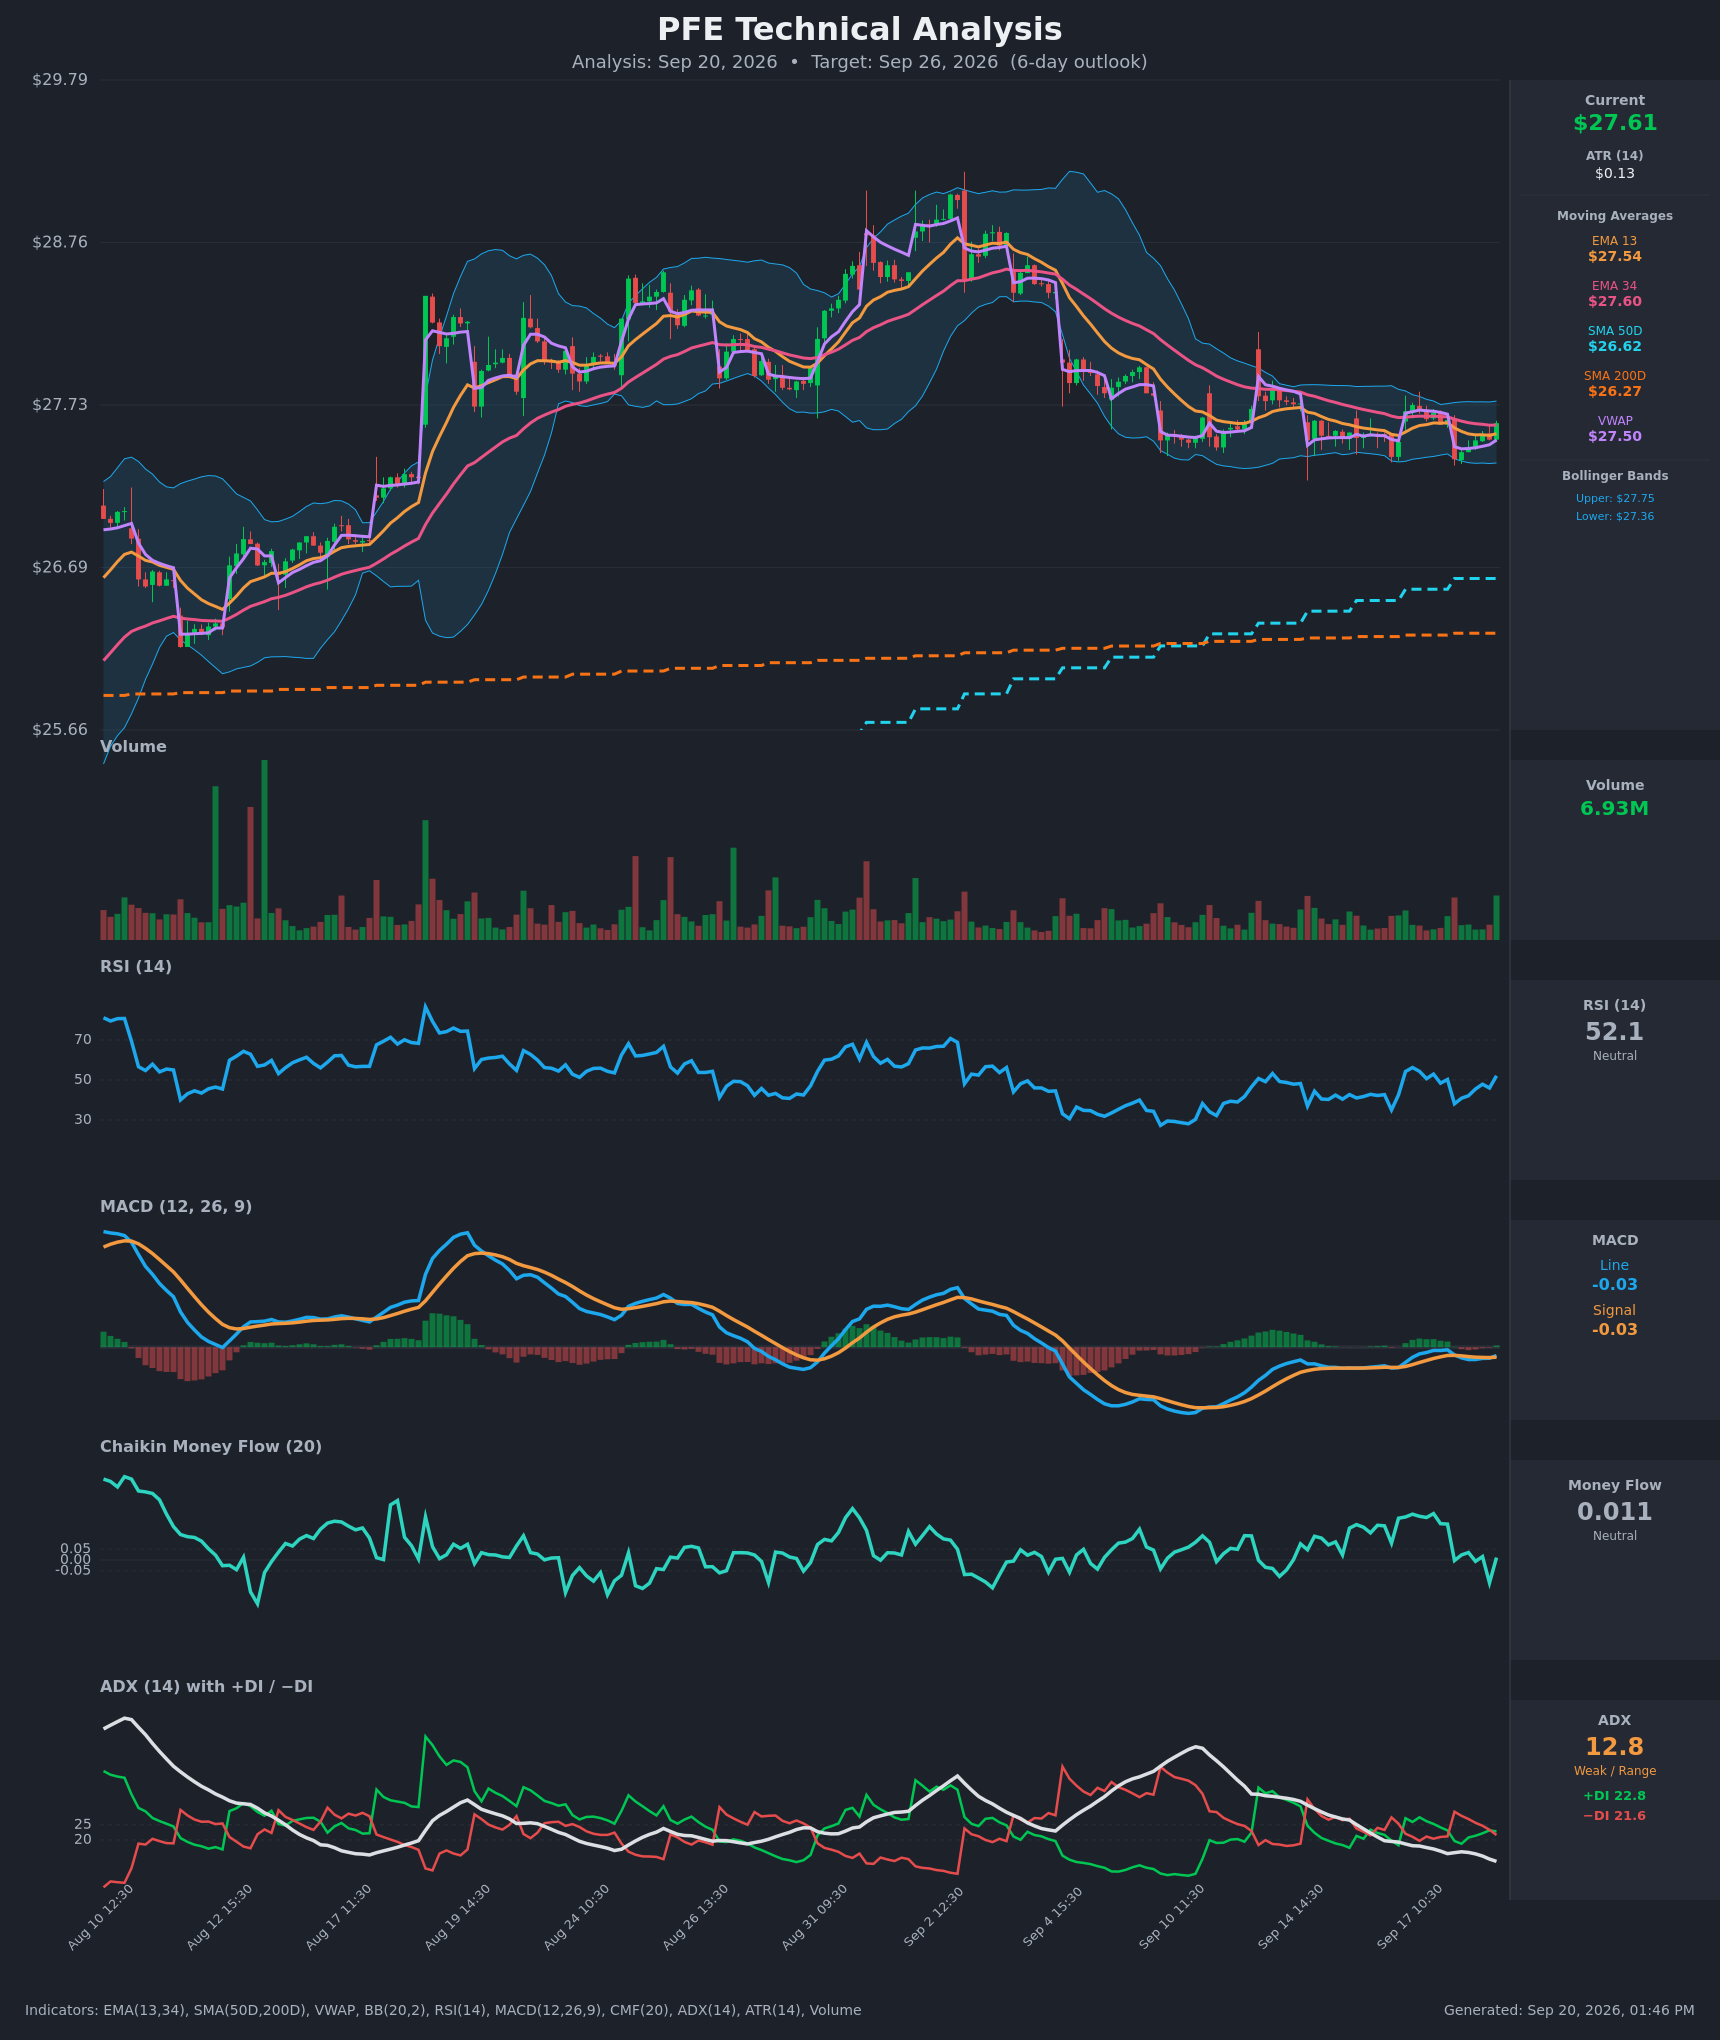
How the technicals shaded the strikes below: the bullish chart read is why the bearish structure's short strike sits at $27.50 rather than lower, and why the neutral condor's put side is placed at $27.00 rather than tighter — the models' $27.36 floor deserves respect even if we lean the other way.
Full technical write-ups: 3-day report → · 5-day report →
4 · Three ways the next five days can go
If PFE pushes above the call wall ($28.50): that strike carries the heaviest call open interest for this expiration and was built in a single session, so the positioning there is fresh and concentrated. Heavy call open interest overhead tends to slow rallies as hedging flows lean against the move; a clean break through it leaves thinner positioning until the 52-week high at $29.21. Getting there requires clearing $28.06 and $28.40 first, which is more than the implied move allows for in five sessions.
If PFE drifts between the walls: this is the base case the data supports. Max pain sits at $27.50, sixteen cents under Friday's close, the estimated dealer gamma regime is positive (hedging that dampens rather than amplifies), and realized movement has collapsed to under half its monthly pace. Expiring open interest and hedging flows in that regime tend to pull price toward the $27.00–$28.00 gamma cluster, with $27.50 the centre of gravity.
If PFE breaks below the $26.95 range floor: the September 25 put wall at $25.00 is too far away to act as this week's backstop, so the relevant references are the $27.23 swing shelf and then the $26.95 lower rail. Spot sits about 1.2% under the estimated $28.00 flip level — an ordinary distance for this name, not a stretched one — and below that pivot one rough estimate suggests market-maker hedging shifts from cushioning selling to amplifying it. A loss of $26.95 puts the 50-day average at $26.62 in view, which would be a bigger event than anything the five-day options pricing currently contemplates.
5 · Three defined-risk structures
Prices are end-of-day midpoints as of 2026-09-18. All structures are hypothetical. Verify live prices before trading — these will be stale by the open.
If you lean bearish: short call spread (leads, and here's why)
- Trade: Sell the September 25 $27.50 / $28.50 call credit spread — sell the $27.50 call, buy the $28.50 call. You collect a credit up front and keep it if PFE finishes below the short strike; the long call caps what you can lose.
- Credit: $0.315 ($31.50 per spread) · Max profit: $31.50 · Max loss: $68.50 · Break-even: $27.815
- Why it fits: It leads the list because premium is rich — options are priced about 3.7 vol points above what PFE has actually delivered, richer than roughly 74% of this stock's own recent readings — and because the short strike sits exactly at the $27.50 max-pain level with the $28.50 call wall as the long leg's anchor. The bias tilts mildly lower; this expresses that without needing a decline, only the absence of a rally past $27.815.
- Makes sense only if: you think $27.75–$28.06 caps the tape this week. Both chart models want exactly that zone tested, so this trade is deliberately fighting the technicals — size it accordingly.
- Invalidated if: PFE closes above $28.06.
- Managing it: take profits at roughly 50% of the credit; re-evaluate at the September 23 checkpoint, where the 3-day chart model's target date lands; if PFE closes through $27.50, close rather than hope — the short-term trend read is fighting a 50-day uptrend that is still up 14.1%, which argues for taking money early rather than holding to expiry.
- Liquidity note: the $27.50 calls quoted 32–39 cents, 7 cents wide, on 3,387 contracts and about $120,000 of premium — the most active contract at this expiration. The $28.50 calls quoted 3–5 cents; 2 cents wide is huge relative to a 4-cent mid, so work the spread as a package at the mid and expect to give up a cent or two.
- Analyze this position →
If you expect the range to hold: iron condor
- Trade: Sell the September 25 $27.00 put, buy the $26.00 put, sell the $28.00 call, buy the $29.00 call. Four legs, one net credit, and you keep it all if PFE finishes between $27.00 and $28.00.
- Credit: $0.165 ($16.50) · Max profit: $16.50 · Max loss: $83.50 · Break-evens: $26.835 and $28.165
- Why it fits: the short strikes bracket the $27.50 max-pain level and sit inside the $26.95–$28.37 expected-move rails; the $27.00 strike is the chain's largest gamma cluster and the $28.00 strike is the estimated flip level, so both short legs sit where hedging flow is heaviest. The positive dealer-gamma estimate and the collapse in realized movement are the two conditions this structure needs.
- Makes sense only if: you accept a modest reward against a large defined risk in exchange for a wide profit zone. This is a low-absolute-dollar trade on a $27 stock — the ratio is the honest reason to size it small or skip it.
- Invalidated if: PFE closes beyond either break-even — above $28.165 or below $26.835.
- Managing it: close at about 50% of max credit; exit the whole package by September 24 regardless rather than carrying four legs into expiration-day gamma; if one side is breached, close that vertical instead of rolling.
- Liquidity note: the $27.00 puts quoted 7–9 cents on 1,260 contracts and the $28.00 calls 11–13 cents on 2,295 — both 2 cents wide. The $26.00 put (1–2 cents) and $29.00 call (1–3 cents) are the slippage risk; on a four-leg package expect to pay a few cents versus theoretical mid, which is material against a $16.50 credit.
- Analyze this position →
If you lean bullish: short put spread
- Trade: Sell the September 25 $27.50 / $26.50 put credit spread — sell the $27.50 put, buy the $26.50 put. You collect a credit and keep it if PFE finishes above $27.50; the long put defines the loss.
- Credit: $0.19 ($19.00) · Max profit: $19.00 · Max loss: $81.00 · Break-even: $27.31
- Why it fits: this is the structure that agrees with both chart models. The short strike sits at max pain, so it profits from the pin as well as from a drift up, and the break-even at $27.31 sits below the chart models' own $27.36 invalidation level. Selling it also harvests the same rich premium the bearish spread does.
- Makes sense only if: you read the September 15 momentum turn and the MACD flip as real. Our positioning read tilts the other way, which is precisely why this appears third rather than first.
- Invalidated if: PFE closes below $27.23.
- Managing it: take 50% of the credit; exit by September 24 to avoid expiration-day assignment risk on an at-the-money short put; close rather than roll if $27.23 gives way.
- Liquidity note: the $27.50 puts quoted 19–24 cents, 5 cents wide, on 2,469 contracts and about $53,000 of premium — the second-most-traded contract at this expiration. The $26.50 puts quoted 2–3 cents. Enter as a spread, not two legs.
- Analyze this position →
If none of these: no trade
Premium is genuinely rich relative to delivered movement, and no scheduled event is distorting that reading — so the case for selling something is real. But "rich" is relative to Pfizer's own recent norm, not to the option market at large: an IV rank of 19.6 and an IV percentile of 7.9 mean the absolute dollars on offer are tiny. The bearish spread's $31.50 of credit is the largest of the three, and the condor's $16.50 against $83.50 of risk is a ratio that a single wide fill can ruin. If your commission and slippage on a four-leg package in a $27 stock runs more than a few cents, the edge is gone before the trade starts. Standing aside beats selling premium here when your fills are poor, when you can't size to at least a handful of spreads, or when you'd rather wait for the corridor to resolve above $28.06 or below $26.95 and trade the level instead of the noise.
6 · Quick FAQ
What is PFE's expected move this week? About ±$0.71, or ±2.58%, into the September 25 expiration — a $26.95 to $28.37 range, derived from what at-the-money straddles cost as of the September 18 close.
Is PFE expected to go up or down over the next five days? Options positioning as of September 18 leans neutral with a slight bearish tilt — put open interest is building faster than call open interest and spot sits in the upper half of the week's wall corridor — but that is a read of what traders have done, not a forecast. The actionable map is the $26.95–$28.37 range, the $27.50 max-pain magnet, and the $28.50 call wall.
Are PFE options expensive right now? Two lenses, two answers. IV rank of 19.6/100 says option prices are lower than about 80% of the past year's readings. But they are running roughly 3.7 vol points above the movement PFE has actually delivered — richer than about 74% of this stock's own recent readings — because realized movement collapsed faster than implied volatility did. Net verdict: modestly favours collecting premium in small, defined size rather than owning it.
Where is PFE's biggest options support and resistance? For the September 25 expiration, the put wall is $25.00 and the call wall is $28.50. The $25.00 wall is too far below spot to matter this week — the practical downside references are the $27.00 gamma cluster and the $26.95 range floor.
What invalidates this week's read? A close above $28.06 — reclaiming the 20-day moving average would put the $28.50 call wall in play and hand the week to the chart models.
Methodology & disclosures. Data: end-of-day options-chain snapshot for PFE, 2026-09-18, generated 2026-09-20T13:46:04.139Z. Prices shown are midpoints and will differ from live markets. Momentum/positioning scores and volatility-premium comparisons are descriptive measurements of past option flow and past price movement — not investment advice, signals, forecasts, or guarantees. All trade structures are hypothetical. Every structure shown has a defined maximum loss; you can lose the entire max-loss amount. Options involve substantial risk and are not suitable for all investors.